
EB Daily Market Report - Friday, May 27, 2022
Spring Special
We are currently running our Spring Special, but it will only last through Monday, May 30th. Don't let it slip by, it's the best deal we offer all year! You can CLICK HERE for more details.
Executive Market Summary
- Futures were higher once again as the market continues its rebound from very oversold territory
- Commodities are mostly higher, though natural gas ($NATGAS, -6.26%) is backing off from the $9 level
- The 10-year treasury yield ($TNX) is down 4 basis points to 2.72% and is below its 50-day SMA for the first time since early March
- Aggressive sectors are in a leading role as technology (XLK, +2.21%) and consumer discretionary (XLY, +2.15%) rally
- All 11 sectors are higher, but energy (XLE, +0.45%) is the worst performer
- Computer hardware ($DJUSCR, +3.02%) is leading technology as Apple (AAPL, +3.06%) helps the cause, testing its 20-day EMA
- Growth vs. value (IWF:IWD) is higher for a third consecutive session as traders move into aggressive growth
- Boeing (BA, +3.22%) is guiding the Dow Jones higher, along with AAPL and Microsoft (MSFT, +2.06%)
Market Outlook
It's really difficult to buy into the secular bear market scenario when accumulation appears to be taking place in one of the most influential areas of the stock market. Transportation ($TRAN) has been declining significantly for the past two months, yet its AD line is moving to multi-month highs. That tells me that while we might be seeing early daily weakness in transports, there are plenty of buyers in the afternoon willing to step in. Check this out:
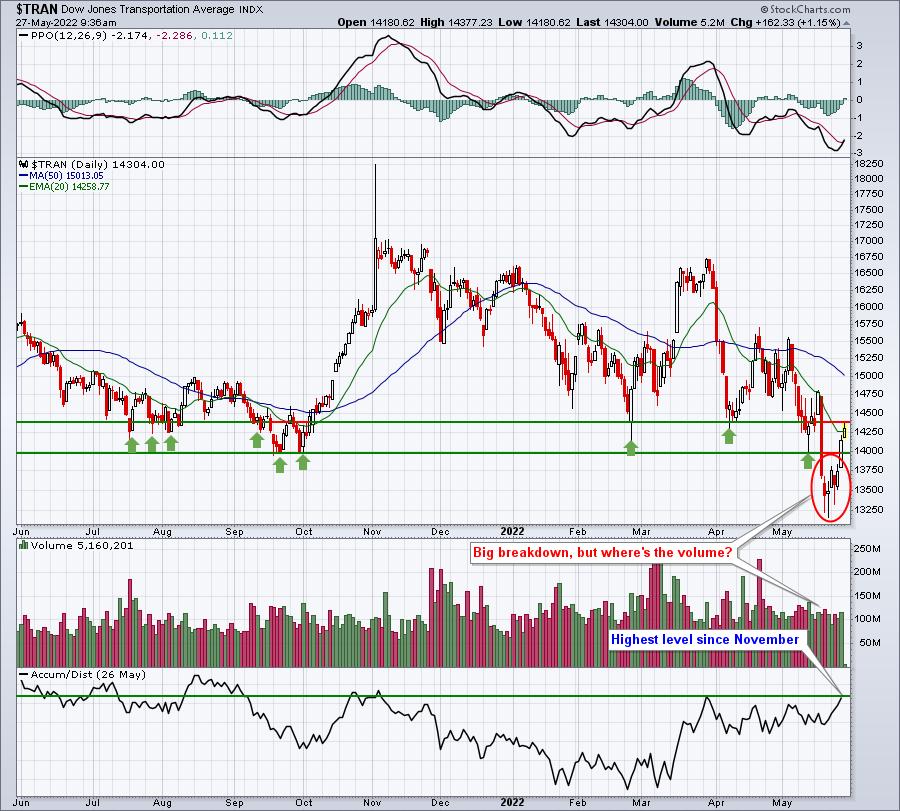
If transports have been accumulated throughout 2022, we have to ask ourselves why. It certainly wouldn't be because a secular bear market is looming.
Sector/Industry Focus
Travel & tourism ($DJUSTT) is a discretionary group that has been beaten up very badly in 2022, losing more than 40% of its index value from the November 2021 high to the recent low. It's rebounding now with the overall market and is quickly approaching its first big test of resistance:
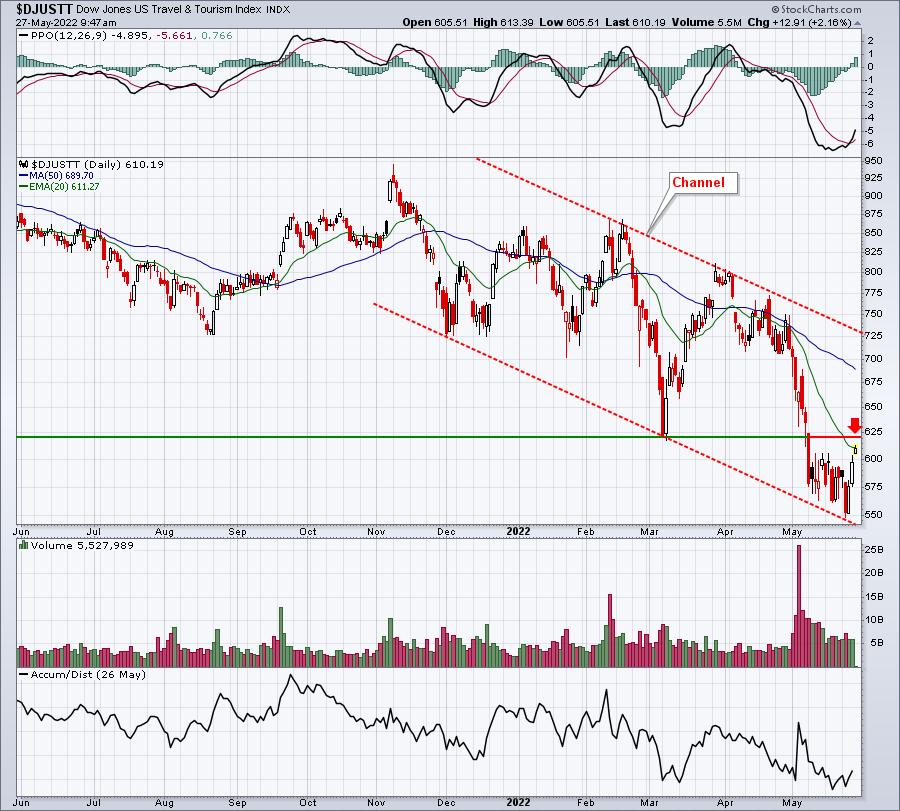
A break above key price resistance near 620 would also result in a break above its downtrending 20-day EMA. It's not out of the question that we'd see a test of the upper downtrend line within its current down channel. That could represent another 15-20% from here. But let's take it one step at a time. Can we get through the 20-day EMA and price resistance?
ChartLists/Strategies
If we do see continuing short-term strength, it would seem obvious to me that companies recently raising guidance could perform really well. From our Raised Guidance ChartList (RGCL), here are two interesting candidates:
PINC:
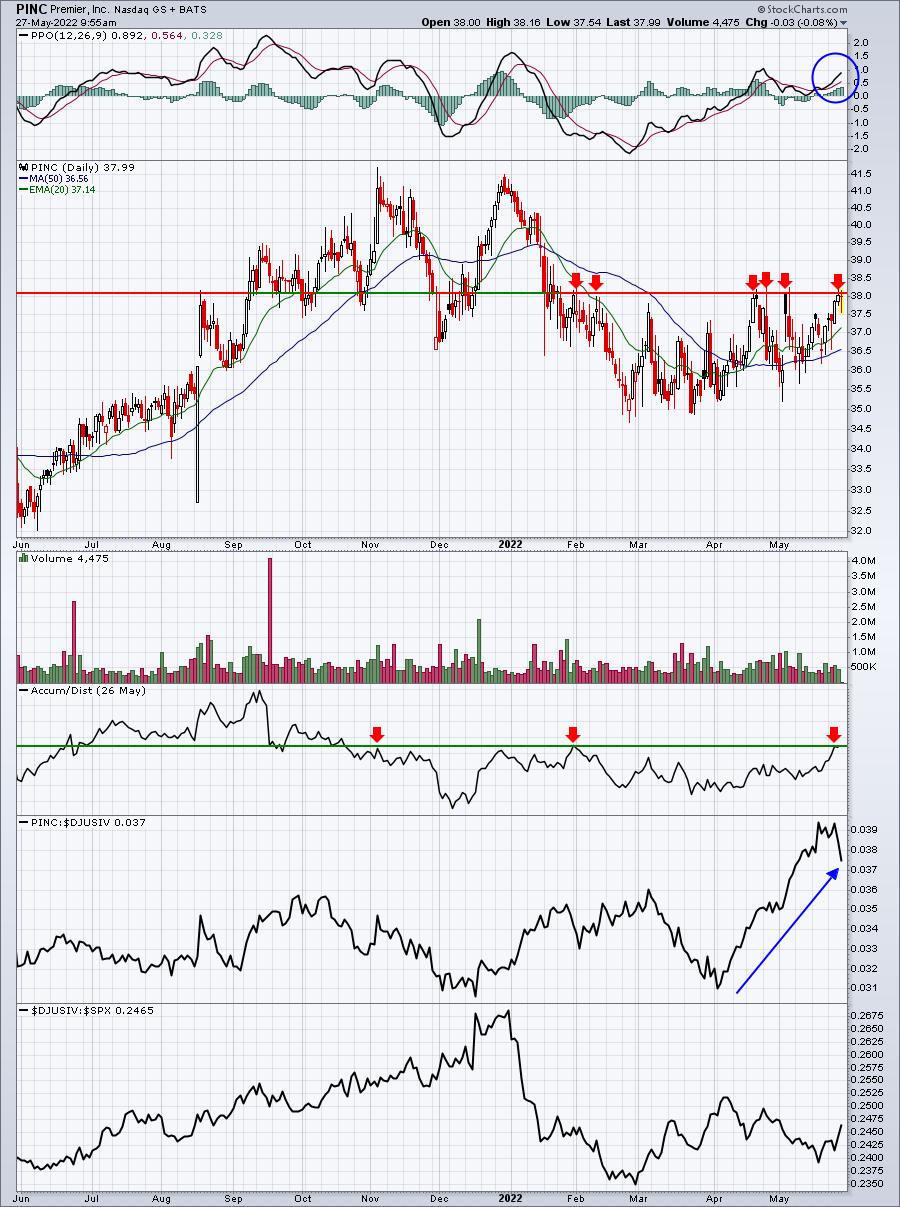
If PINC can close above key price resistance at 38.11, I believe it can run. It opened at 38.11 after it raised guidance, tested gap support and now is on the verge of a big breakout. The PPO is strengthening, as is the AD. A move through that 38.11 level would set PINC up for its highest close since January - quite bullish relative to the overall market.
RMNI:
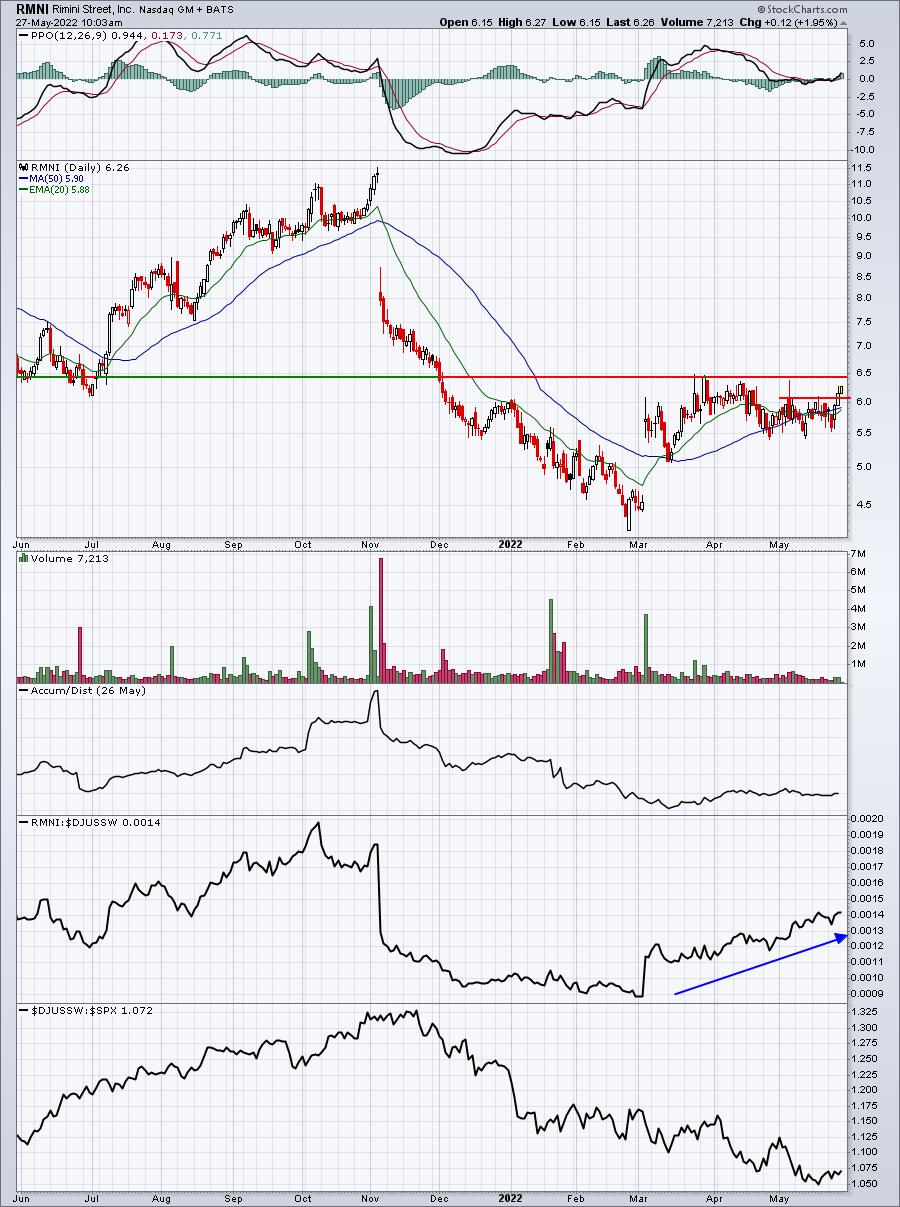
RMNI is showing relative strength vs. its software ($DJUSSW) peers. Closing price resistance is at 6.44. It hasn't closed above that level since November, so it's a big deal. Buying in ahead of the breakout is definitely more risky, but the market is in a risk-on mood right now, so perhaps the risk is worth it for some of you. 6.06 was the latest price breakout, so you might consider a closing stop there.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, May 27, 2022:
PDD, CGC
Tuesday, May 31, 2022:
CRM, HPQ, BEKE, CHPT, VSCO, AMBA, APPS
Economic Reports
April personal income: +0.4% (actual) vs. +0.6% (estimate)
April personal spending: +0.9% (actual) vs. +0.7% (estimate)
May consumer sentiment: (actual) vs. 59.1 (estimate)
Happy trading!
Tom