
EB Daily Market Report - Wednesday, June 15, 2022
Executive Market Summary
- Futures were higher overnight and those gains held through to the opening bell
- The 10-year treasury yield ($TNX) is down 7 basis points to 3.41% after the recent surge; many shorts are likely covering ahead of the meeting
- Cryptos may need to be renamed RIPtos the way they've been trading of late; if the overall stock market bottoms, I would suspect we're getting close to a bottom here as well
- Crude oil ($WTIC, -1.36%) is down to the $117 per barrel level
- Among sectors, communication services (XLC, +1.73%), consumer discretionary (XLY, +1.67%), and technology (XLK, +1.24%) - our three key aggressive sectors - are helping to lead today's gains
- Meanwhile, energy (XLE, -1.88%), which likely has the most to lose during options expiration week, is the primary laggard
- Boeing (BA, +7.15%) and Netflix (NFLX, +6.87%), two stocks benefiting from "max pain" as options approach expiration, are leading the S&P 500 higher today
- We're about to hear from the Fed in literally just a couple minutes, expecting to see either a 50-basis point or 75-basis point rate hike
Market Outlook
It's Fed day. How will the market react to what is likely to be a 50-basis point or 75-basis point hike? What will the Fed's language be? Will they provide any glimmer of hope that inflation is moderating? We'll soon find out.
I'm of the opinion that the S&P 500 has bottomed - or will bottom this week. I can't ignore the prospects of HUGE volatility with the upcoming Fed announcement, due out in minutes. I would keep an eye on this intraday (15-minute chart of June action) and watch the sustainability ratios in the panels below:
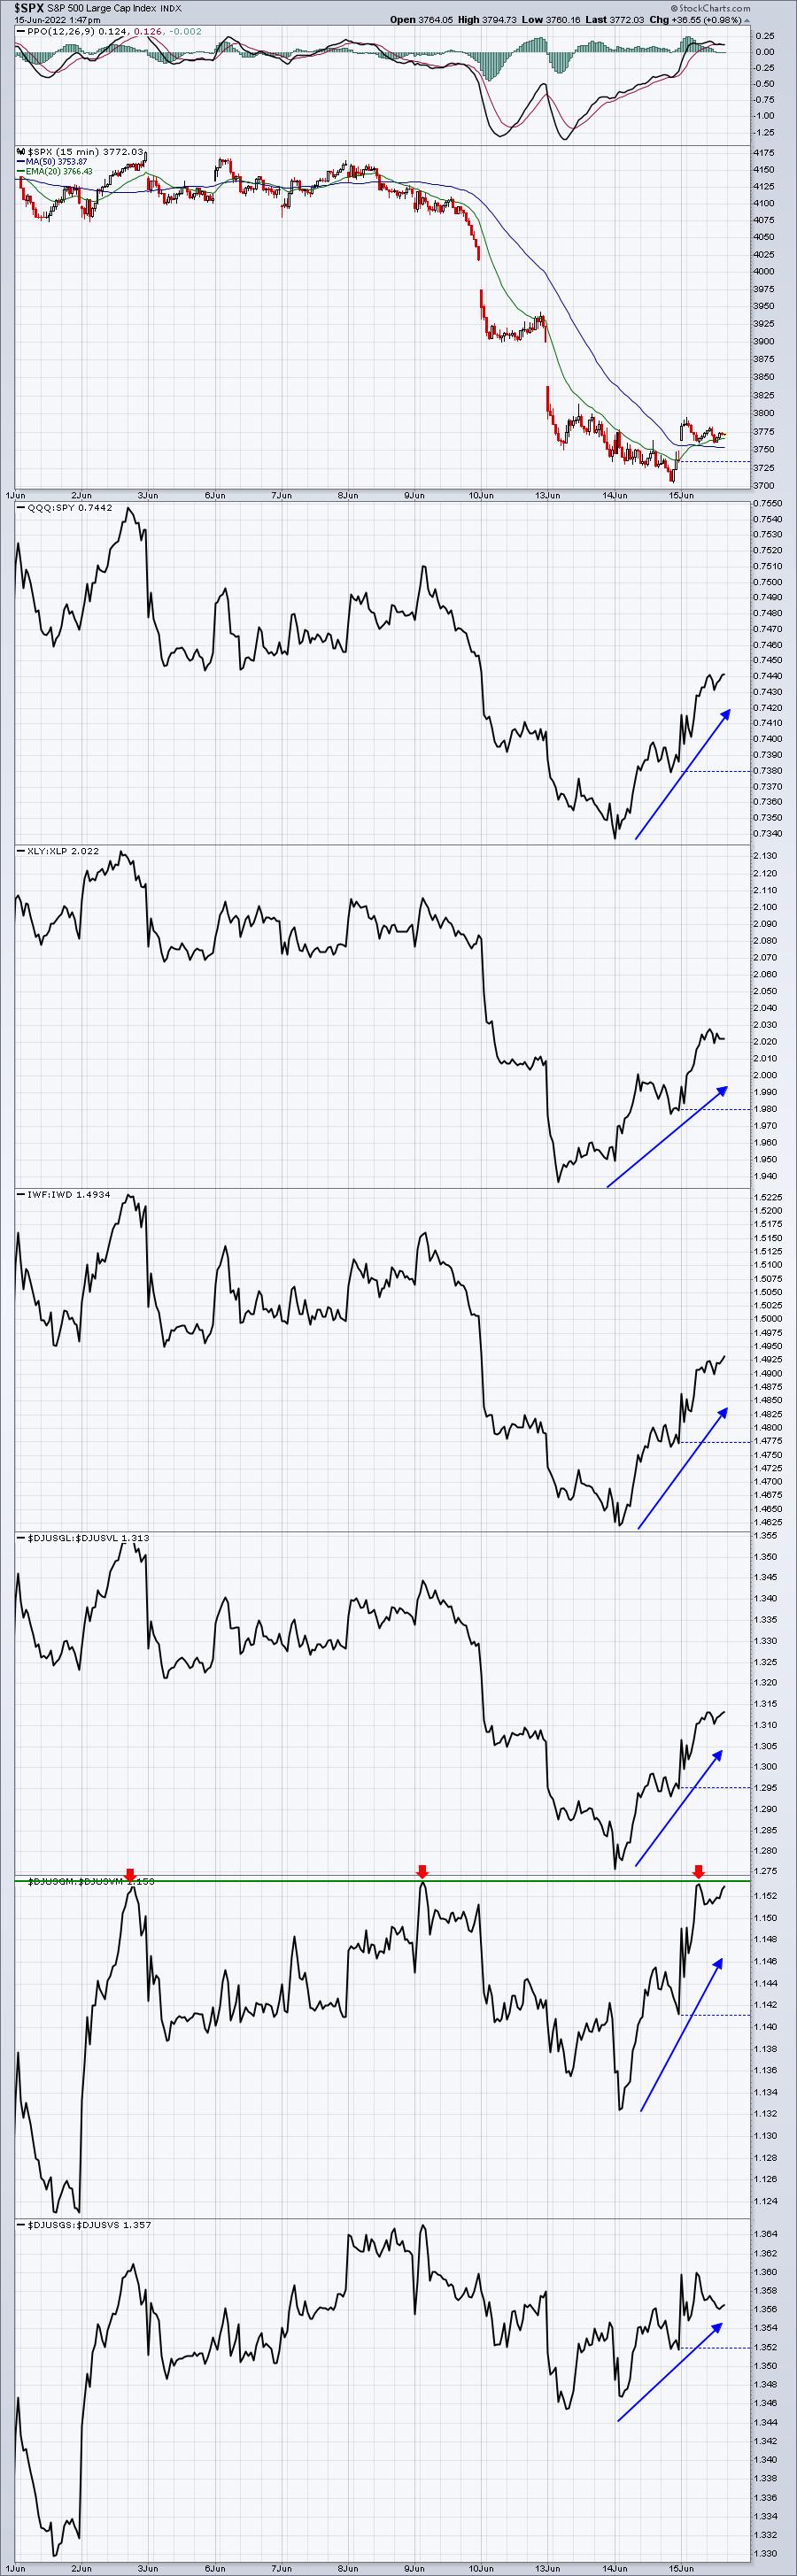
If the bottom falls out of these ratios after the meeting and into the end of the week, then I'm likely premature with my bottom call. But if these ratios continue moving higher and the May relative lows hold on these ratios, then I believe that U.S. equities are poised to rally in the second half of the year.
Sector/Industry Focus
If a bottom is in process of forming, then we are going to see significant rotation to recently underperforming industries. Staying on top of this will be critical to outperforming the S&P 500 over the balance of 2022. One industry that has really begun to spread its wings is delivery services ($DJUSAF):
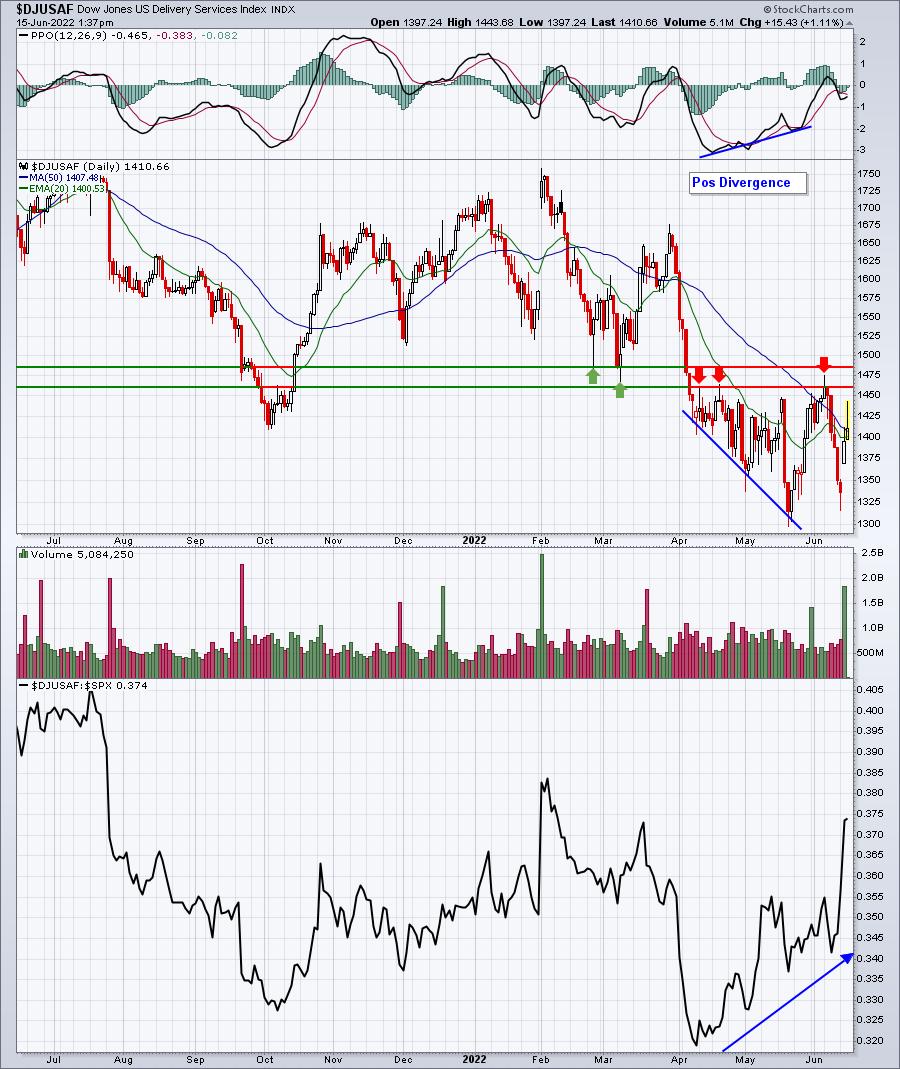
If you don't follow relative strength, many times you miss the rotation taking place in the market. The DJUSAF chart above does NOT look bullish to me, other than the evidence of slowing downside momentum (positive divergence). If we simply look at the absolute chart, we just see a downtrending chart. But that bottom panel highlights improving relative strength. I like this group, so look for stocks like FedEx (FDX) and United Parcel Service (UPS) to do well. Right now, FDX looks like the better relative performer.
ChartLists/Strategies
I'm focusing on the June max pain candidates for now, many of which are having solid days thus far. Of course, we should be expecting whipsaw action with the Fed announcement due out within the hour. It's very typical for volatility to be extreme with price action moving significantly in both directions - sometimes within minutes. I will be focusing more big picture to see how certain areas like growth vs value perform after the announcement.
If you missed last night's max pain event, Erin Webber provided an Excel spreadsheet that listed between 100-200 stocks, highlighting max pain levels. Be sure to check that out on our website. If you have any questions, reach out to Erin via "[email protected]".
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, June 15:
None
Thursday, June 16:
ADBE, KR, JBL, CMC
Economic Reports
May retail sales: -0.3% (actual) vs. +0.1% (estimate)
May retail sales less autos: +0.5% (actual) vs. +0.7% (estimate)
June empire state manufacturing index: -1.2 (actual) vs. 5.5 (estimate)
April business inventories: +1.2% (actual) vs. +1.3% (estimate)
June housing market index: 67 (actual) vs. 68 (estimate)
FOMC announcement at 2:00pm ET
Happy trading!
Tom