
EB Daily Market Report - Wednesday, June 22, 2022
Trading Places LIVE
I apologize for the late cancellation this morning of my Trading Places LIVE show. We were having technical issues with Zoom up until a few minutes before the show typically begins. I made the decision about 10 minutes before the show began to cancel it, packed up my computer and was about to head to Starbucks, and Erin informed me that we had resolved issues, were back up, and ready to go. Unfortunately, I wasn't prepared at that point, so we cancelled. Because of travel plans this weekend with family, I will not be available on Monday for TP LIVE either. Therefore, our next live show will be on Wednesday, June 29th at 9:00am ET.
My Schedule
As I mentioned above, I will be traveling this weekend. I'll be on the road out of town, driving all day on Thursday. Then I'll be driving home all day on Monday. Because of the critical time in the market, I'll no doubt be checking in from time to time over the next few days and I'll relay any concerns I might have to John Hopkins, who'll likely be providing a brief market update each day Thursday through Monday. I'll be back to my regular schedule on Tuesday.
Executive Market Summary
- Futures were weak overnight, but did cut losses into the opening bell
- All of our major indices began the morning in negative territory, but rotation still remains solid
- Real estate (XLRE, +1.52%) and health care (XLV, +1.26%) are the leading sectors today, while energy (XLE, -3.74%) and materials (XLB, -1.79%) lag
- Footwear ($DJUSFT, -3.21%) is struggling today and approaching a key price support level from May - see Sector/Industry Watch section below
- Software ($DJUSSW, +0.26%) is clinging to a gain and it's the only technology industry that's positive
- Crude oil ($WTIC, -2.83%) is roughly $106 per barrel, but is well off its worst levels of the session
- A number of health care names litter the S&P 500 leaderboard, including DaVita Inc (DVA, +4.80%) and Moderna (MRNA, +4.52%); the former appears to be simply bouncing after a horrific Tuesday
Market Outlook
We're at least getting a short-term bounce, which is a start to potentially carving out the bottom. I called the bottom last week, but I'm not at all suggesting it'll be a "V" bottom and we'll go higher every day. That's one possibility and I'd love it, but we need to view this as a process that could take some time. I believe the extreme bearish sentiment is helping us right now on the long side, but ultimately it'll be the story that rotation tells. It's that bigger picture that we need to remain focused on or market makers will get control of our emotions. And then it's over. Staying objective is critical. Let's look at how the aggressive sectors are performing on a relative basis vs. the benchmark S&P 500:
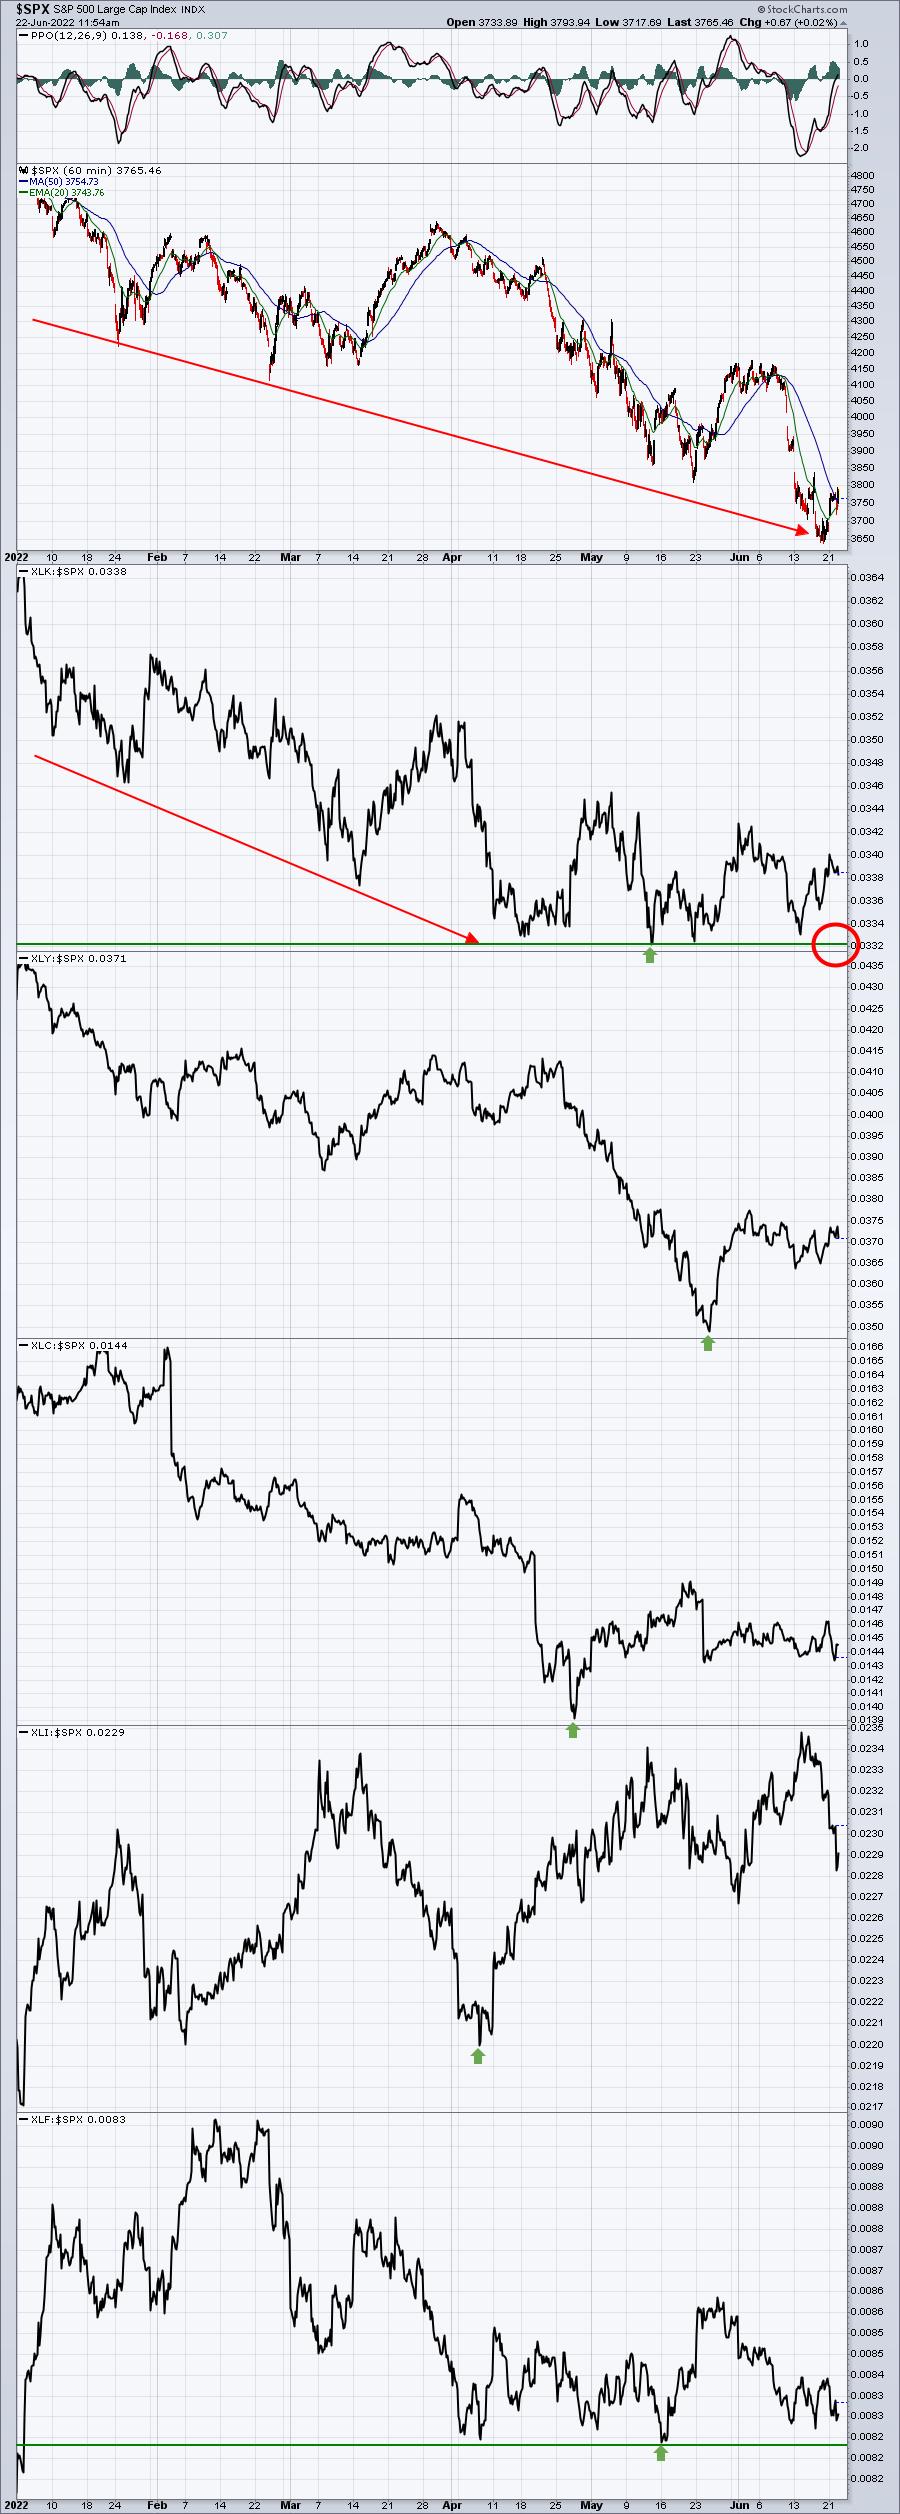
As the S&P 500 has fallen to new lows in recent months, all of these aggressive sectors have held their prior relative lows. This tells us that it is NOT aggressive groups leading the market to the downside. Technology (XLK) is, by far, the most influential sector with an S&P 500 weighting of 27%. As long as technology continues to outperform on a relative basis, it's going to be more difficult for the S&P 500 to set new lows. I'd keep a very close eye on the XLK:$SPX ratio.
Sector/Industry Focus
If the market bottom is in place, I'd expect to see more and more industries within aggressive sectors holding absolute price support and beginning to show relative strength. One industry that would benefit from a strengthening economy down the road would be footwear ($DJUSFT). Unfortunately, the group is not showing much absolute strength at the moment, but are there signs of rotation and accumulation?
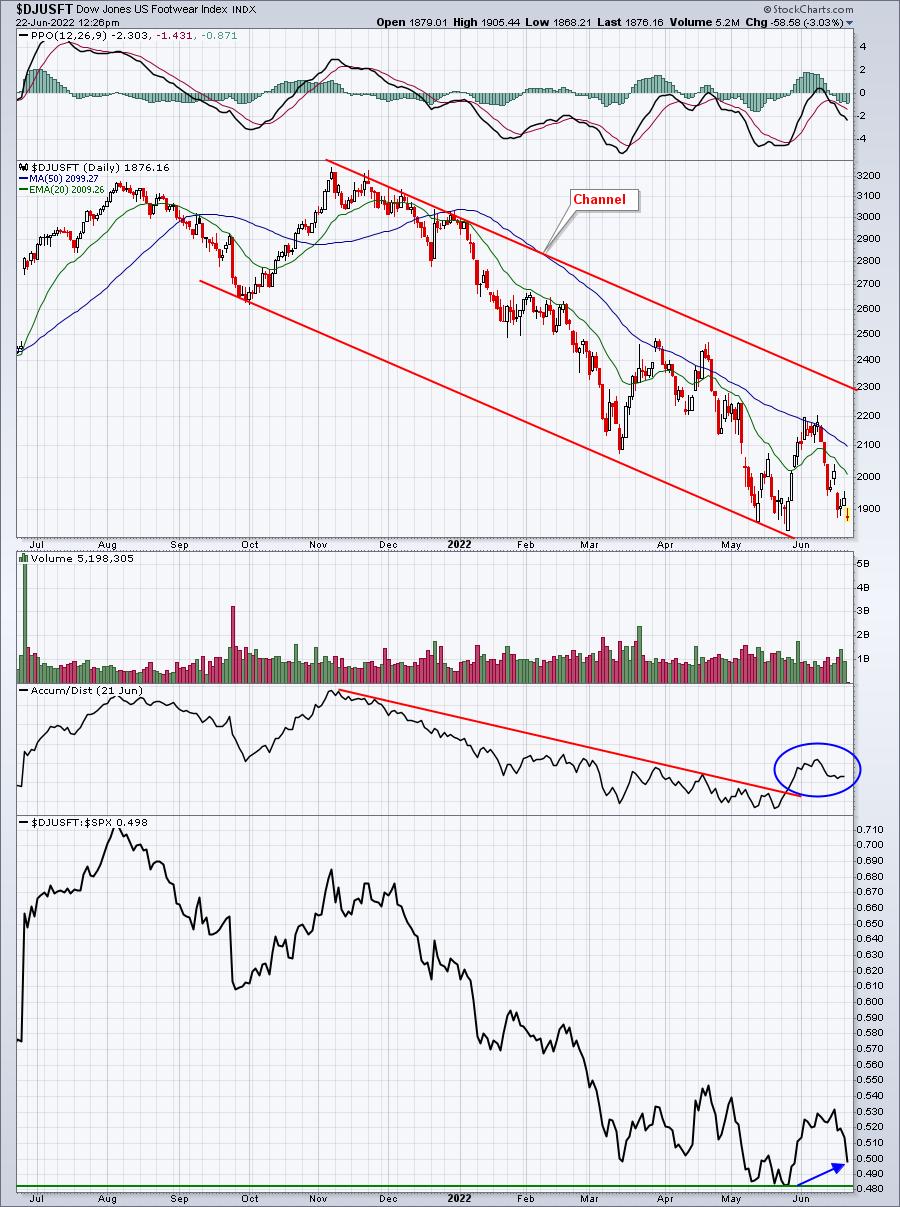
The downtrend in absolute price remains obvious. But are these subtle hints at a bottom?
- The blue directional line showing a higher relative line - the DJUSFT is actually at a level right now that would make a new closing low, but the relative strength is higher
- The AD line is well off its earlier low and appears to be holding up well during the latest absolute price decline
I'm seeing progress here, but nothing definitive. My point, however, is that as more and more of these aggressive industry groups show signs of a potential bottom, the more confident I'd grow about being heavily long in this market.
ChartLists/Strategies
The good news is that I am of the opinion that buying into riskier stocks now makes a lot more sense than at any point in 2022. The bad news is that the Volatility Index ($VIX) remains at 30 - extremely high on a historical basis. Market makers are likely to take advantage of retail traders, most of whom believe that the U.S. stock market can't go anywhere, but down. So taking long positions in stocks will require patience and allowing these stocks more wiggle room to the downside than what I've stressed in prior months. I kept talking about making sure entries were such that you could keep a tight stop. I now believe you have to be willing to give more room to the downside, which could be painful if stocks roll over and plunge further. I cannot make that risk call for everyone.
I like stocks that have already shown that an uptrend could be underway. I've mentioned Zoom (ZM) in several communications of late, but that's one of my favorites. Many software names are beginning to look somewhat similar to ZM. As an example, check out Gitlab Inc. (GTLB), which, like ZM, gapped higher with its latest earnings and now appears to be trending above its 20-day EMA:
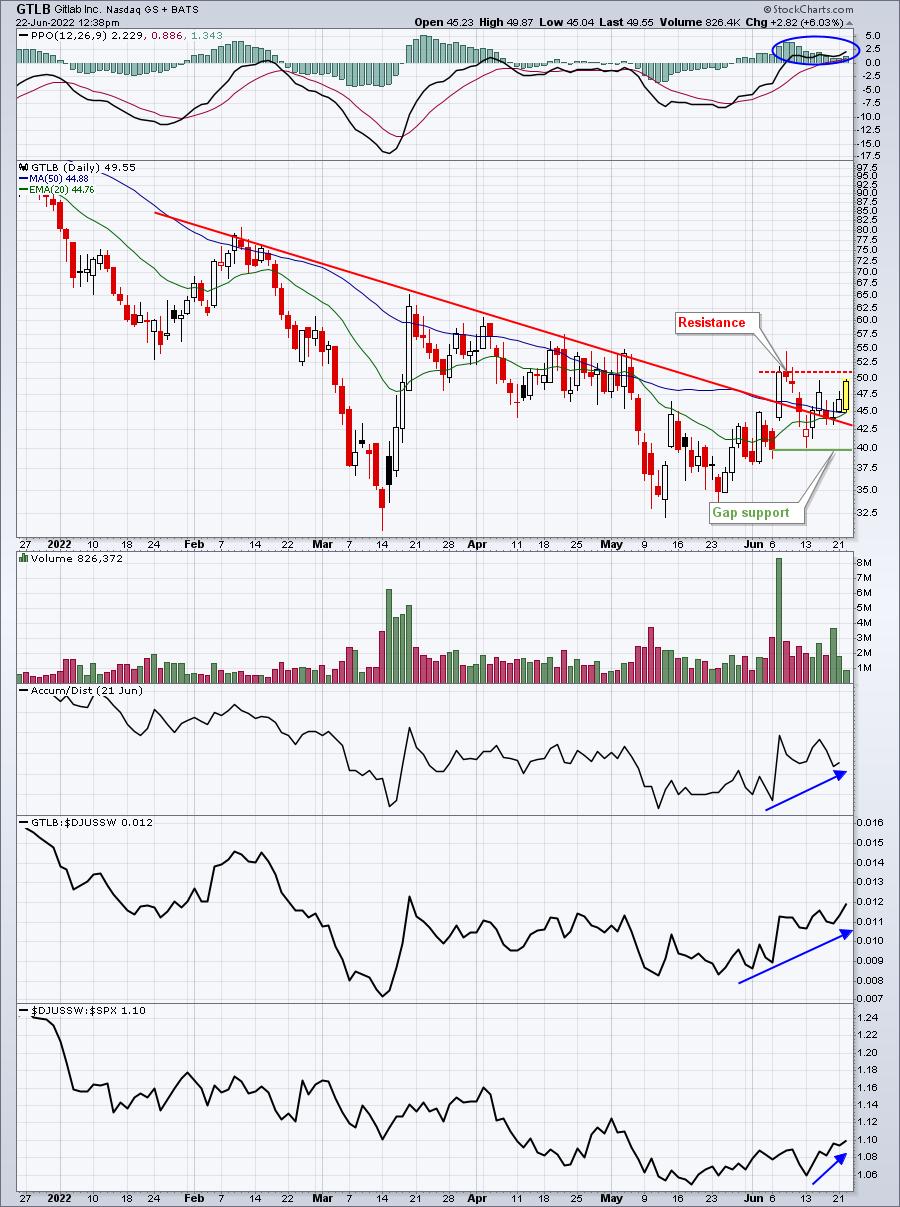
Short-term price resistance resides near 51, while major gap support is near 40. In November, GTLB traded at 135. It's emotionally difficult to pull the trigger on a stock like GTLB at 50, when it could have been bought at 40, or even close to 30. But you can't view it like that. Just as price was way ahead of itself to the upside in November, the selloff was likely overdone as well. We can only evaluate it based on where it is now and how it's performing and how it's industry group is performing. Both are improving.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, June 22:
FUL, KFY, KBH, WGO
Thursday, June 23:
ACN, FDX, DRI, FDS, BB, GMS, MEI
Economic Reports
None
Happy trading!
Tom