
EB Daily Market Report - Tuesday, July 26, 2022
ChartLists
I'm working today on updating various ChartLists and should have the links available for you tomorrow.
Executive Market Summary
- Futures were weak overnight and our major indices got off to a rough start
- Rotation continues in bearish fashion, matching what we've seen the past two sessions
- Walmart (WMT, -8.57%) cut guidance for Q2, citing inflationary pressures on consumers
- Most retailers are significantly lower today in sympathy with WMT
- The 10-year treasury yield ($TNX) is down 6 basis points to 2.76%, as money rotates back into treasuries - an interesting development ahead of the FOMC announcement tomorrow
- Crude oil ($WTIC, -0.40%) reversed course after trading higher earlier today
- Defensive sectors lead on a relative basis and with fractional gains, while consumer discretionary (XLY, -2.70%) takes the brunt of today's selling
- While WMT is a big drag on the Dow Jones, 3M (MMM, +6.42%) is partially offsetting that weakness after reporting solid quarterly results and announcing a health care spinoff
- Shopify (SHOP, -15.55%) was the latest technology company to announce layoffs
Market Outlook
The turn higher in the 5-day moving average of the equity only put call ratio ($CPCE) and the weakness in our sustainability ratios likely are contributing to the short-term market weakness. I've identified short-term price support and the rising 20-day EMA as our first critical test of the recent market rally. Here's a quick look at the NASDAQ 100 and where we stand:
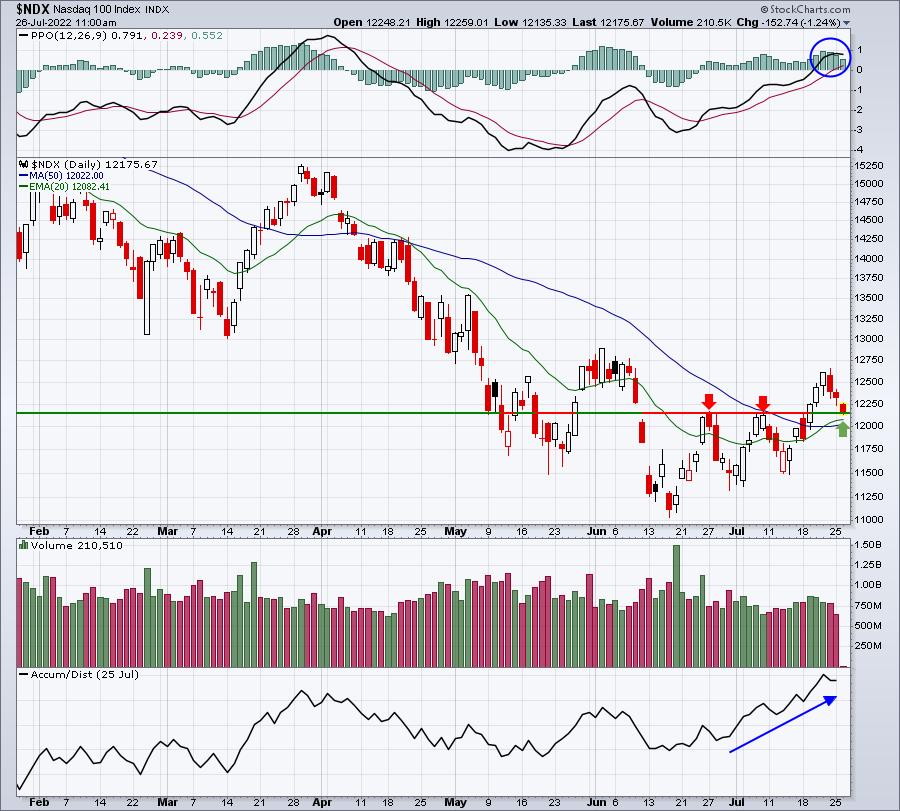
Listen, we know from our analysis of 2022 that the QQQ has performed MUCH better once we've passed the 10am mark in the morning. That's a big reason why that AD line is so strong. I'm looking for a big reversal back to the upside either later today OR after the Fed announcement on Wednesday. We'll see.
Sector/Industry Focus
Broadcasting & entertainment ($DJUSBC) is down today and has been down the past 3 sessions, but its technical outlook is MUCH improved over the past 6 weeks:
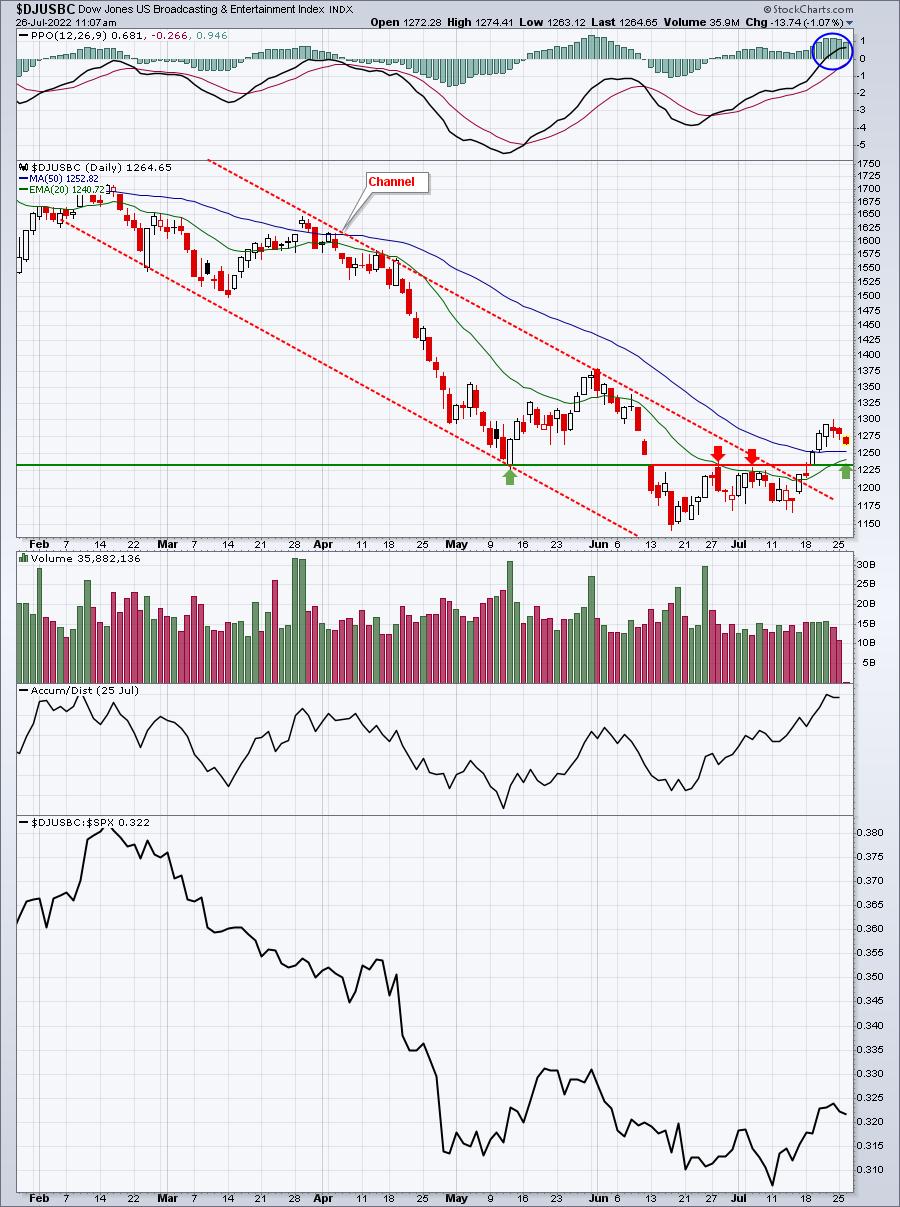
The DJUSBC has cleared price resistance and appears to be trending higher, despite the recent selling. The daily PPO has turned positive, so we have bullish short-term momentum. The key to sustainable rallies like this is holding the rising moving averages on pullbacks, then rebounding to new highs. That's the test facing the broadcasting and entertainment group this week as we prep for the next Fed announcement and interest rate hike.
ChartLists/Strategies
We are seeing the first key short-term test for this rally. The NASDAQ 100 ($NDX) has price support at 12158 and today's intraday low was 12135. Also, the NDX has its 20-day EMA at roughly 12080, so we're very nearly testing that key short-term moving average. Personally, I've taken a position in the QLD, which tracks the NASDAQ 100 at a 2 to 1 clip. This is an aggressive strategy that is certainly not for everyone. An obviously less aggressive strategy would be to buy the QQQ, which tracks the NDX at a 1 to 1 clip (no leverage). It would make sense to keep stops tight in the event selling escalates. I will likely exit my QLD if the NDX closes beneath its rising 20-day EMA.
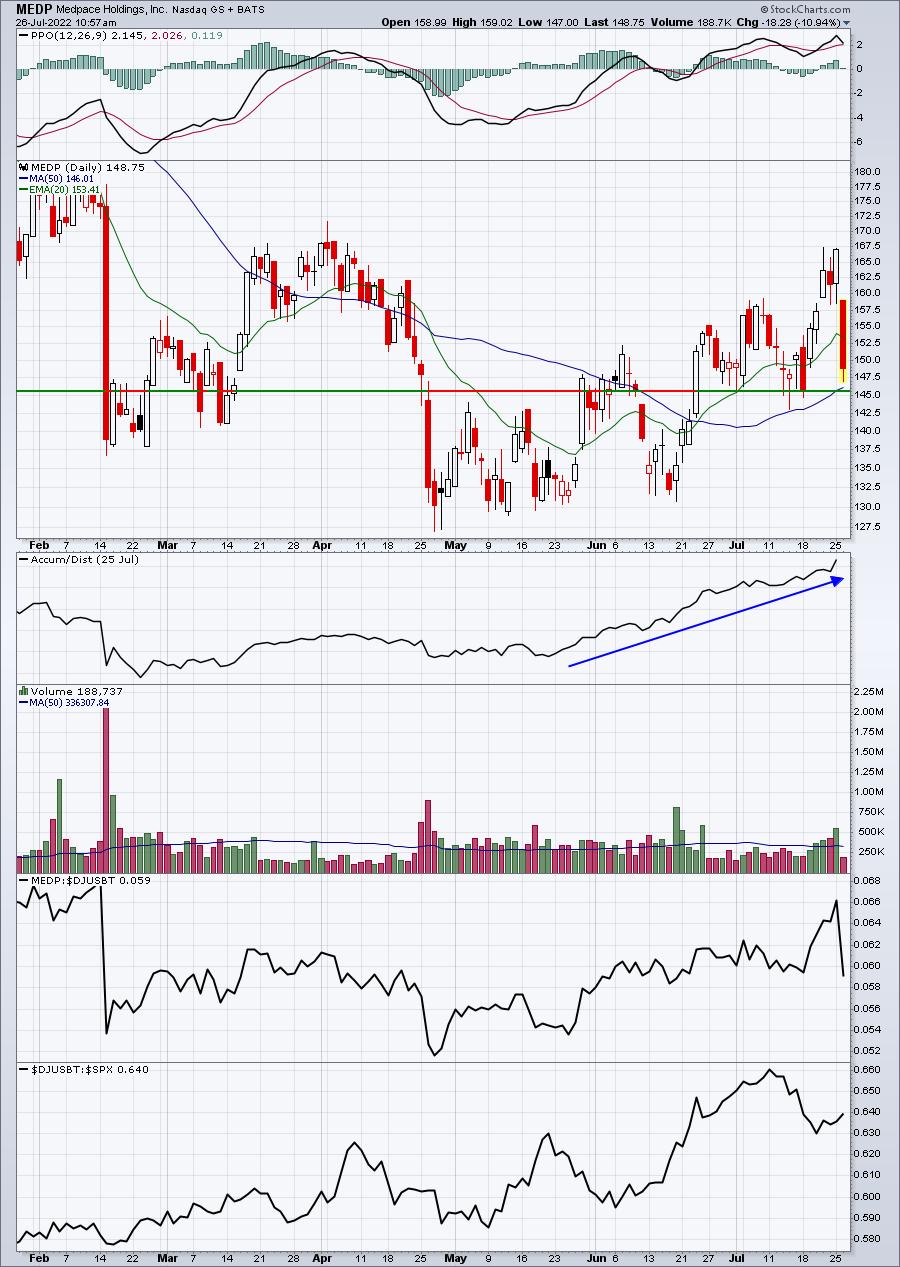
I also like to trade off of the Strong AD ChartList (SADCL) when we get morning weakness. Medpace Holdings (MEDP) reported revenues and EPS above expectations but issued cautious guidance due to foreign exchange impact. The selling, which reached approximately 13% this morning, seems a bit overdone and MEDP's AD line is quite strong. This suggests it has a habit of finishing in the top half of its daily trading range. A rally later today is a definite possibility. Again, this type of trade should be viewed as very aggressive and is not for everyone:
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, July 26:
MSFT, GOOGL, V, KO, MCD, UPS, TXN, RTX, MDLZ, CNI, CB, MMM, SYK, GE, FISV, UBS, MCO, CNC, GM, ECL, KMB, ADM, CMG, MSCI, ENPH, GLW, PCAR, EQR, AMP, CSGP, CAJ, FE, ESS, AGR, TRU, PARA, TER, IEX, UDR, ACI, BXP, PHM, HUBB, WSO, JNPR, ZION, PNR, MANH, ST, PII, WH, BYD, SKX, AXTA, TENB, TNET, IRDM, CVLT, XRX, NAVI, SSTK, SILK, NXGN
Wednesday, July 27:
META, QCOM, TMUS, BMY, BA, ADP, NOW, CME, SHW, LRCX, WM, HUM, GD, EQIX, NSC, BSX, F, AEP, SHOP, KHC, ORLY, APH, TEL, CTSH, LYG, HLT, VICI, ODFL, HES, OTIS, AVB, AWK, ROK, RCI, DRE, INVH, SPOT, ALGN, GPC, GRMN, GIB, MAA, RJF, URI, TDY, AEM, ICLR, ROL, CINF, MOH, HOLX, UMC, ACGL, SSNC, EQT, TYL, CS, AVY, BG, CSL, TECK, PTC, CHRW, ETSY, AR, QGEN, LW, RE, GGG, CCJ, FBHS, PAG, OC, TEVA, TDOC, MUSA, MKSI, OPCH, INFA, SLAB, DRVN, COLM, QS, IART, TPX, NCR, AMED, KGC, PEGA, R, TMHC, MMSI, FORM, MMYT, MXL, MC, UPWK, GPI, SIMO, SHOO, COUR, BOOT, PI, CCS, CAKE, LC, EXTR
Economic Reports
FOMC meeting begins, announcement due out on Wednesday at 2:00pm ET
May Case-Shiller home price index: +1.3% (actual) vs. +1.6% (estimate)
May FHFA house price index: +1.4% (actual) vs. +1.6% (prior)
July consumer confidence: 95.7 (actual) vs. 96.8 (estimate)
June new home sales: 590,000 (actual) vs. 664,000 (estimate)
Happy trading!
Tom