
EB Daily Market Report - Monday, September 19, 2022
Executive Market Summary
- Futures were weak to start a key trading week
- The Federal Reserve will begin its latest 2-day meeting tomorrow morning and will announce its rate hike and policy statement on Wednesday at 2pm ET
- There was another weak housing report today, and rate hikes won't help the homebuilding group
- Cryptocurrencies are down today, but have rallied considerably off their intraday lows
- Commodities are mixed and also well off their earlier lows; crude oil ($WTIC, +0.34%) was down more than 3% earlier
- The 10-year treasury yield ($TNX) is up 4 basis points to 3.49%, setting a fresh 11-year high just before the Fed meets
- Consumer discretionary (XLY, +1.09%) is leading the action today, as footwear ($DJUSFT, +2.88%) and home construction ($DJUSHB, +2.67%) lead the way
- Defensive groups are lagging, as real estate (XLRE, -1.36%) is today's worst-performing sector and approaches its mid-June low
- Moderna (MRNA, -8.42%) is the worst-performing S&P 500 stock
Market Outlook
One thing bears require in order to take prices significantly lower is increased fear. Many times, we'll see the Volatility Index ($VIX) move into the 30s as fear ramps up. Today, after gapping up to 27.69 and trading as high as 27.95, the VIX has reversed and is now lower by 2.21% to 25.72. The VIX has been struggling to clear 28. If we remain below 28, it will add to my bullish thesis for U.S equities heading into Q4. Here's the current look at the VIX:
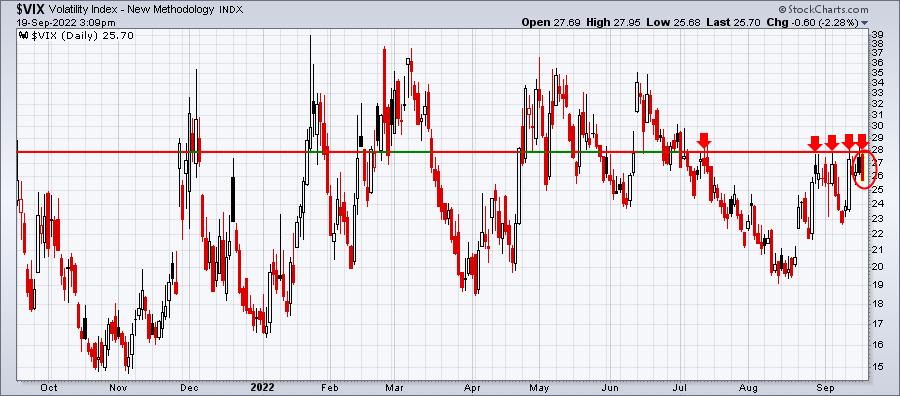
The consistent failures at 28 are a big deal. Without that additional fear, I just don't see the selling continuing for very long. And if the S&P 500 hangs onto its mid-June low of 3636 through the bearish month of September, I believe the path of least resistance will be back to the upside in Q4.
Sector/Industry Focus
There are a few housing market economic reports due out through Wednesday, as we await the Fed's latest rate hike and policy statement. Today, the September housing market index fell to 46 from August's reading of 49. Yet, the home construction index ($DJUSHB) is rallying. Check out the chart:
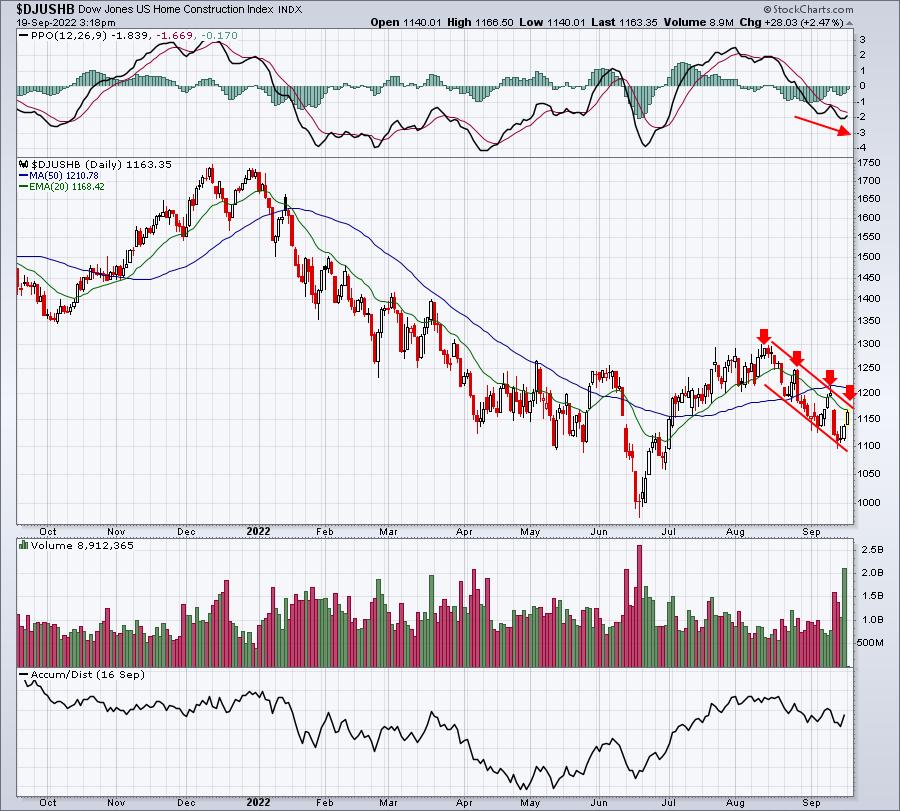
The downtrend remains intact, despite today's rally. Also, with the daily PPO setting a new low recently, the odds are greater that we'll see failure at the 20-day EMA and/or trendline resistance.
ChartLists/Strategies
As I mentioned last week, I'm a bit more cautious as we trade beneath 3900 on the S&P 500. We need to respect the short-term weakness, despite the fact that I still fully believe the mid-June was and will continue to be THE low for the 2022 cyclical bear market. While we're currently trending lower, I also see and recognize that our afternoon trading remains quite bullish. That suggests that Wall Street is happily buying shares offered up at the open and/or during the morning session. Distribution would take place throughout trading sessions, not just at the opening bell and first 30-60 minutes. I interpret this action as VERY bullish for the more intermediate- to long-term forecast.
Short-term, I believe it's important to trade stocks on the long side that are at or very near key price support. That's what I did with our Model Trades over the weekend. A question came in from a member. I'm paraphrasing a bit, but essentially the question is as follows:
"Tom, why do you suggest buying at the opening bell for the Model Trades when you've repeatedly discussed the early morning weakness?"
Well, my answer is this. I typically provide more than one entry, unless we're already at key support. If we're already at the best entry point on the chart, why wait for a lower price? Should the price fall much further, we'd be seeing a breakdown on the chart, in which case we certainly wouldn't want to buy. Remember, if the SPY or QQQ gaps lower at the open, it doesn't mean every stock in its universe will follow suit. Also, the opening price will benefit from the gaps lower that we've been seeing. What we DON'T want to do is buy stocks at the close and be subject to the opening gaps lower and early morning weakness.
I hope that helps to clarify the possible ambiguity.
The 4 Model Trades provided yesterday are all performing fairly well, at last check. NET, TXN, SJM, and STZ are all up on a so-so day with the S&P 500 up roughly 0.25%.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, September 19:
AZO
Tuesday, September 20:
None
Economic Reports
September housing market index: 46 (actual) vs. 48 (estimate)
Happy trading!
Tom