
EB Daily Market Report - Monday, October 3, 2022
My Schedule
I'm among the 17 technical analysts that StockCharts.com has invited to speak at ChartCon 2022. The event will be held on October 7th and 8th (this Friday and Saturday). I will be traveling to Redmond, WA on Thursday, October 6th and will not be returning until Tuesday, October 11th. Our schedule at EarningsBeats.com will obviously be significantly impacted. At this time, I'm expecting to do Trading Places LIVE on Wednesday morning, October 5th, but I will not likely do another show until Wednesday, October 12th. There will be no EB Digest articles on either Friday, October 7th or Monday, October 10th. I will not be writing a Daily Market Report from Thursday, October 6th through Tuesday, October 11th. John Hopkins, if available, may provide a quick update each of those days.
ChartCon is available to everyone, but there is a fee. For more information on speakers, agenda, and cost, you can CLICK HERE. I know there will be a significant savings for StockCharts.com members - as much as 67% off - so taking out at least a free 30-day trial subscription prior to signing up would make good financial sense, if you're not already a StockCharts.com subscriber.
Executive Market Summary
- Futures were higher overnight and our major indices gapped higher at the opening bell
- Bulls have remained in charge throughout today's session, led by energy (XLE, +5.89%); crude oil prices ($WTIC, +4.81%) have surged higher as well
- Most commodities are up significantly, including silver ($SILVER, +8.70%) and gold ($GOLD, +2.05%)
- The 10-year treasury yield ($TNX) is down 14 basis points to 3.67% and appears headed for a test of yield support near 3.50%
- Tesla (TSLA, -7.37%) is falling after reporting Q3 deliveries well below expectations; autos ($DJUSAU, -5.93) is today's weakest industry group
- Consumer stocks are lagging as both discretionary (XLY, -0.84%) and staples (XLP, -1.72%) struggle to keep pace with the major indices
- Semiconductors ($DJUSSC, +4.32%) is enjoying one of its best days of 2022 - see below
- Many energy names are leading the S&P 500, including Marathon Oil (MRO, +10.76%) and Devon Energy (DVN, +9.45%)
Market Outlook
Money has been rotating into small cap growth vs. small cap value ($DJUSGS:$DJUSVS) recently and it could be a signal that the big Wall Street firms are favoring small caps in general. After one look at the weekly chart of the S&P 600 Small Cap Index ($SML), I think I can understand why:
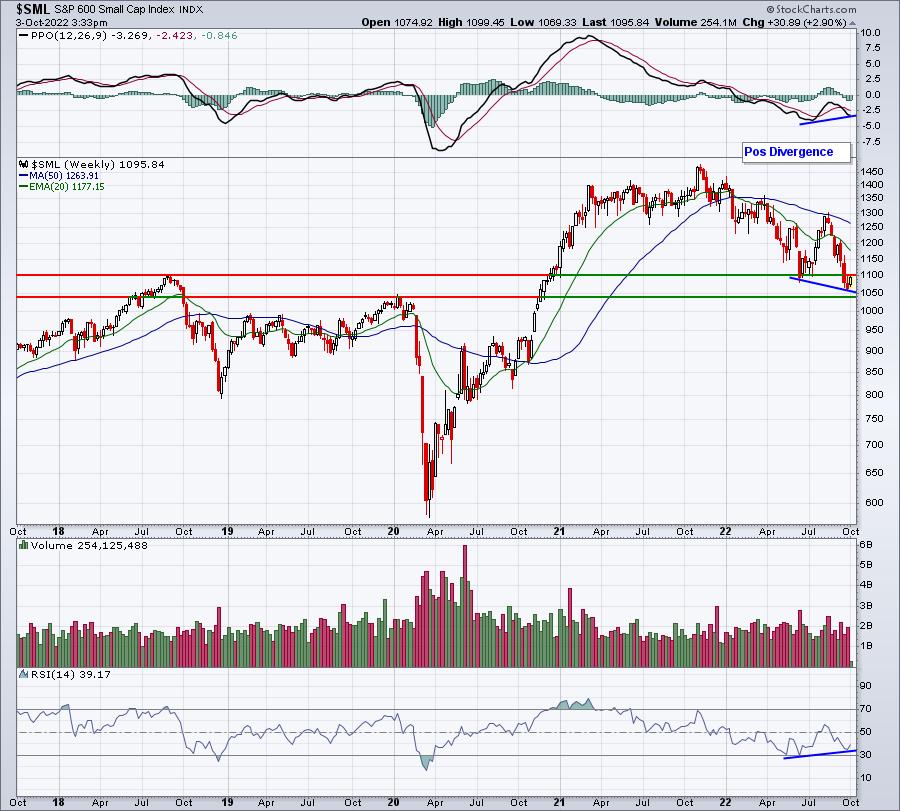
The positive divergence suggests that downside momentum is waning and the rotation that we've been seeing would seem to confirm this.
Sector/Industry Focus
Semiconductors ($DJUSSC) have been one missing ingredient in my bullish call for this summer. The group has continued to spiral lower and lower. It's way too early to suggest today's strength is the start of a massive rally. Instead, we should watch key long-term trendline support to the downside and short-term channel resistance to the upside:
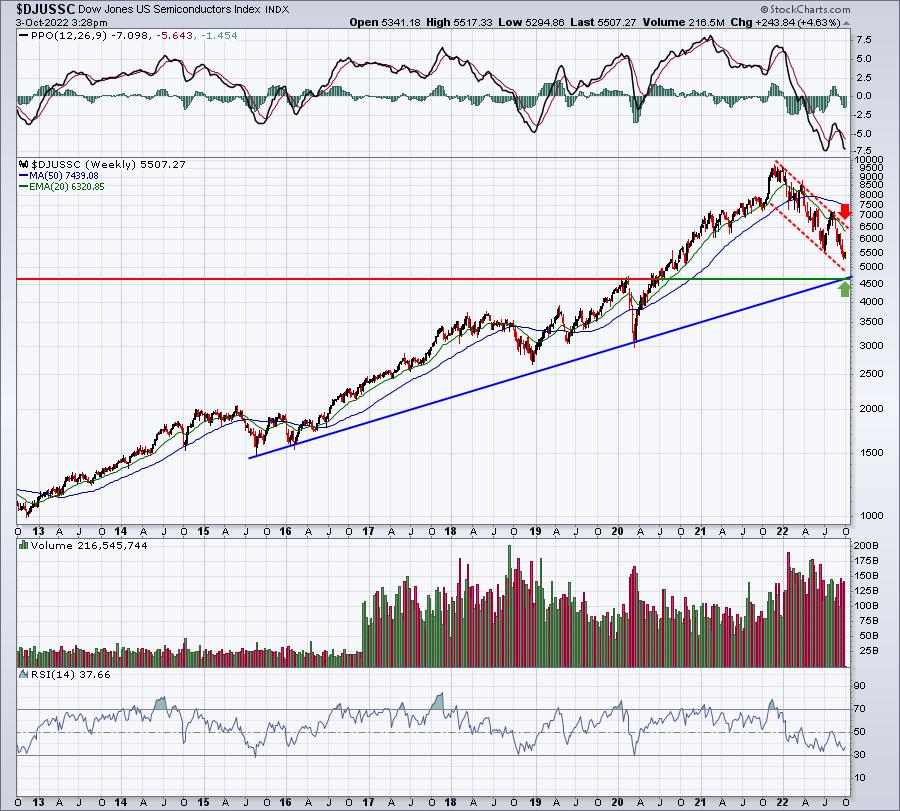
This is a very wide range from 4500-6500, but this is also an extremely volatile group. I'd have no problems buying or adding to this industry group for a year or two down the road, but you'd simply have to realize that an even better buying opportunity could be just around the corner.
ChartLists/Strategies
Here's an update of our Model Trades:
ENPH - it's making another move higher today, up 4.20% at last check. It's also testing its key 20-day EMA and 50-day SMA right now, so taking profits is an option if you're concerned about the overall market. Our target is at 297 and we'll keep it there for now, though I'm considering raising it. Our closing stop remains 268.
For now, we'll simply hold on to ENPH, but I'll be looking to add another Model Trade or two at some point later this week. I certainly don't want to chase a stock after a big move higher today.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, October 3:
None
Tuesday, October 4:
AYI, NG, SGH
Economic Reports
September PMI manufacturing: 52.0 (actual) vs. 51.8 (estimate)
September ISM manufacturing: 50.9 (actual) vs. 52.4 (estimate)
August construction spending: -0.7% (actual) vs. -0.1% (estimate)
Happy trading!
Tom