
EB Daily Market Report - Wednesday, October 5, 2022
My Schedule
I'm among the 17 technical analysts that StockCharts.com has invited to speak at ChartCon 2022. The event will be held on October 7th and 8th (this Friday and Saturday). I will be traveling to Redmond, WA on Thursday, October 6th and will not be returning until Tuesday, October 11th. Our schedule at EarningsBeats.com will obviously be significantly impacted. At this time, I'm expecting to do Trading Places LIVE on Wednesday morning, October 5th, but I will not likely do another show until Wednesday, October 12th. There will be no EB Digest articles on either Friday, October 7th or Monday, October 10th. I will not be writing a Daily Market Report from Thursday, October 6th through Tuesday, October 11th. John Hopkins, if available, may provide a quick update each of those days.
ChartCon 2022 - LAST CHANCE!
ChartCon is available to everyone, but there is a fee. For more information on speakers, agenda, and cost, you can CLICK HERE. I know there will be a significant savings for StockCharts.com members - as much as 67% off - so taking out at least a free 30-day trial subscription prior to signing up would make good financial sense, if you're not already a StockCharts.com subscriber.
I will be speaking at 4:25pm ET on Friday in a Market Outlook panel with David Keller, Mary Ellen McGonagle, and Leslie Jouflas. On Saturday, I will join the Bulls vs. Bear Debate, which begins at 2:00pm ET. I hope you'll join me! The event will be quite interactive, so I'd love to hear from you!!!
Executive Market Summary
- Futures were weak overnight and it certainly appeared we were poised to give back gains from the past two sessions
- But the bulls have battled back and our major indices have just turned green
- Energy (XLE, +2.58%) is having another strong session; health care (XLV, +0.72%) and technology (XLK, +0.71%) are strong performers as well
- OPEC agreed to cut oil production by 2 million barrels per day, adding to strength in energy
- Crude oil ($WTIC, +1.44%) is jumping in sympathy
- Two defensive sectors - utilities (XLU, -1.67%) and real estate (XLRE, -1.40%) - are lagging badly
- Nike (NKE, +3.20%) is leading the Dow Jones, while the S&P 500 is seeing strength from Schlumberger (SLB, +6.42%)
Market Outlook
I know many folks are worried about interest rates pushing higher and higher. But many of the relative charts that I follow simply don't agree. If rates are expected to move higher, there is NO reason to want to own small cap growth stocks ($DJUSGS) over small cap value stocks ($DJUSVS). None. Zero. Yet, since the May low, subsequent lows in June and September on the S&P 500 have been accompanied by money rotating into small cap growth. Here's the visual:
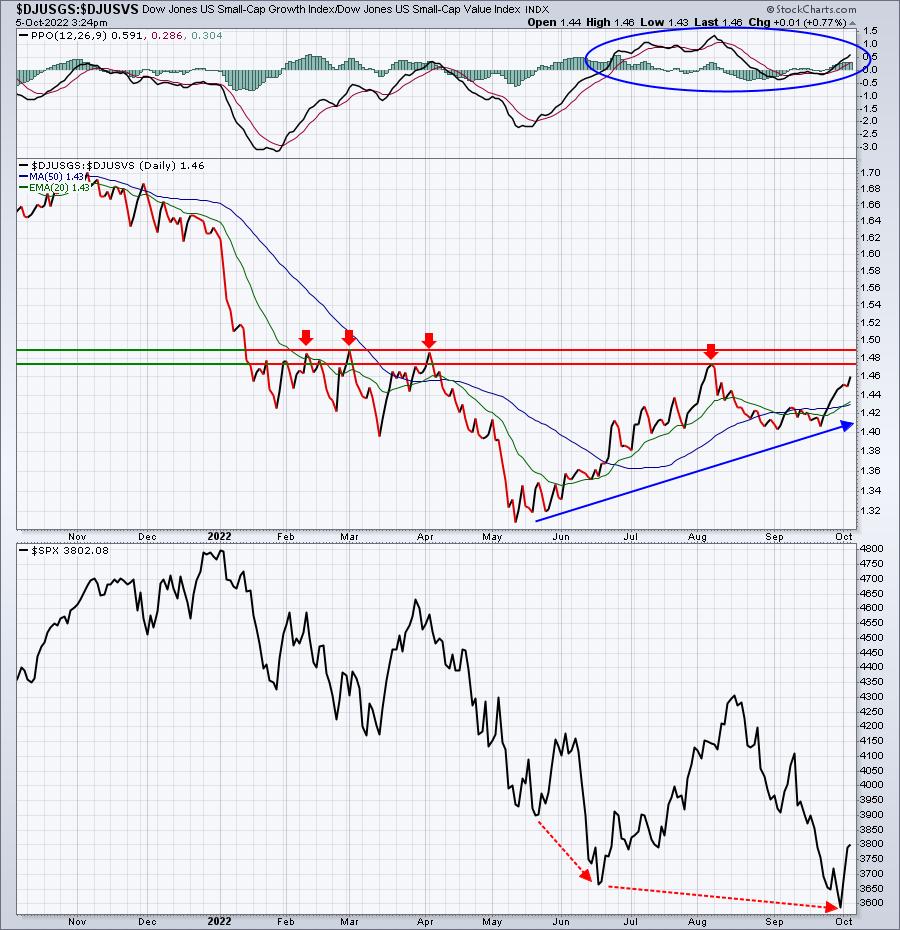
The PPO remaining mostly above the zero line and now turning up again really underscores the bullish momentum of small cap growth vs. small cap value. Yes, the S&P 500 price action turned bearish in September, setting a new low, but rotation isn't supporting the bearish argument. Remember, it was just 9 months ago that the exact opposite was occurring. The S&P 500 was setting an all-time high, but money was rotating much more defensively to value-oriented stocks. We know how that turned out, don't we?
Sector/Industry Focus
I've spoken about financials quite a bit lately as this sector enjoys much historical strength through November. Industrials (XLI) are similar in that regard. Transportation stocks ($TRAN) have begun to strengthen and, if that continues, it would be EXTREMELY bullish for the S&P 500. Here's the latest chart, where the TRAN is looking to clear its 20-day EMA and significant price resistance in the 12900-13100 zone:
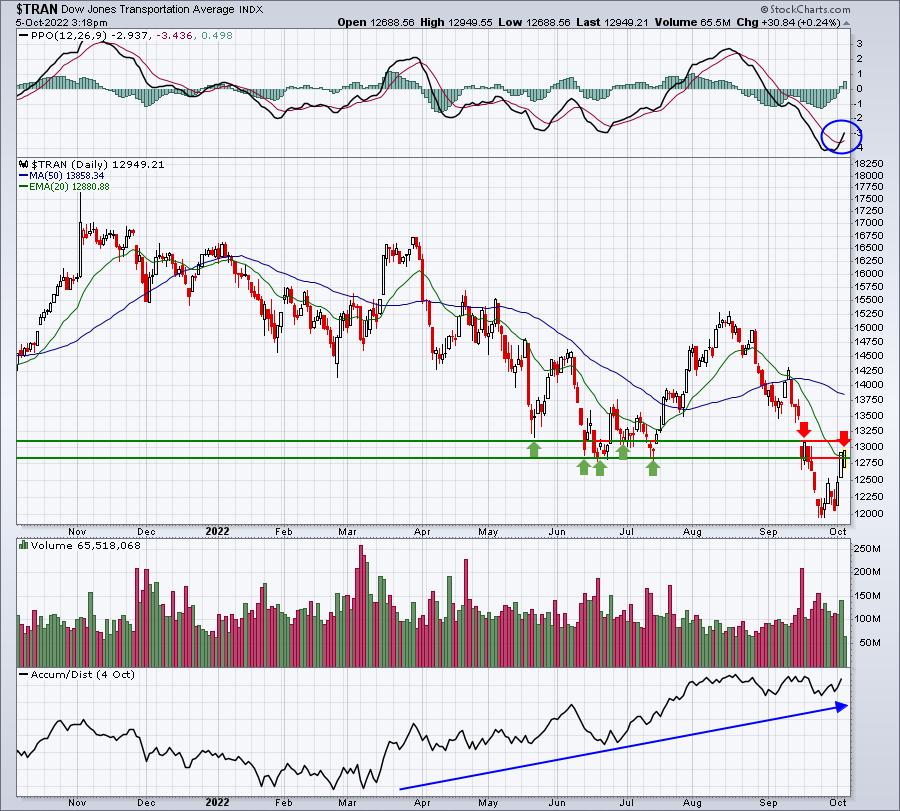
The AD line is on the verge of setting a new 52-week high and price action is attempting to clear a major area of resistance. This combination is quite bullish and adds to my call of a market bottom. Keep a close eye on transports as they are the most closely related group to our economy.
ChartLists/Strategies
Here's an update of our last remaining Model Trade:
CDNS - we added CDNS yesterday at 171.64 with a second entry at 167.97, which triggered this morning when CDNS hit an intraday low of 167.72. It's since rebounded and traded at 170.29 - at last check.
Because of my schedule traveling out to Seattle to participate in ChartCon 2022, I don't have any further Model Trades and we'll likely just ride with CDNS for now. Should our major indices break above the 20-day EMA on a closing basis, I will grow much more bullish - so long as that moving average then holds as support on future pullbacks. As always, I'd focus on LEADING stocks as money will likely return to those stocks much quicker than others.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, October 5:
LW, RPM, HELE
Thursday, October 6:
STZ, MKC, CAG, LEVI, ACCD
Economic Reports
September ADP employment report: 208,000 (actual) vs. 200,000 (estimate)
September PMI composite: 49.5 (actual) - no estimate provided
September ISM services index: 56.7 (actual) vs. 56.0 (estimate)
Happy trading!
Tom