
EB Daily Market Report - Wednesday, October 19, 2022
Model ETF Portfolio DRAFT
Well, another 3 months have passed and it's time for our latest Model ETF Portfolio Draft, which will occur at 5:30pm ET today. I'll be looking at the market environment and current themes to take into consideration in filling out our ETF portfolio for the next 90 days. It should be another great educational event, including a description of our ETF Analyzer tool that helps us understand WHAT WE OWN. And when putting together a portfolio of ETF's, that's a very important and overlooked component of ETF portfolio management. Be sure you understand what you own.
We'll record today's event and that recording will be available for your review either later this evening or tomorrow. Hope to see you there!
Executive Market Summary
- Futures were strong last night after a strong quarterly report by Netflix (NFLX), but turned negative overnight as the 10-year treasury yield ($TNX) spiked yet again
- Today marks the 35th anniversary of Black Monday, October 19th, 1987, the day the Dow Jones dropped 22%
- Building permits were reported stronger-than-expected this morning, though housing starts were weak
- Interest rates (think TNX) will be in the spotlight after 2pm ET as the beige book is released; the initial 15-minute response has been muted, but we've seen a slight uptick in stocks
- Today's action has been quite choppy with a fairly narrow trading range, at least vs. what we've seen the past several days
- Commodities are mixed with crude oil ($WTIC, +4.04%) back above $86 per barrel; natural gas ($NATGAS, -4.09%) is challenging major price support in the 5.40-5.50 range
- Energy (XLE, +3.18%) is easily the best-performing sector, while real estate (XLRE, -2.17%) returns to being a significant underperformer after a respite and test of its declining 20-day EMA
- Netflix (NFLX, +12.86%) posted much better-than-expected quarterly results and is the S&P 500's best performer; Intuitive Surgical (ISRG, +9.47%) also beat expectations and is seeing a similar reaction
- Meanwhile, Generac Holdings (GNRC, -24.66%) missed estimates, said sales have slowed and INVENTORY IS PILING UP (remember this, because I believe high inventories will ultimately prove to be a deflationary threat, triggered much lower interest rates ahead)
Market Outlook
I feel like the excellent Netflix (NFLX) report and options expiration are trying to carry the market higher, while the rapidly-advancing TNX is squashing every effort. There is financial incentive for market makers to carry prices higher into the end of the week, but outside of early gaps higher, there really hasn't been much buying throughout the day. That reeks of manipulation, suggesting that we could be in for another move lower in the near-term. I believe that depends on the direction of interest rates. But if advancing rates continue to pressure equities, it seems like it's only a matter of time before stock traders buckle.
The NASDAQ 100 had a chance to bust through a key short-term down channel and it's failed - again:
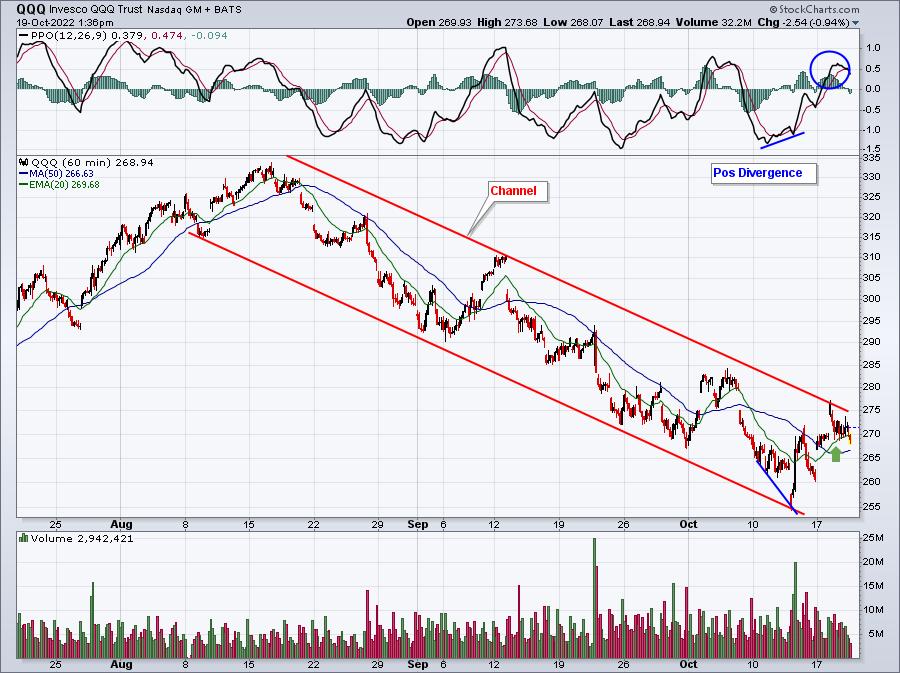
This is the same chart that I showed yesterday. The bulls failed to clear key resistance and now the bears are attempting to take out 20-hour EMA support. In a downtrend, we should expect the bears to prevail - until they don't. Because I remain very bullish longer-term, I'm looking for short-term triggers to ignite the stock market higher. The most obvious trigger would be a sudden reversal and subsequent downtrend in the TNX. Bond traders are usually the smartest traders, so we should all be on the lookout for a topping signal, like a reversing daily, and especially weekly, candle.
Sector/Industry Focus
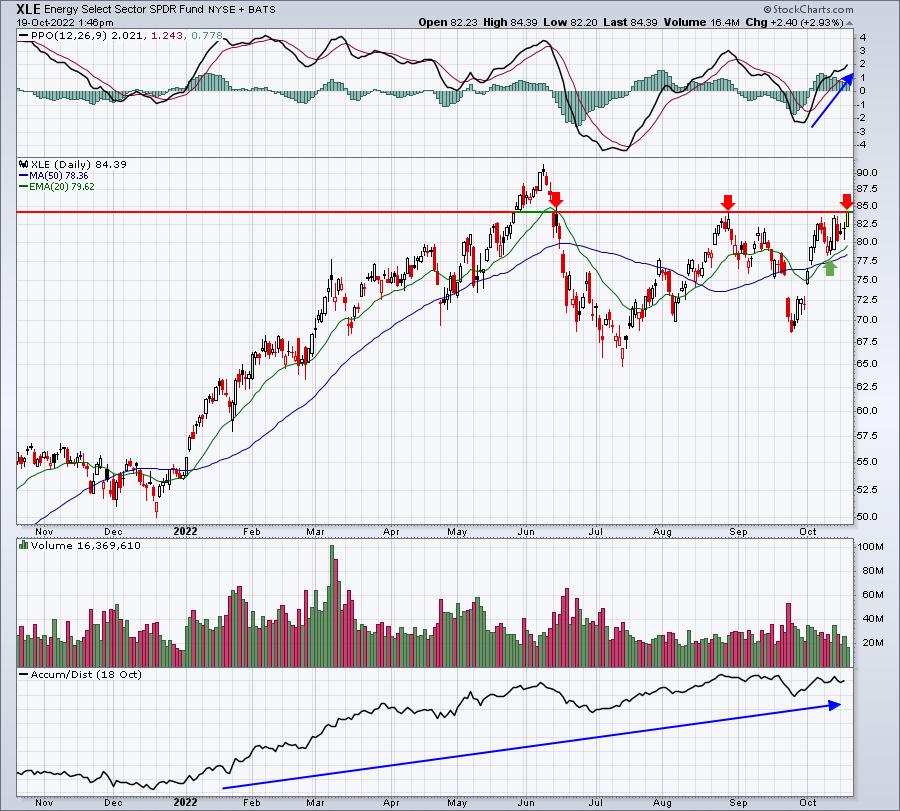
Energy (XLE) was shown yesterday on its hourly chart. Recently lows near 78.50 were highlighted as support, with the odds favoring the energy bulls that this support would hold. If we look at the daily chart on the XLE, the short-term momentum clearly remains with the bulls, even though the XLE had underperformed the S&P 500 badly over the past 2-3 days:
ChartLists/Strategies
In addition to the dozens and dozens of stocks included in the Max Pain spreadsheet sent out over the weekend, I provided two additional stocks - Snap, Inc. (SNAP) and NIO Inc. (NIO) - last night during our event. The latter was provided as a Model Trade candidate, looking to capitalize on any short-term strength into options expiration Friday. That backfired today when many of the smaller auto companies like NIO, Workhorse Group (WKHS), and Nikola Corp (NKLA) all sold off from the opening bell. Our intraday stop was set at 11.60, to help mitigate any severe downside risk, and that triggered very early this morning. At last check, NIO traded at 10.80, so while the loss was painful, it was a reminder why we keep stops in place. I would expect NIO to rebound into the end of the week and early next week based on its outstanding options, but volume is very heavy today. Market makers do have limited capital, though, making a heavy volume selling day difficult to reverse.
After the recent string of whipsaw action and losing trades, we'll hold off a bit before taking other positions.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, October 19:
TSLA, PG, ABT, ASML, ELV, IBM, PLD, CCI, LRCX, TRV, KMI, MTB, LVS, NDAQ, PPG, BKR, EFX, CFG, NTRS, STLD, CMA, ALLY, REXR, MKTX, KNX, AA, SEIC, FR, LAD, LSTR, RLI, UMPQ, CVBF, TCBI, UNF, PACW, CNS, BMI, LBRT, SLG, WDFC, WGO, KALU, HCSG
Thursday, October 20:
DHR, PM, UNP, T, MMC, BX, CSX, ABB, FCX, DOW, NUE, NOK, FITB, TSCO, GPC, ERIC, SIVB, SNAP, DOV, KEY, DGX, POOL, SNA, EWBC, WSO, RHI, WBS, AAL, WHR, WAL, IRDM, SNV, THC, OZK, ALK, MSM, MAN, BKU, HTH
Economic Reports
September housing starts: 1,439,000 (actual) vs. 1,475,000 (estimate)
September building permits: 1,564,000 (actual) vs. 1,550,000 (estimate)
Beige book released at 2:00pm ET
Happy trading!
Tom