
EB Daily Market Report - Thursday, October 20, 2022
Executive Market Summary
- Futures were mixed overnight and prices opened this morning in similar fashion
- After 30-45 minutes of equity strength after the opening bell, treasury yields again rose rapidly and crushed that early rally - more on this below
- Cryptocurrencies are mostly lower as bitcoin ($BTCUSD, -0.93%) challenges 19000
- Commodities are once again mixed as crude oil ($WTIC, +0.82%) rises, while natural gas ($NATGAS, -1.92%) tumbles further
- The 10-year treasury yield ($TNX) is up another 9 basis points to 4.22% after initial jobless claims were reported much lower than expected
- Higher interest rates are not good for aggressive sectors that rely on future earnings growth to drive rising PEs
- Utilities (XLU, -2.85%) and consumer discretionary (XLY, -2.06%) lead U.S. stocks lower today
- Communication services (XLC, +0.04%) was the only sector higher just before 2:30pm ET
- Tesla (TSLA, -7.51%) weighed on consumer discretionary stocks after reporting quarterly revenues below expectations
Market Outlook
The bond market remains a big hurdle for U.S. equities. Every rally attempt seems to be thwarted by yet another spike in the 10-year treasury yield ($TNX). Today's morning rally in the QQQ ended abruptly, just as soon as the TNX started its day-long uptrend:
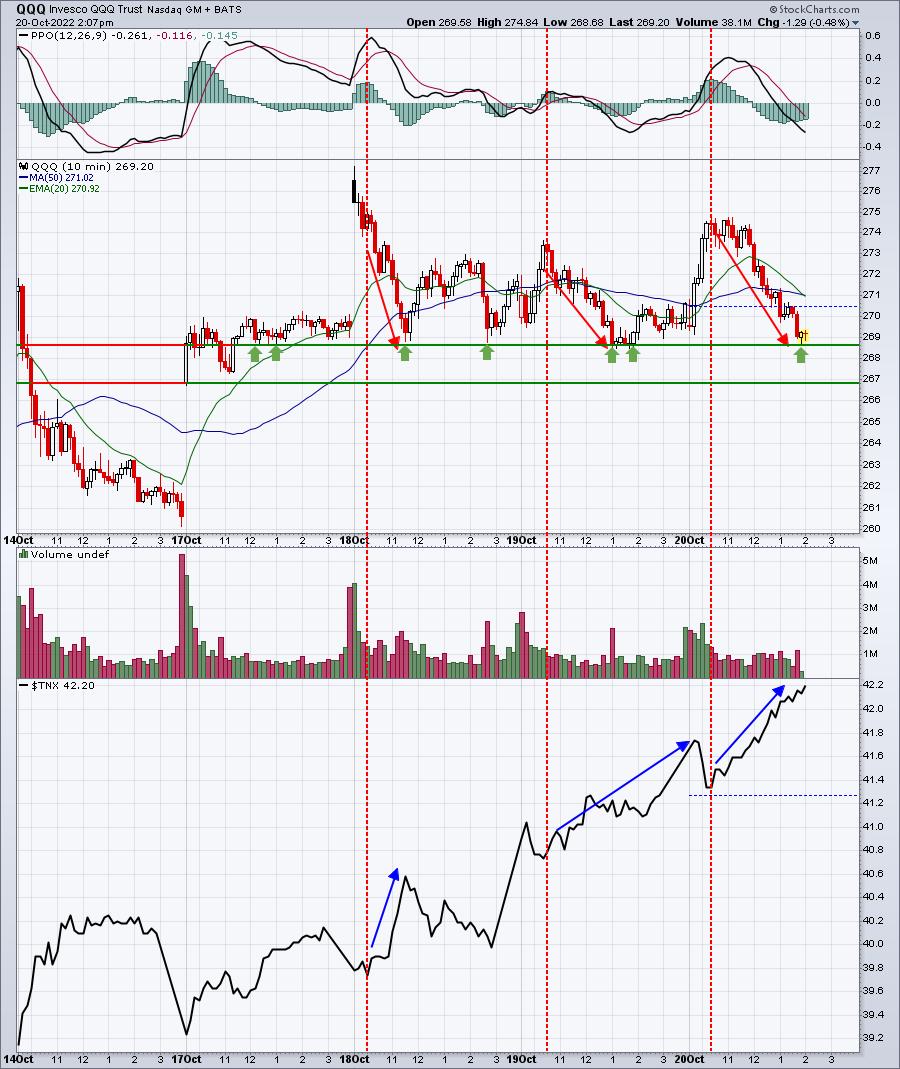
Morning strength in the QQQ has now fallen apart later in the session 3 consecutive days. If you follow my work, you know that I care more about afternoon performance than morning performance. Short-term, this is not likely to bode well. It's also important to understand that U.S. stocks are facing their worst weekly historical period of the year next week. The S&P 500 has produced annualized returns of -42.81% from the close on October 21st (Friday) through the close on October 27th since 1950. The NASDAQ has produced annualized returns of -63.54% during this upcoming week since 1971. It doesn't always go lower, but the odds certainly favor the bears.
Sector/Industry Focus
Technology (XLK), the most influential sector, attempted to break above its 20-day EMA this morning and has failed resoundingly:
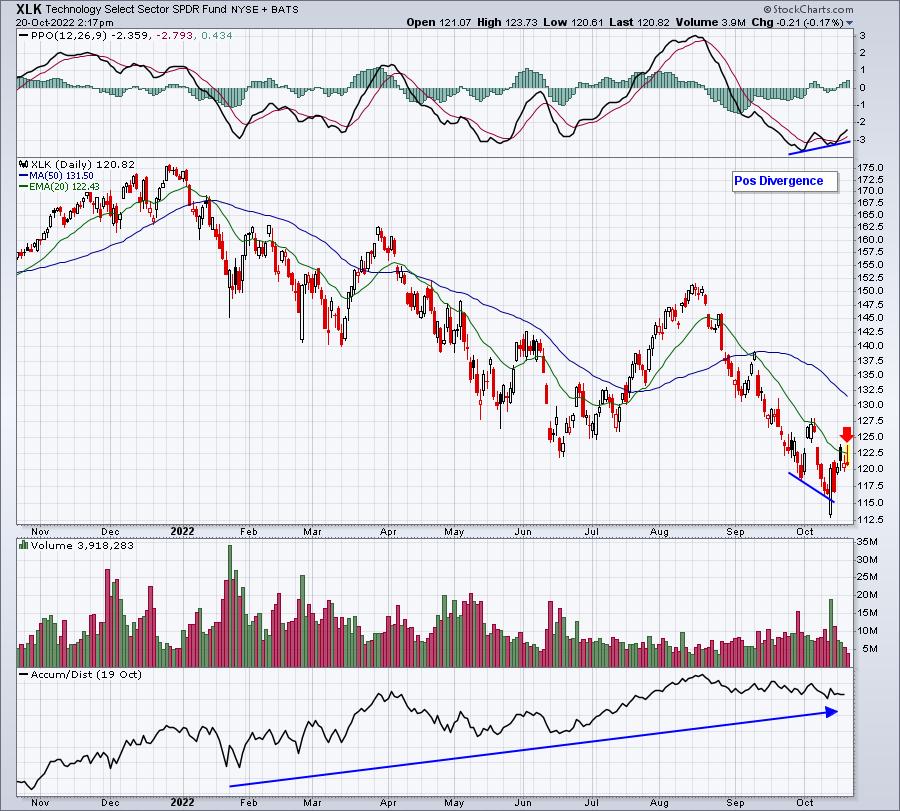
This is not helping the market and the constant failure at the 20-day EMA likely relates to the rapidly-rising TNX. I do like the positive divergence and the strong AD line, but we need price action to confirm these secondary indicators. We're not there yet.
ChartLists/Strategies
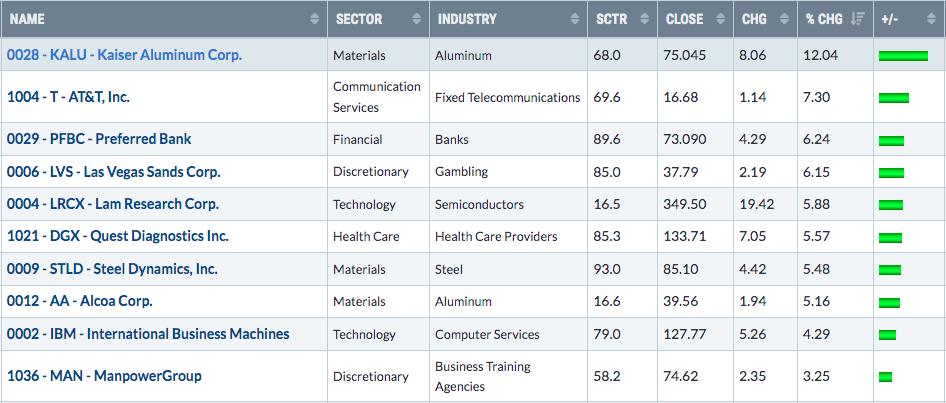
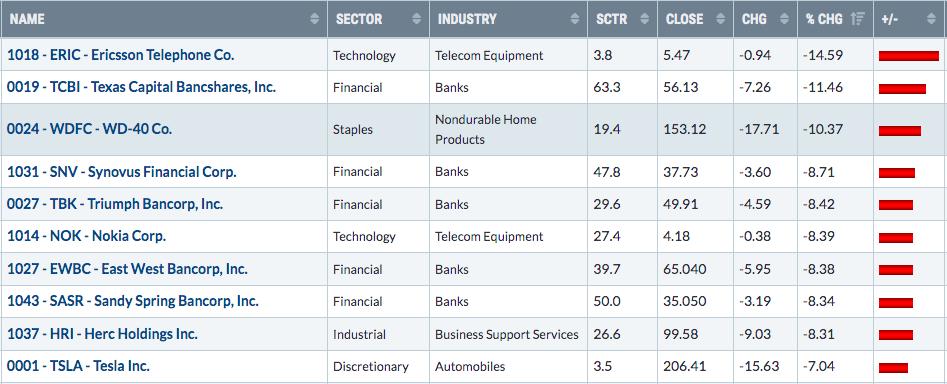
Don't forget that we have those Upcoming Earnings ChartLists for every day during earnings season. Here's today's ChartList, first featuring the best reactions from earnings out since yesterday's close, followed by the worst reactions:
Best Earnings Reactions:
Worst Earnings Reactions:
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, October 20:
DHR, PM, UNP, T, MMC, BX, CSX, ABB, FCX, DOW, NUE, NOK, FITB, TSCO, GPC, ERIC, SIVB, SNAP, DOV, KEY, DGX, POOL, SNA, EWBC, WSO, RHI, WBS, AAL, WHR, WAL, IRDM, SNV, THC, OZK, ALK, MSM, MAN, BKU, HTH
Friday, October 21:
VZ, AXP, SLB, HCA, HBAN, RF, IPG, ALV, EEFT, SMPL, SXT
Economic Reports
Initial jobless claims: 214,000 (actual) vs. 235,000 (estimate)
October Philadelphia Fed Manufacturing Index: -8.7 (actual) vs. -5.0 (estimate)
September existing home sales: 4,710,000 (actual) vs. 4,695,000 (estimate)
September leading indicators: -0.4% (actual) vs. -0.3% (estimate)
Happy trading!
Tom