
EB Daily Market Report - Monday, November 7, 2022
Sneak Preview - Top 10 Stocks
This afternoon, I'll be hosting our latest Sneak Preview of our Portfolio Draft, highlighting the key themes that I'll be looking at as we approach the date in which we'll switch out our Portfolio Stocks - November 19th. I'll also look into some of the better earnings reports and reactions that we've seen this quarter, discussing several stocks that may be Portfolio Stocks for next quarter. The webinar will be begin at 4:30pm ET and instructions for the event were sent out this morning. I hope to see you there!
Executive Market Summary
- Futures were up overnight, though there was a bit of relative weakness in NASDAQ futures - again
- Gold ($GOLD, +0.11%) has struggled to follow through on Friday's significant gains, despite a further drop in the U.S. Dollar (UUP, -0.65%)
- Other commodities are mixed as natural gas ($NATGAS, +8.08%) surges; crude oil ($WTIC, -0.68%), however, trades slightly lower to $92 per barrel
- 9 of 11 sectors trade higher, with communication services (XLC, +1.79%) and technology (XLK, +1.77%) leading the advance
- Utilities (XLU, -1.67%) is the primary laggard today, though consumer discretionary (XLY, -0.41%) is weak; Tesla (TSLA, -4.19%) is threatening to close beneath $200 for the first time since June 2021
- The 10-year treasury yield ($TNX) is up 6 basis points to 4.22%, though there's been no economic news of significance today
- Two utilities - Nisource (NI, -6.86%) and Dominion Energy (D, -6.03%) - are the worst S&P 500 performers on the session
Market Outlook
This Thursday, we'll get the October CPI report. This calculation takes the last 12 CPI readings and adds them to together to come up with the annual rate. Here's a chart showing the monthly moves with the bottom panel highlighting the 12-month rate of change (ROC):
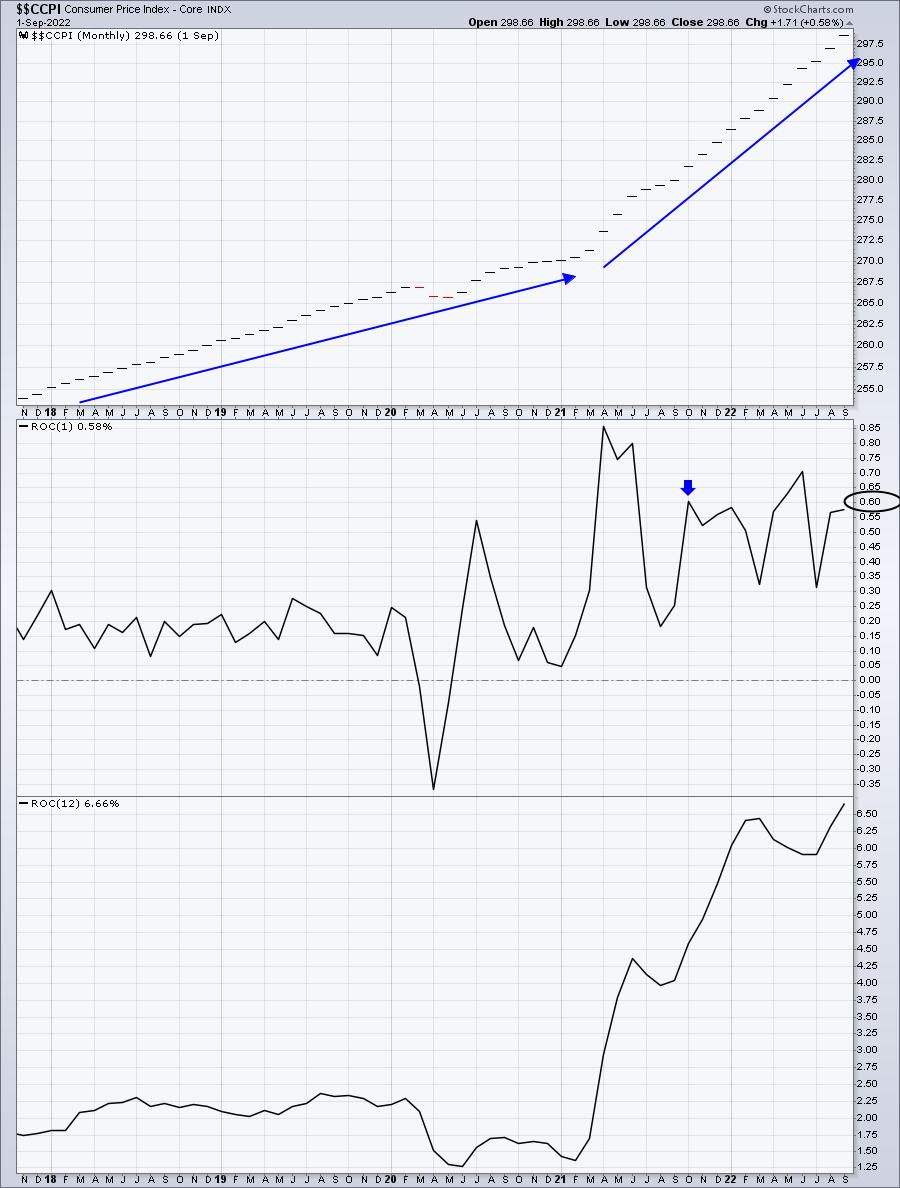
You can see the dramatic rise in the monthly Core CPI in the top portion of the chart. The middle panel highlights the 1-month rate of change and the blue arrow highlights the October 2021 reading of 0.60, which is what will be replaced. The October 2022 "expectation" is that Core CPI will increase 0.5%. If it meets the estimate, then the annualized rate of inflation will actually drop by one-tenth of one percent. The last two CPI reports have resulted in large gaps lower, so if the news is bad on Thursday, don't be shocked by another gap lower. But it'll be more important to watch the rest of the day's action, not just the opening reaction.
Sector/Industry Focus
In my last Daily Market Report (DMR), I looked at financials (XLF) and materials (XLB) as both were fighting key trendline price resistance issues. Today, we'll take a quick glance at technology (XLK) and consumer discretionary (XLY) - the two most important sectors, in my opinion:
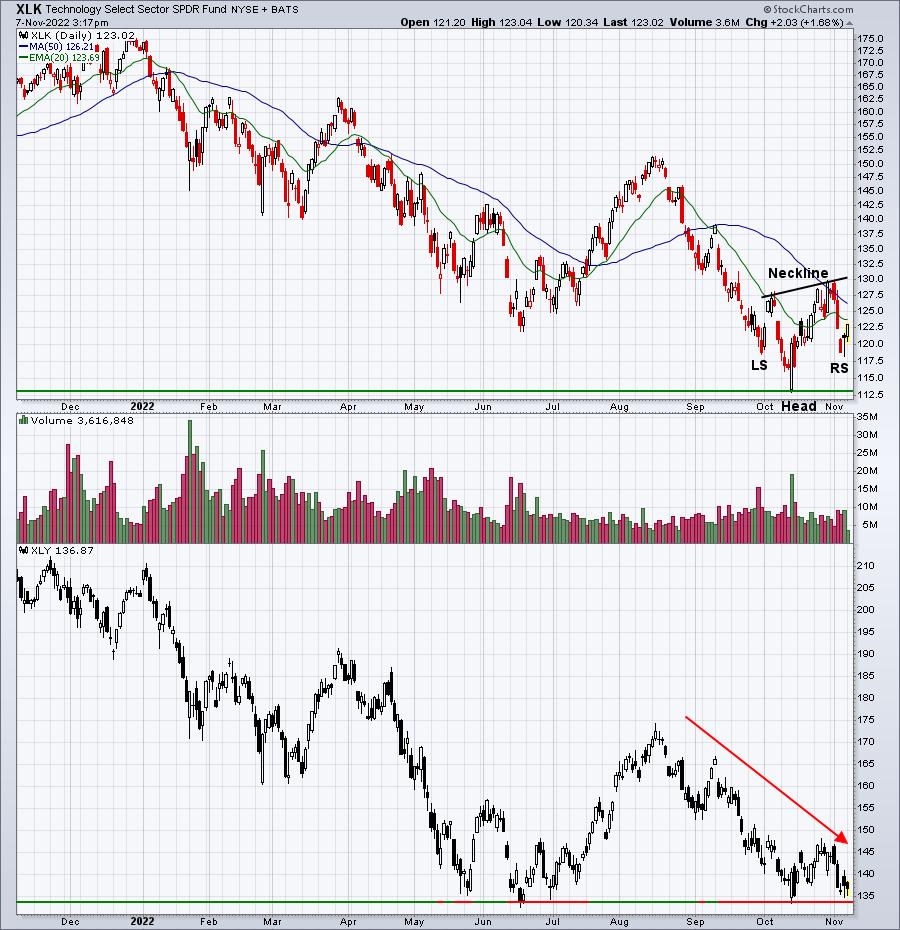
First, it's important to note that the XLB has broken its downtrend line and the XLF is literally sitting on its downtrend line as I write this. As for the XLK and XLY, the XLK appears to be in a funky bottoming reverse head & shoulders pattern, though it would take a close above 130-132 to confirm it. Meanwhile, the key on the XLY appears to be holding support at 134. These two sectors MUST begin showing more absolute and relative strength in order for the S&P 500 to enjoy a sustainable rally.
We're not quite there yet.
ChartLists/Strategies
I'm planning to wait until we see our major indices strengthen and trade above their rising 20-day EMAs. That means patience will be required. If I were to trade at all, it'd likely be leading stocks in leading industry groups that sell off after they report solid results.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, November 7:
ATVI, BNTX, FANG, WELL, IFF, FNV, TTM, MOS, PLTR, RYAAY, DINO, LNT, TTWO, SEDG, VTRS, WTRG, NI, NRG, SWAV, QGEN, CHH, RBA, FSK, LYFT, AMG, FN, HAE, CBT, FIVN, FOUR, ICUI, SANM, TRIP, TDC, DOCN, THS, DK, MWA, TASK, BLDP, QTWO, SAVA, CRON, FLGT, LGND, DO
Tuesday, November 8:
DIS, OXY, CEG, DD, GFS, ALC, RPRX, LCID, EC, CNHI, PKI, EXPD, AKAM, JKHY, DAR, NLOK, NFE, XP, FNF, DOX, AXON, CG, NWS, BLDR, PLUG, WYNN, NCLH, NXST, MASI, HALO, REYN, PLNT, COTY, PRGO, LITE, AFRM, NTRA, DV, IGT, NEWR, ZD, YPF, SPWR, GO, SFM, AMC, ALRM, NOG, ARRY, ROG, CRCT, CARG, HAIN, UPST, NVAX, VRTV, LMND, SILK, OPK, MODN, EVBG, WTI, RAMP, DDD, AVID, ANGI
Economic Reports
None
Happy trading!
Tom