
EB Daily Market Report - Thursday, December 1, 2022
Executive Market Summary
- Futures were higher overnight and we gapped up at the opening bell
- Sellers quickly jumped in, however, and the bulls have been trying to battle back all day
- The 10-year treasury yield ($TNX) has fallen 18 basis points to 3.53%; the TNX should find key support in the 3.48%-3.50% range
- Commodities are jumping, especially gold ($GOLD), which has spiked more than 3% on the session, back above $1800 per ounce; this would be $GOLD's first close above $1800 since August
- Sectors are mixed with 6 higher and 5 lower
- Communications services (XLC, +0.60%) is today's best sector, while financials (XLK, -0.51%) see a bit of profit taking
- Salesforce.com (CRM, -8.22%) is reeling after its quarterly report; CRM is contributing to significant underperformance today by the Dow Jones
- Netflix (NFLX, +4.25%) is having another very solid day, helping to lift internet stocks ($DJUSNS, +0.83%)
Market Outlook
Yesterday, we confirmed many key breakouts and today has been mostly about holding onto those gains. Here's a quick look at the S&P 500:
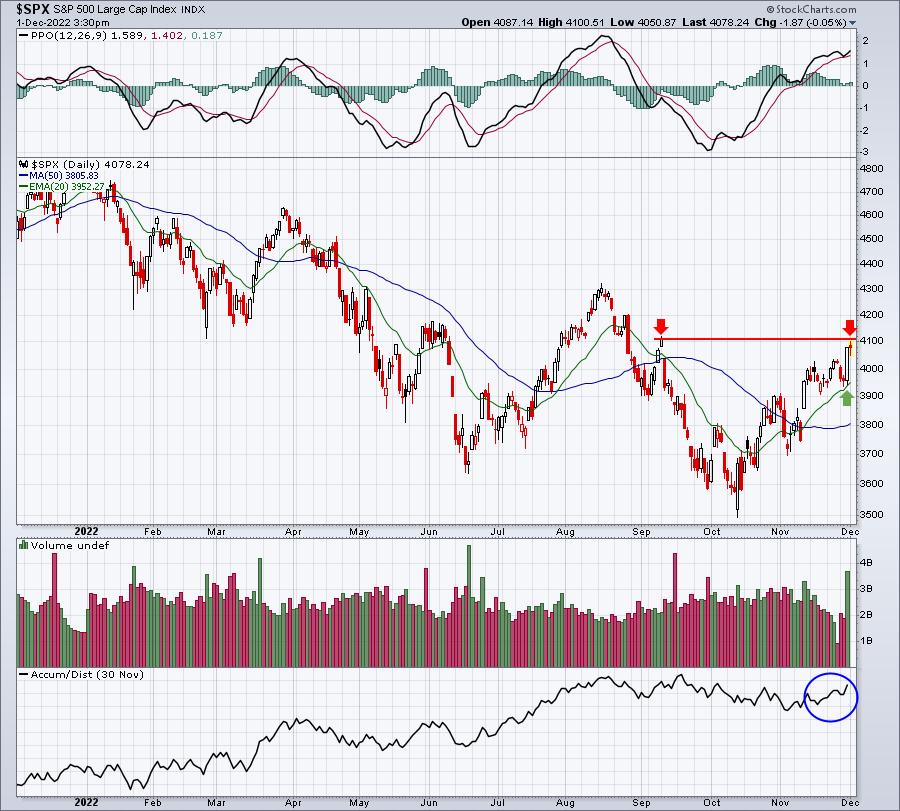
As the stock market recovers, there'll be one key level after another that we'll need to negotiate. The bounce yesterday off the rising 20-day EMA was perfect, but next up will be gap resistance at 4110. Today's high at 4100 nearly got there.
Sector/Industry Focus
Clothing & accessories ($DJUSCF) is attempting a nice breakout of its own:
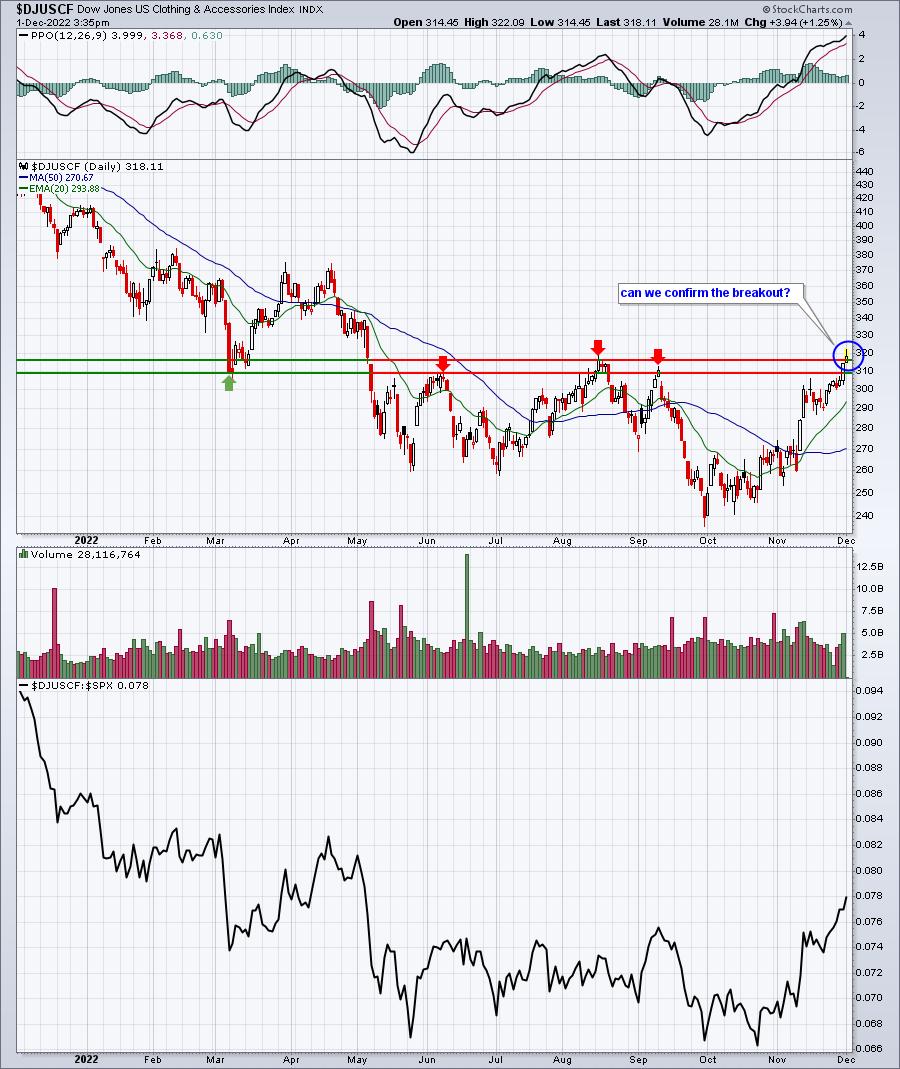
Relative strength in the DJUSCF is already nice. An absolute price breakout would add to it. That would make stocks like Lululemon Athletica (LULU) even more attractive, because it'll confirm that money is rotating into this space.
ChartLists/Strategies
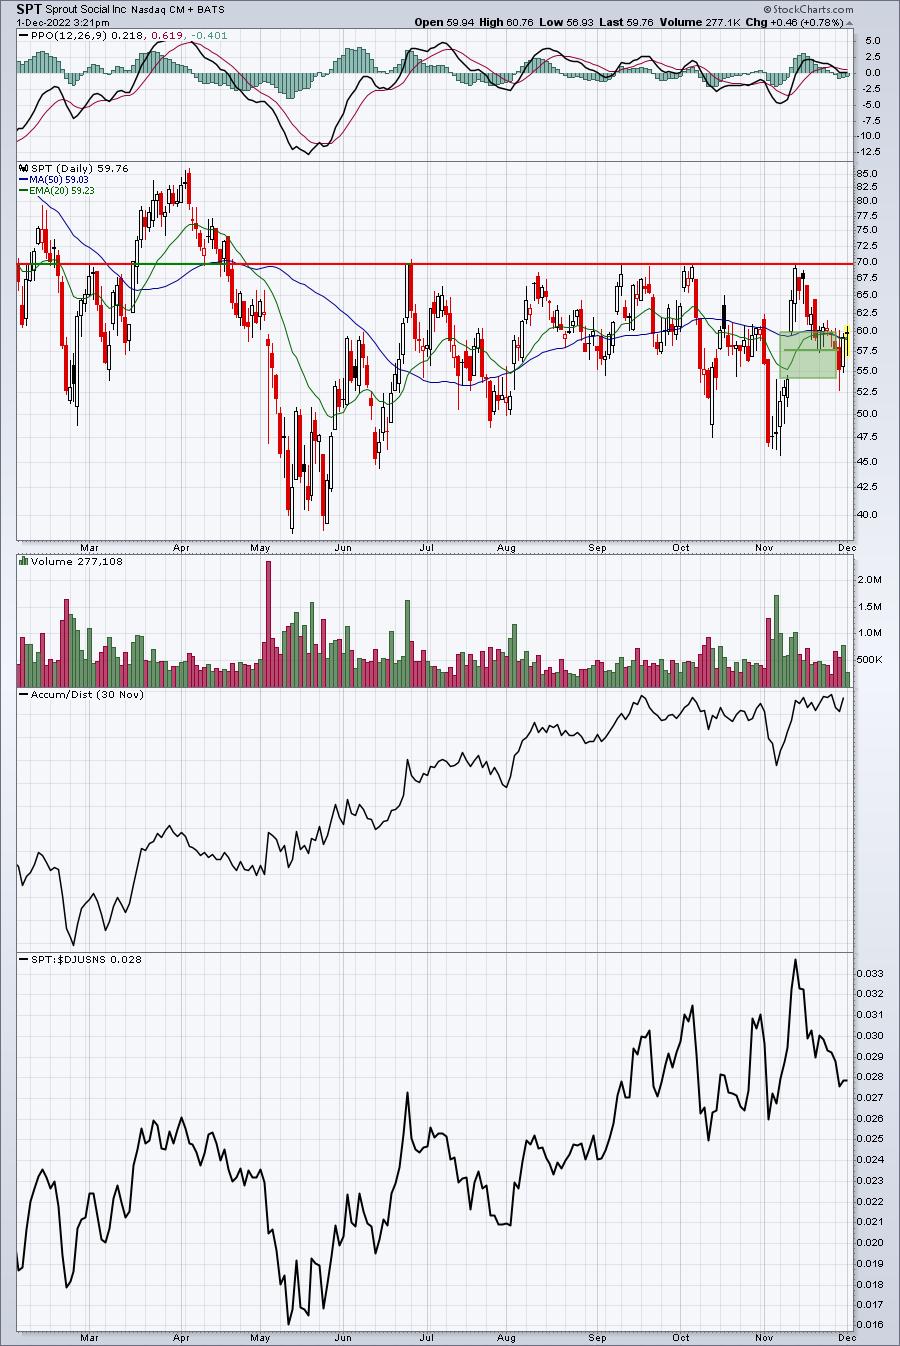
Here were the last two possible trades that I discussed off of earnings-related gap support:
SPT (from Saturday's Weekly Portfolio Report):
TASK (from yesterday's DMR):
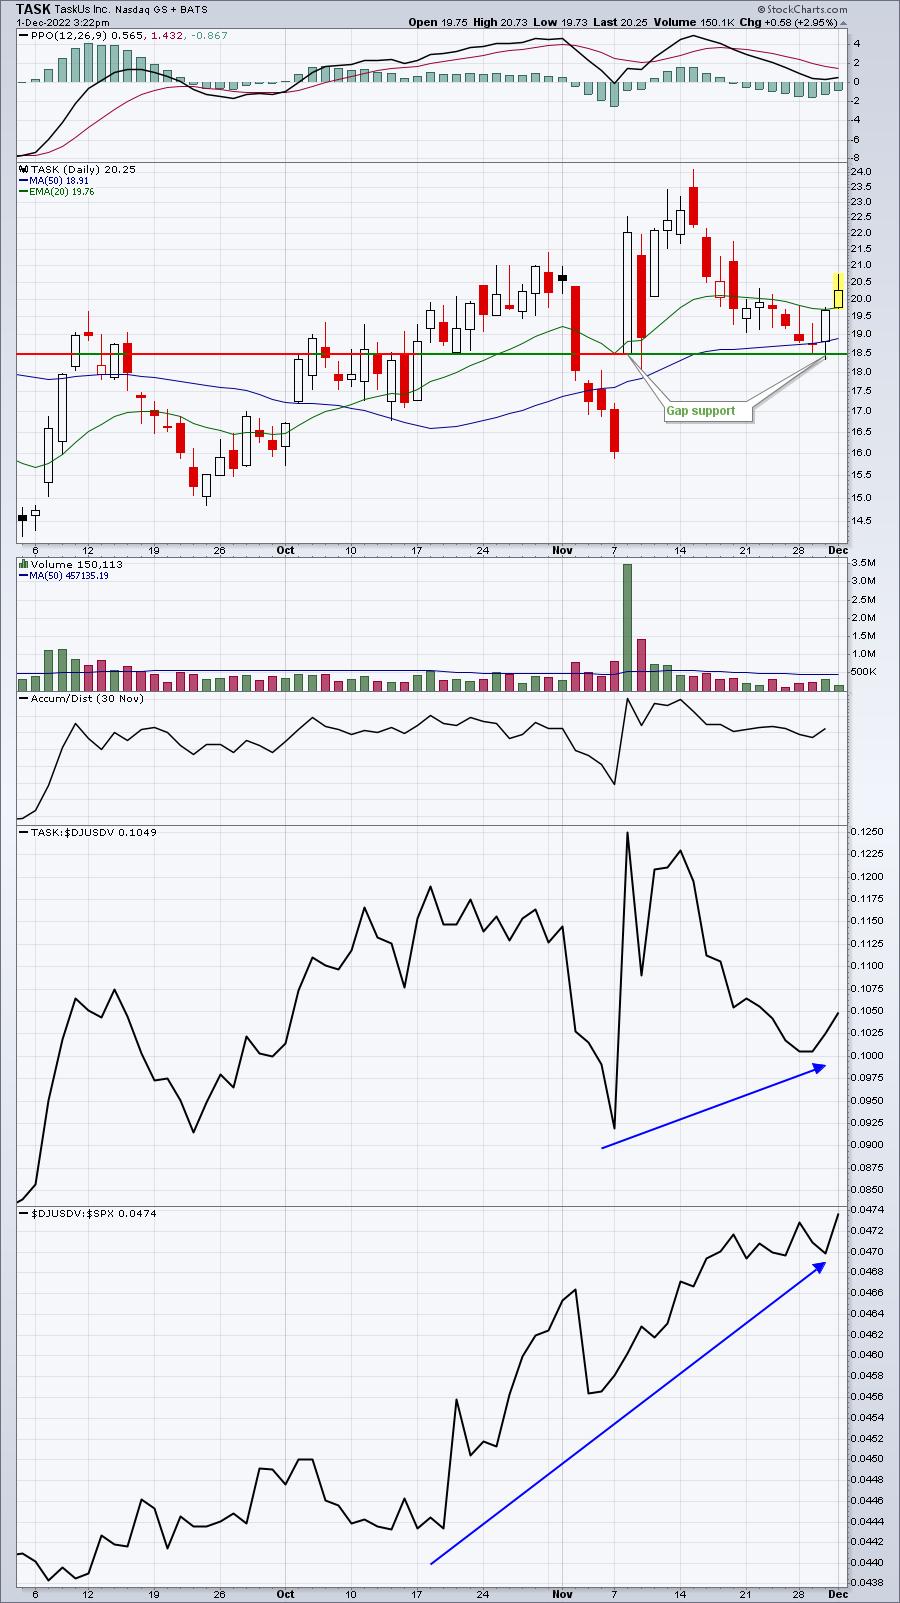
Now you know why I like this strategy. Clearly, having a very solid and rapidly-rising market doesn't hurt, but I've found in my trading years that this is one of the most reliable trade setups - at least for me. And when stocks rise this quickly, I take the money and run. If they keep going higher, great. I want my money and I return to cash. At that point, the risk is GONE. I've sold SPT and TASK. I sold NFLX yesterday and way too early, but I don't care. We might be in a different market environment soon - one where I'll be more willing to swing trade and hold for a few weeks. But with the VIX still around 20, now is not that time. I get my money and EXIT STAGE LEFT.
Today, I took a shot with Dollar General (DG). DG reported a miss in earnings (though revenues did beat estimates), but I simply liked the fact that DG opened ABOVE key price support, then traded beneath it. I bought this morning, hoping to see a strong recovery and support held. I took small profits a few mins ago, because I didn't want to hold it overnight. But here's the look of the chart:
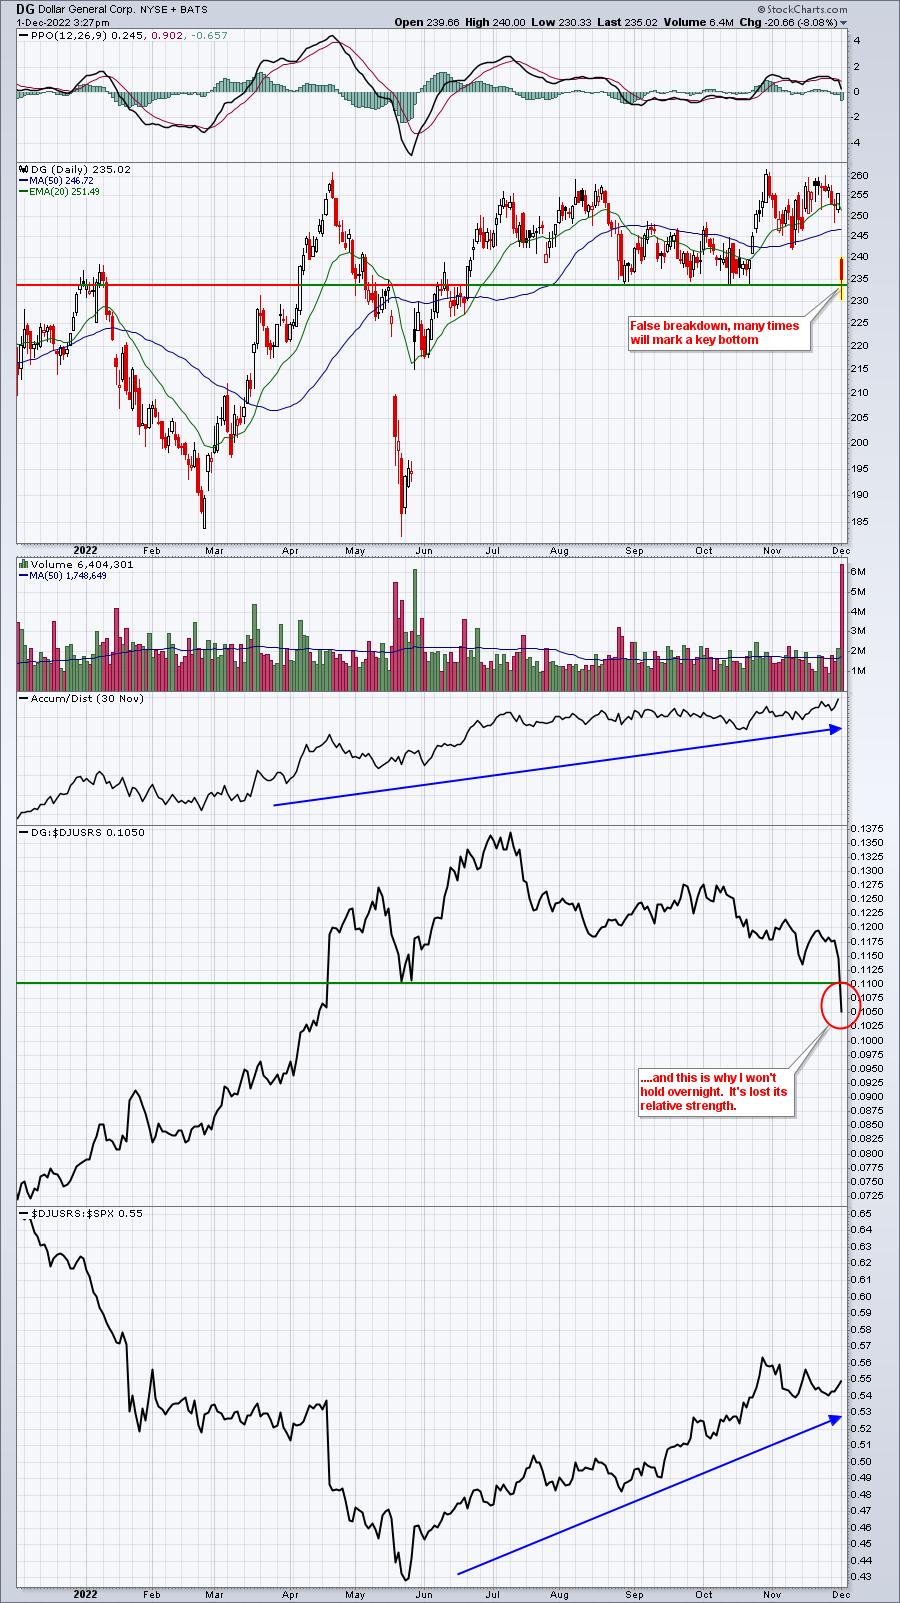
Specialty retail ($DJUSRS) is strengthening, but there are many better options in this industry group than DG right now. It was a quick trade for me and I'm out.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, December 1:
TD, BMO, DG, CM, MRVL, KR, VEEV, ULTA, ZS, PATH, CHPT, SMAR, ASAN, PDCO, AMBA, PD, MEI, GIII, DBI
Friday, December 2:
CBRL
Economic Reports
Initial jobless claims: 225,000 (actual) vs. 238,000 (estimate)
October personal income: +0.7% (actual) vs. +0.4% (estimate)
October personal spending: +0.8% (actual) vs. +0.8% (estimate)
November PMI manufacturing: 47.7 (actual) vs. 47.6 (estimate)
November ISM manufacturing: 49.0 (actual) vs. 49.9 (estimate)
October construction spending: -0.3% (actual) vs. -0.1% (estimate)
Happy trading!
Tom