
EB Daily Market Report - Friday, December 2, 2022
Executive Market Summary
- Futures were down slightly until 8:30am ET; then the November nonfarm payrolls showed a stronger jobs number than expected and futures quickly gave back some of its recent gains
- Commodities are mostly lower with gold ($GOLD, -1.08%) dropping back beneath $1800 per ounce
- The 10-year treasury yield ($TNX) neared key support at 3.50% before rallying 8 basis points to 3.61%
- Technology stocks (XLK, -1.42%) are being hit hardest today, while energy (XLE, -0.03%) has been mostly spared
- All 11 sectors are lower thus far
- Semiconductors ($DJUSSC, -2.04%) are dragging down technology; renewable energy ($DWCREE, +1.56%), on the other hand, remains quite strong
- Drug retailers ($DJUSRD, +0.87%) are bucking the trend and rising to another fresh high on the session
Market Outlook
The gap lower tested short-term price support on the SPY (ETF that tracks the S&P 500). We certainly could bounce right off of this. If not, expect the rising 20-day EMA to be the key support:
I know the November nonfarm payrolls was released this morning and it was slightly hotter than expected. But I follow the charts, not the news. Currently, the market is behaving just fine. That may change by the end of the day, but again, I'd be most concerned if our key indices began failing at rising 20-day EMA support. I'm not going to focus my energy on something that MIGHT happen. I'm bullish.
Sector/Industry Focus
Retailers have rallied back from early weakness. Specialty retail ($DJUSRS), in particular, is showing renewed strength. Check this out:
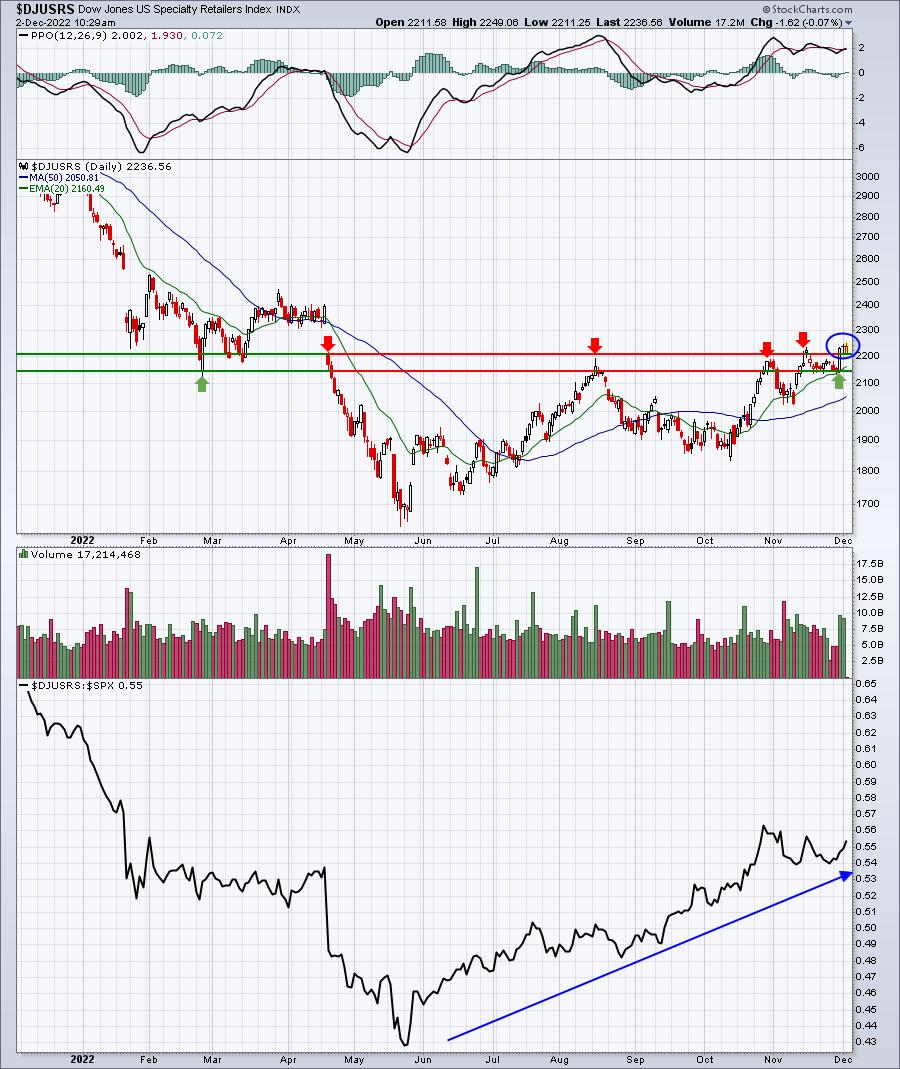
Volume has been nice the past few days and we're seeing a solid advance and breakout. I suspect the group is poised to rally further.
ChartLists/Strategies
We saw early weakness this morning, because of the November nonfarm payrolls. The stock market would like to see weak, but not too weak, numbers. Instead, the report showed jobs higher than expected. The average hourly earnings were double expectations and, to me, that's what spooked everyone when the report was released. I believe this will be an opportunity for traders on the long side. I simply want to see our major indices stay above their respective 20-day EMAs.
Given this morning's selloff, I pulled up the Strong AD ChartList (SADCL) to search for strong stocks (high SCTRs) that are taking an early morning hit. The idea is to buy low this morning and then consider taking profits on any afternoon rebound. Remember, stocks get on this ChartList because of their tendency to finish the day in the upper half of their trading range. Here are the bottom 10 stocks using the Summary view on StockCharts.com as of 10:15am ET:
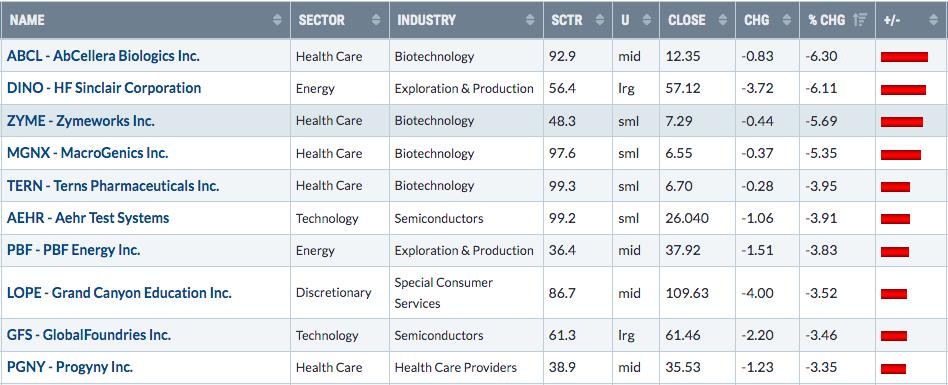
I'll look at two of them, ABCL and PGNY:
ABCL:
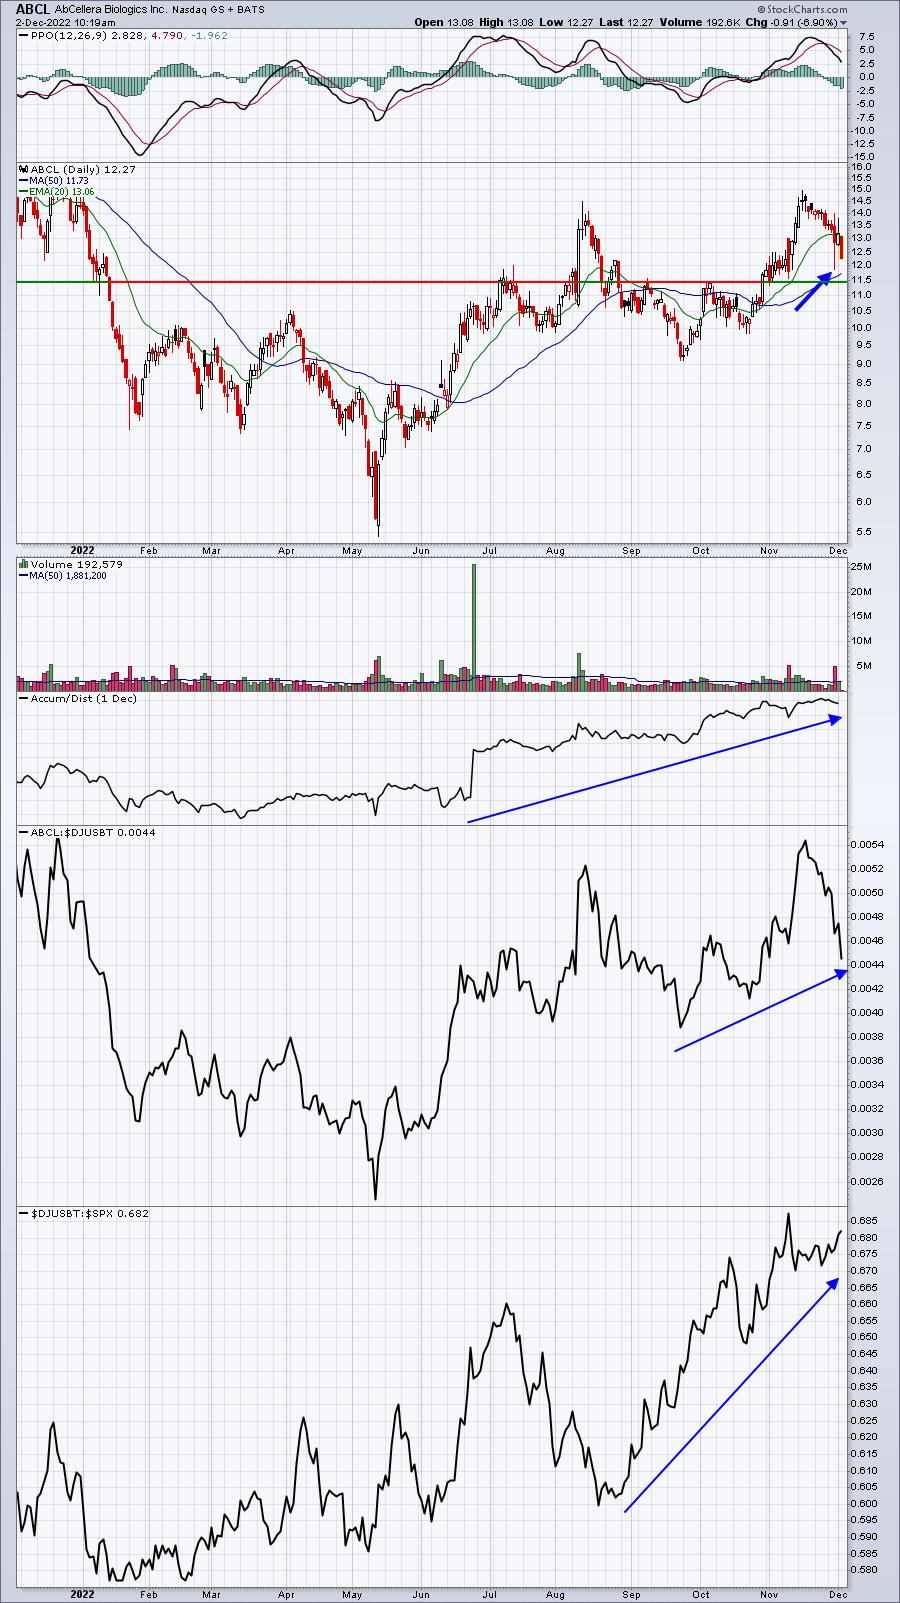
ABCL has a 92 SCTR and is part of the strong biotech industry ($DJUSBT). The blue line above highlights early morning weakness a couple days ago, followed by a nice afternoon rally. I wouldn't be surprised to see it again, though I view key support closer to 11.50-11.75.
PGNY:
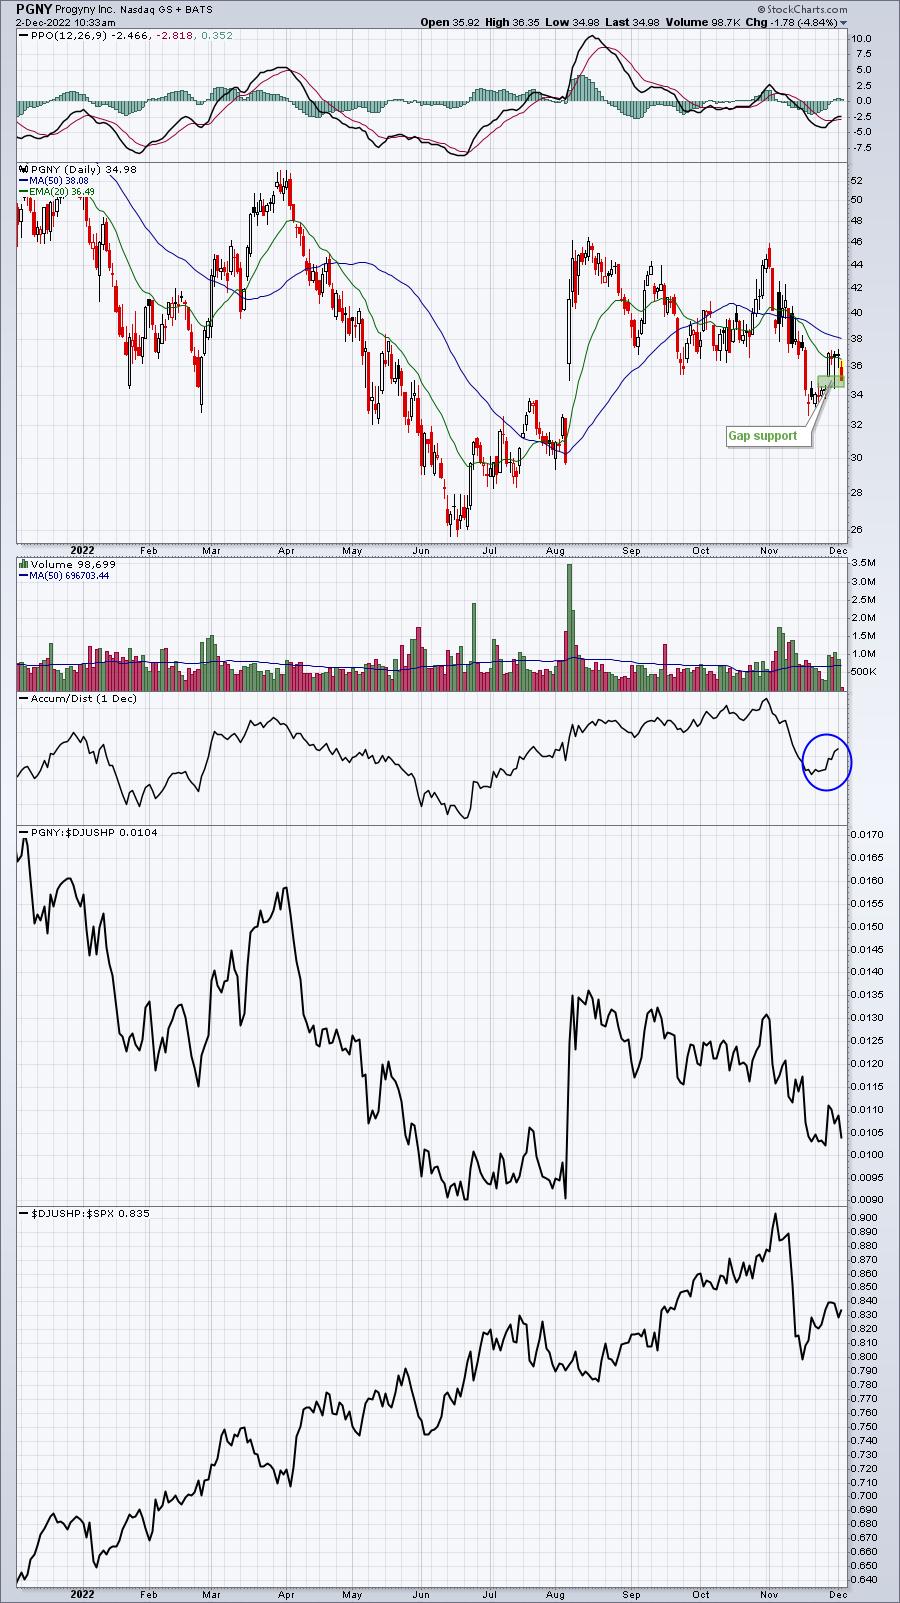
PGNY failed at its 20-day EMA and rolled over, so this is either a good trade today or I'd be out. I like the possibility of a quick bounce off of the gap support zone from a week ago. Any quick move back into the 36.00-37.00 resistance range and I'd take the money and walk away.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, December 2:
CBRL
Monday, December 5:
SAIC, GTLB
Economic Reports
November nonfarm payrolls: 263,000 (actual) vs. 200,000 (estimate)
November private payrolls: 221,000 (actual) vs. 200,000 (estimate)
November unemployment rate: 3.7% (actual) vs. 3.7% (estimate)
November average hourly earnings: +0.6% (actual) vs. +0.3% (estimate)
Happy trading!
Tom