
EB Daily Market Report - Quick Update - Friday, December 9, 2022
This will be brief as I've been out most of the day. I simply want to give you my quick take on the action today.
Inflation
While the big report - the November CPI - won't be released until Tuesday morning, we did get the November PPI, which was slightly hotter than expected. I'm personally more interested in the inflation that's passed onto the consumer, but there was clearly a slight negative reaction this morning when the November PPI was released.
Treasury Yields
The 10-year treasury yield ($TNX) has jumped 8 basis points to 3.57% today. We saw an initial spike after the November PPI was released, but the early treasury selling has continued throughout the day. There's been a lot of buying of treasuries (sending yields lower) the past 6-7 weeks, so some profit taking ahead of the CPI report and Fed meeting next week is to be expected. The 20-day EMA of the TNX is now 3.67%, so that's the initial yield resistance to pay attention to.
Volatility
The Volatility Index ($VIX) has been rising in December as our major indices have faltered, but there's definitely been hesitation on the VIX as it encountered 20-day EMA resistance:
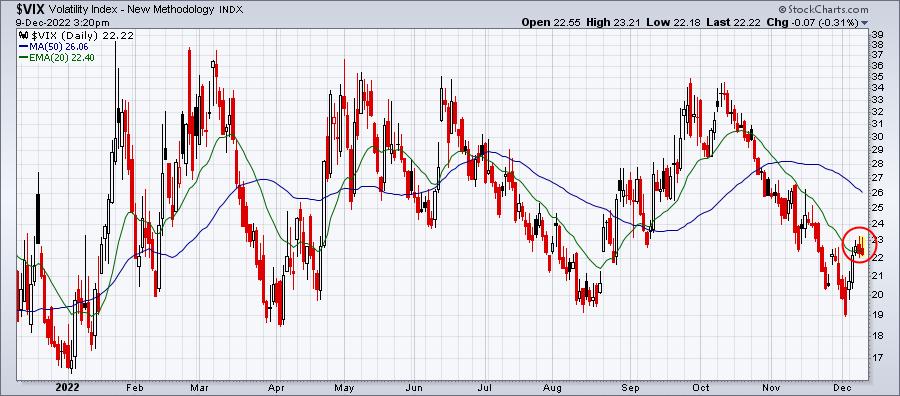
A closing breakout above 23 would be bearish for U.S. equities. But a top at this level and a move back down towards 2022 support in the 18.50-19.50 range would be quite bullish.
Sector Performance
Our major indices are close to the flat line today, with a bit of relative weakness on the Dow Jones Industrial Average and slight outperformance by the NASDAQ. Communication services (XLC, +0.83%) is the top-performing sector as broadcasting & entertainment ($DJUSBC, +1.53%) show strength:
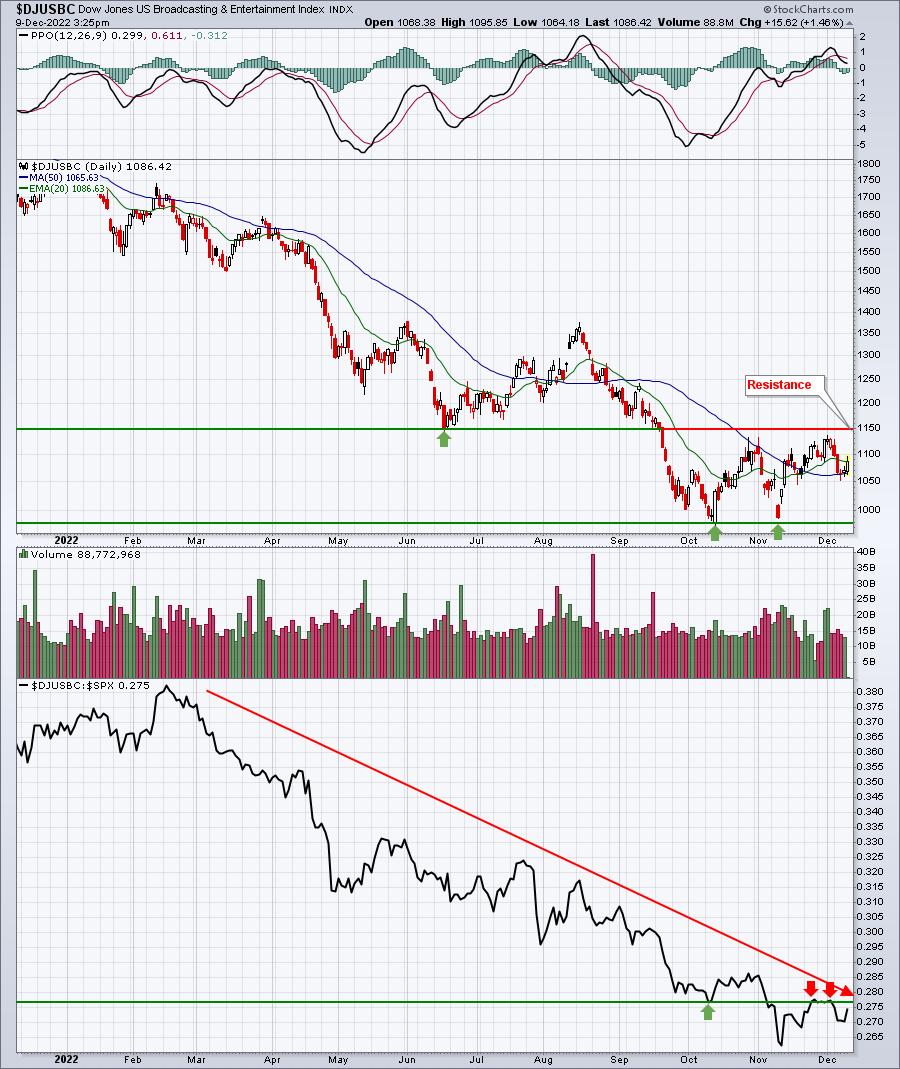
While I'd like to say the DJUSBC is ready to fly, there are still significant technical hurdles to clear first. The relative downtrend remains firmly intact and the DJUSBC's absolute price action is consolidating, at best. Clearing price resistance near 1150 would be a very good first step on this chart, along with clearing relative price resistance at about 0.277.
Historical Tendencies
Keep in mind that while December overall is an excellent month for equities, the overwhelming majority of historical strength has occurred during the second half of December. If we can negotiate the next 2-3 days of BIG news (CPI, Fed meeting), I believe we could be primed for a solid run into year end.
Wishing everyone a great weekend!
Tom