
EB Daily Market Report - Friday, December 23, 2022
Holiday Schedule
We'll have a skeletal staff in place during the holidays. There will be no Trading Places LIVE shows, but I do plan to continue to provide the EB Digest 3x per week. I will likely publish an EB Weekly Portfolio Report, though it might be abbreviated AND I'm not sure what time it might be published, given that both Christmas and New Years fall on Sunday. I honestly have no idea when I might publish a DMR next week. I will try to publish at least one and, of course, will keep you updated if I see anything major taking place.
I want to thank each and every one of you for your support and loyalty in 2022. We could not do what we do without your support. 2022 has been a very challenging year as I discussed it likely would be back in December 2021 and in early 2022. I believe the worst is behind us, but that certainly isn't a guarantee that we don't see lower prices in 2023. Much of that will depend on the Fed's stance as we move into the first quarter - all in my opinion, of course.
I want to wish everyone a very Merry Christmas and Happy New Year! If you don't celebrate the Christmas season, then I wish you happy holidays! Please be safe over the holidays and spend quality time with family and friends! Finally, here's to a prosperous 2023!
Tom and the rest of the EarningsBeats.com Team
Executive Market Summary
- Futures turned a bit weak into the opening bell after being mostly higher overnight
- The NASDAQ again lags as the 10-year treasury yield ($TNX) jumps another 8 basis points to 3.75%
- Commodities are mostly higher, led by crude oil ($WTIC, +2.76%), which is approaching $80 per barrel
- Energy (XLE, +2.96%) is easily the best-performing sector today and for the year (+63.24%)
- 9 of 11 sectors are higher today, with health care (XLV, -0.33%) and technology (XLK, -0.29%) lagging
- The Volatility Index ($VIX) has dropped another 4.51% today, moving back just beneath 21
- Carmax, Inc. (KMX, +4.56%) is one of today's top stocks in the S&P 500, completely filling the big gap lower from yesterday's earnings-related weakness
- Chevron's (CVX, +2.91%) strength is leading the Dow Jones higher
Market Outlook
As a reminder, the following was my "best guess" as to the S&P 500's direction as I provided it on Saturday, January 8, 2022:
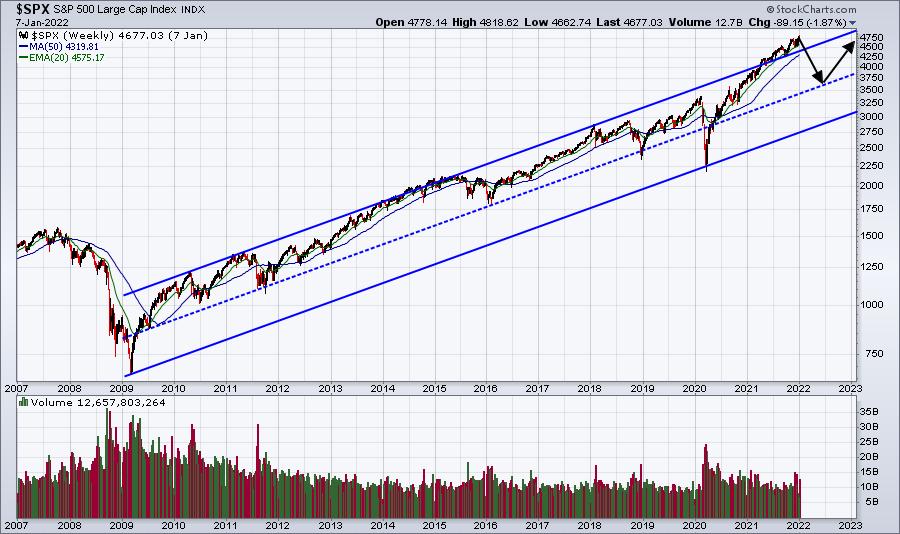
As we prepare to close out 2022, I'd say the overall prediction was pretty solid, though the recovery has not been as swift as I had expected. Here's how the above chart now looks with 2022 price action included:
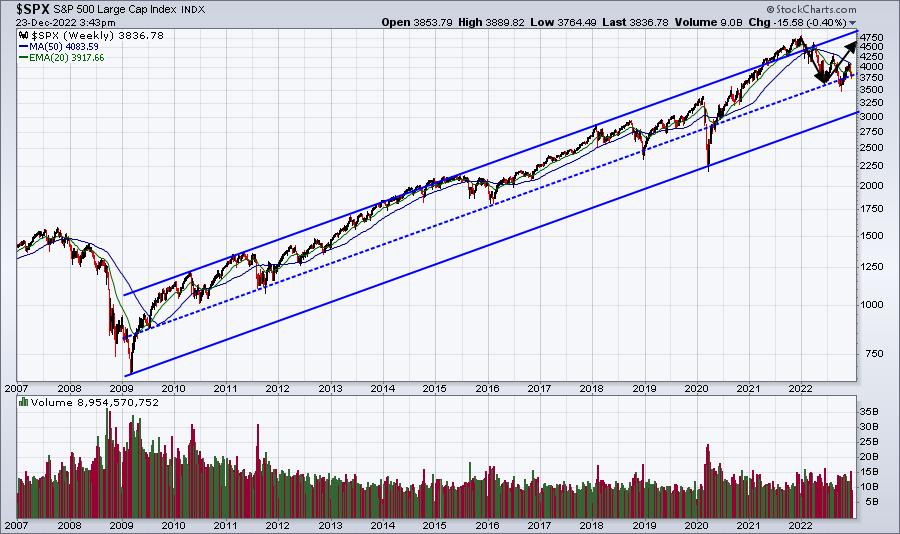
We've still got our work cut out for us as we end 2022 and move into 2023. I'll provide my annual forecast in two weeks at MarketVision 2023 on Saturday, January 7, 2023. I hope you'll be able to join us!
Sector/Industry Focus
The S&P 500 has climbed roughly 4% over the past 3 months and here's the breakdown of sector strength over that same period:
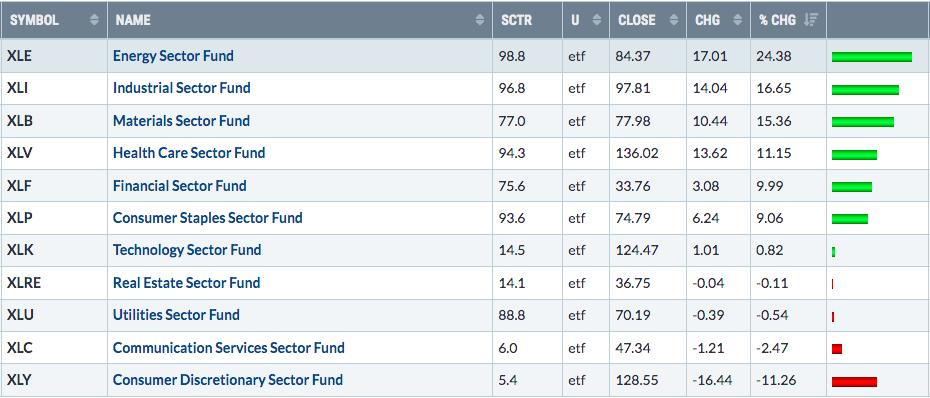
If you feel compelled to trade individual stocks, it might be best to stick with the sectors that remain relatively healthy - energy, industrials, materials, and health care.
ChartLists/Strategies
I'm patiently awaiting better relative strength in key areas like semiconductors ($DJUSSC), software ($DJUSSW), and internet ($DJUSNS). Until that occurs, we'll likely be in a choppy market - best case.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, December 23:
None
Monday, December 26:
None
Economic Reports
November durable goods: -2.1% (actual) vs. -0.8% (estimate)
November durable goods ex-transports: +0.2% (actual) vs. +0.0% (estimate)
November personal income: +0.4% (actual) vs. +0.3% (estimate)
November personal spending: +0.1% (actual) vs. +0.2% (estimate)
November new home sales: 640,000 (actual) vs. 600,000 (estimate)
December consumer sentiment: 59.7 (actual) vs. 59.1 (estimate)
Happy trading!
Tom