
EB Daily Market Report - Thursday, March 2, 2023
ChartLists Updated
I'm continuing to work on our ChartLists before I head on vacation. By tomorrow morning, you should be able to view/download the following ChartLists from our website:
- Raised Guidance (RGCL)
- Strong AD (SADCL)
- Bullish Trifecta (BTCL)
That should bring all of our key ChartLists up to date, while I'm on vacation.
Vacation Starts Tomorrow
I'll be out of the country on vacation from tomorrow through next Friday, March 10th. There will be no Trading Places Live shows during that period, although there will likely be earlier recordings replayed on StockCharts TV on Tuesday, March 7th and Thursday, March 9th. There will be no Daily Market Reports on Friday, March 3rd or the following week, but John Hopkins will provide everyone at least a brief market update each day. There will be no EB Weekly Portfolio Report on Sunday, March 5th, though I should be back in time to provide one on Sunday, March 12th.
I hope everyone has a great week while I'm gone, I certainly hope I will! It's been a long time since I took a vacation without any work responsibility, so I'm looking forward to getting away and relaxing. It's been a difficult market the past couple years and I think we've done as solid a job as anyone in terms of market guidance through it all. I'll be back a week from Monday refreshed and ready to get back at it.
Executive Market Summary
- Futures were bifurcated overnight, with strength on the Dow Jones and weakness on the NASDAQ
- Q4 unit labor costs were reported much higher than expected, sending the 10-year treasury yield ($TNX) higher in anticipation of another upcoming Fed rate hike
- That sent the dollar (UUP, +0.58%) higher, though gold (GLD) has remained relatively flat
- Despite the prospects of higher rates and potentially lower equity prices, the Volatility Index ($VIX, -3.94%) has fallen back beneath 20; folks, fear continues to dissipate, which is quite bullish, in my view
- Ignore the bad news that the media will focus on, and instead focus on what matters most - the charts
- Crude oil ($WTIC, +0.41%) is fractionally higher and back above $78 per barrel
- Energy (XLE, +1.08%) is up nicely today, but utilities (XLU, +1.69%) is today's big winner
- Financials (XLF, -0.55%) and consumer discretionary (XLY, -0.50%) are the only two sectors in negative territory
- Salesforce.com (CRM, +11.18%), a Dow Jones component stock, reported excellent quarterly results and is leading the Dow Jones to its relative strength today
Market Outlook
The XLY:XLP ratio is one of my favorites to watch and it was extremely encouraging to see this ratio soar during January. It's run into a bit of difficulty in February and its history in March isn't great. So what might we expect in terms of its potential relative pullback in March? Keep in mind that we've already seen a relative pullback, so there's no guarantee it continues. But to give us an idea of what we might look for IF this ratio does remain weak, let's look at a relative chart using the Fibonacci retracement tool:
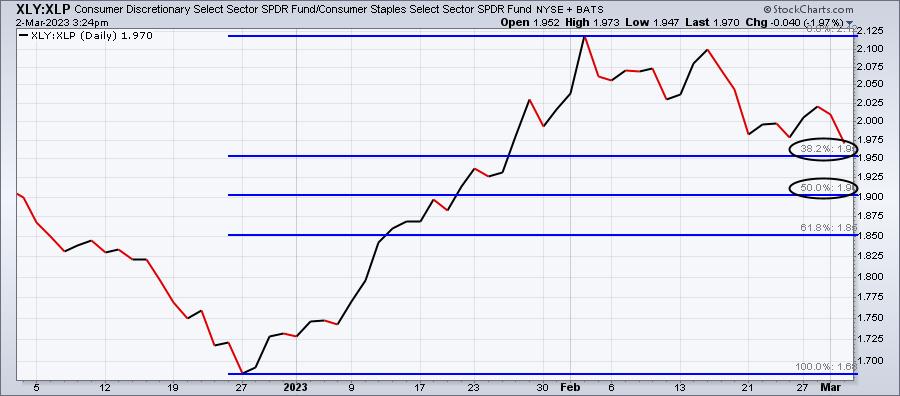
The 38.2% and 50.0% retracements are the two most popular and the two most often tested during pullbacks. We're almost to the initial 38.2% retracement. If we can bounce off of this level, it would be very bullish for U.S. equities and their likely direction through the balance of March. If we fail, however, at this 38.2% level, then a trip to test the 50.0% retracement level would be more likely and such a trip would most likely coincide with further market weakness and/or rotation.
Let me be very clear about one thing. Despite all my talk about possible rotation and weakness in March, I AM VERY BULLISH the stock market. I would rather be invested and lose a portion of my investments during March than move to cash and watch the stock market ignore short-term issues and soar higher. If the market moves higher, I want to be in the move higher.
Sector/Industry Focus
Today we've seen a nice rebound, but leadership is coming in the form of utilities (XLU), which love the month of March, and consumer staples (XLP), which typically outperforms the XLY in March. I don't know if this is the start of a new trend favoring defensive stocks, but it's certainly happened plenty of times before during March. The XLU is printing a reversing bullish engulfing candle:
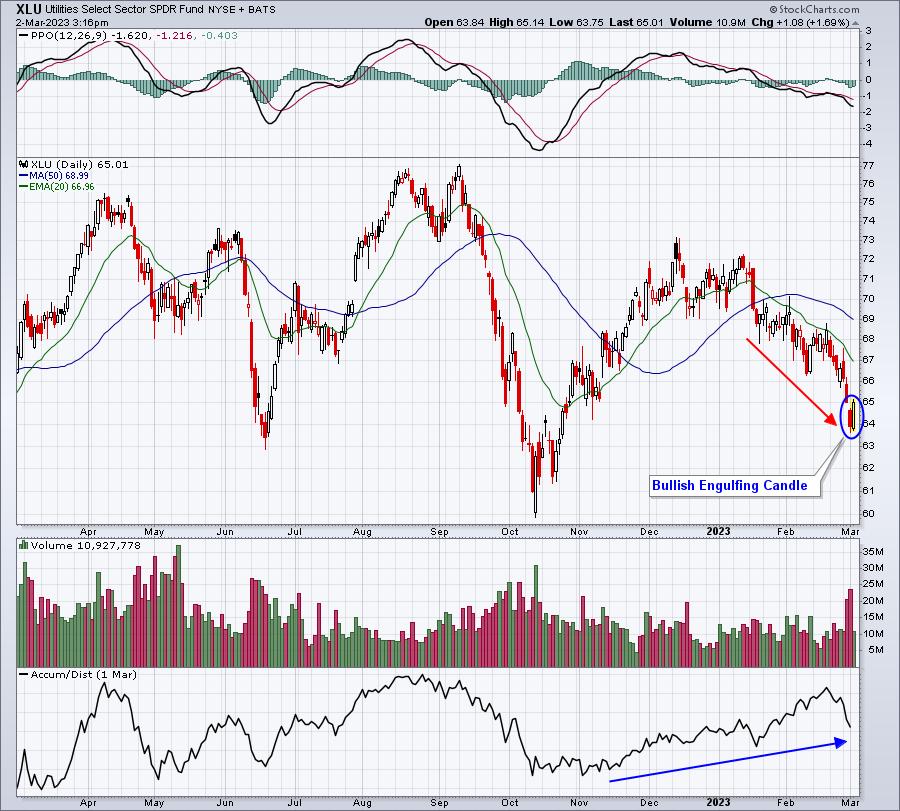
The AD line has remained fairly strong on the XLU, despite the recent selling. I don't know if today's reversal is THE candle that suggests rotation back to utilities is taking place, but jumping in (if you're an ETF trader) and then keeping a stop beneath yesterday's low makes sense to me, given the historical boost that March typically provides utilities. It's also a defensive approach to a market that appears at least somewhat vulnerable this month.
ChartLists/Strategies
Here are two stocks that I've recently mentioned that I took nice profits on today:
SPLK:
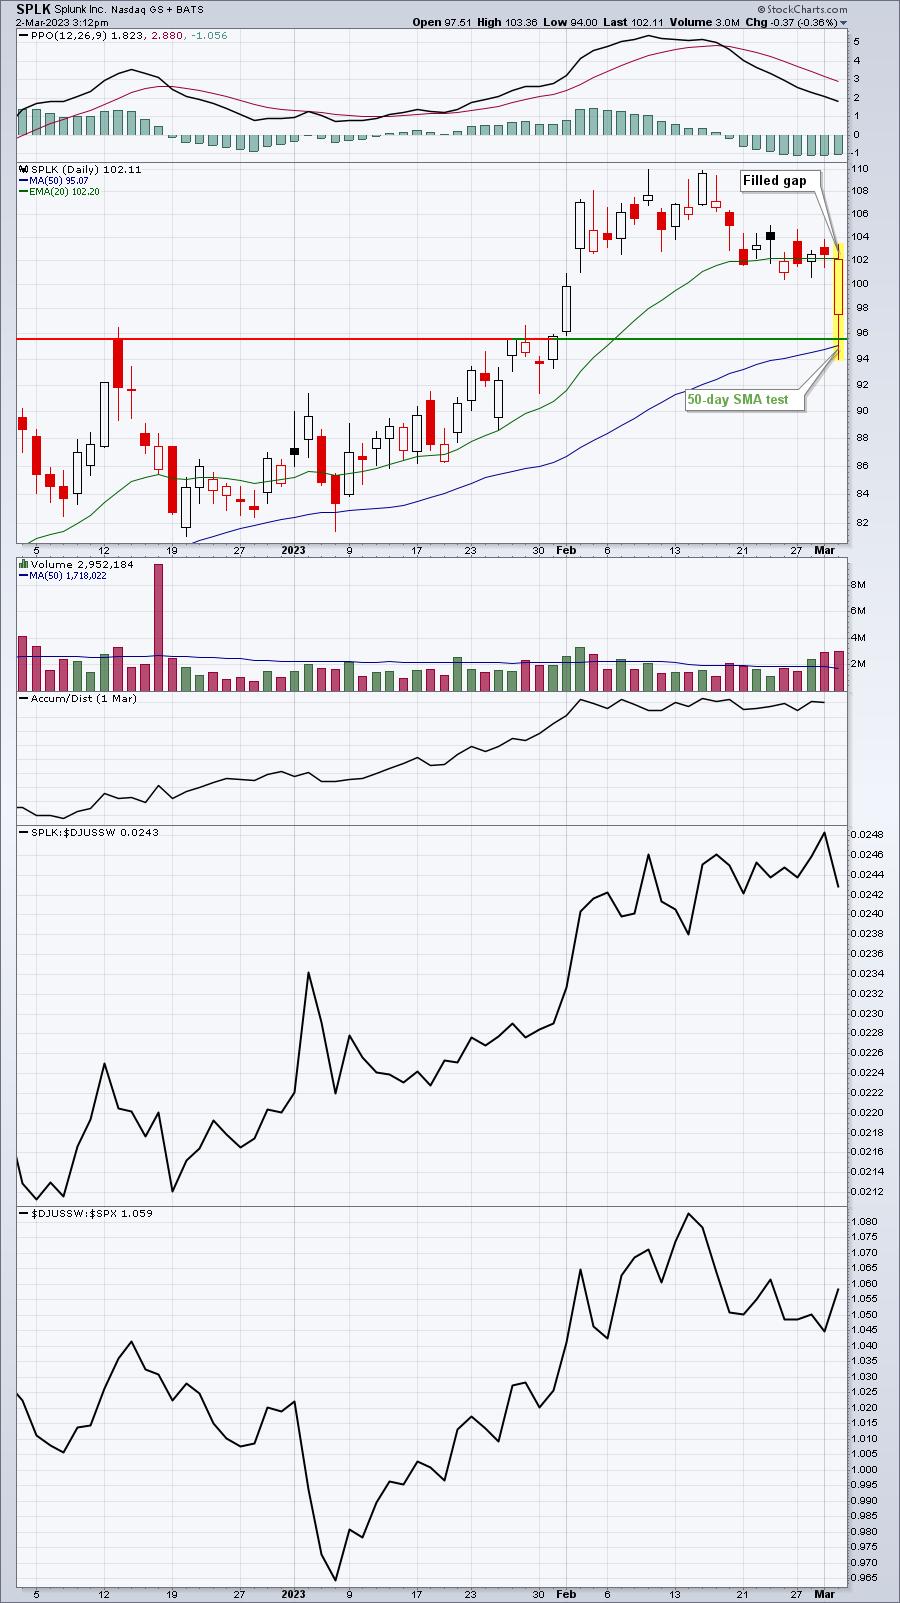
I wrote about this one recently in the EB Digest, really liking the way it's been trading on a relative basis. They absolutely blew away estimates, yet a "sell on the news" mentality allowed a drop back to the 95 level, which I mentioned on my TP Live show this morning at StockCharts.com as a very interesting entry level. After a very quick reversal off the 50-day SMA, I sold when SPLK filled its gap at yesterday's close of 102.48. It may continue higher, but by taking profits, I also eliminate any risk and add to cash levels for future trading opportunities.
EHTH:
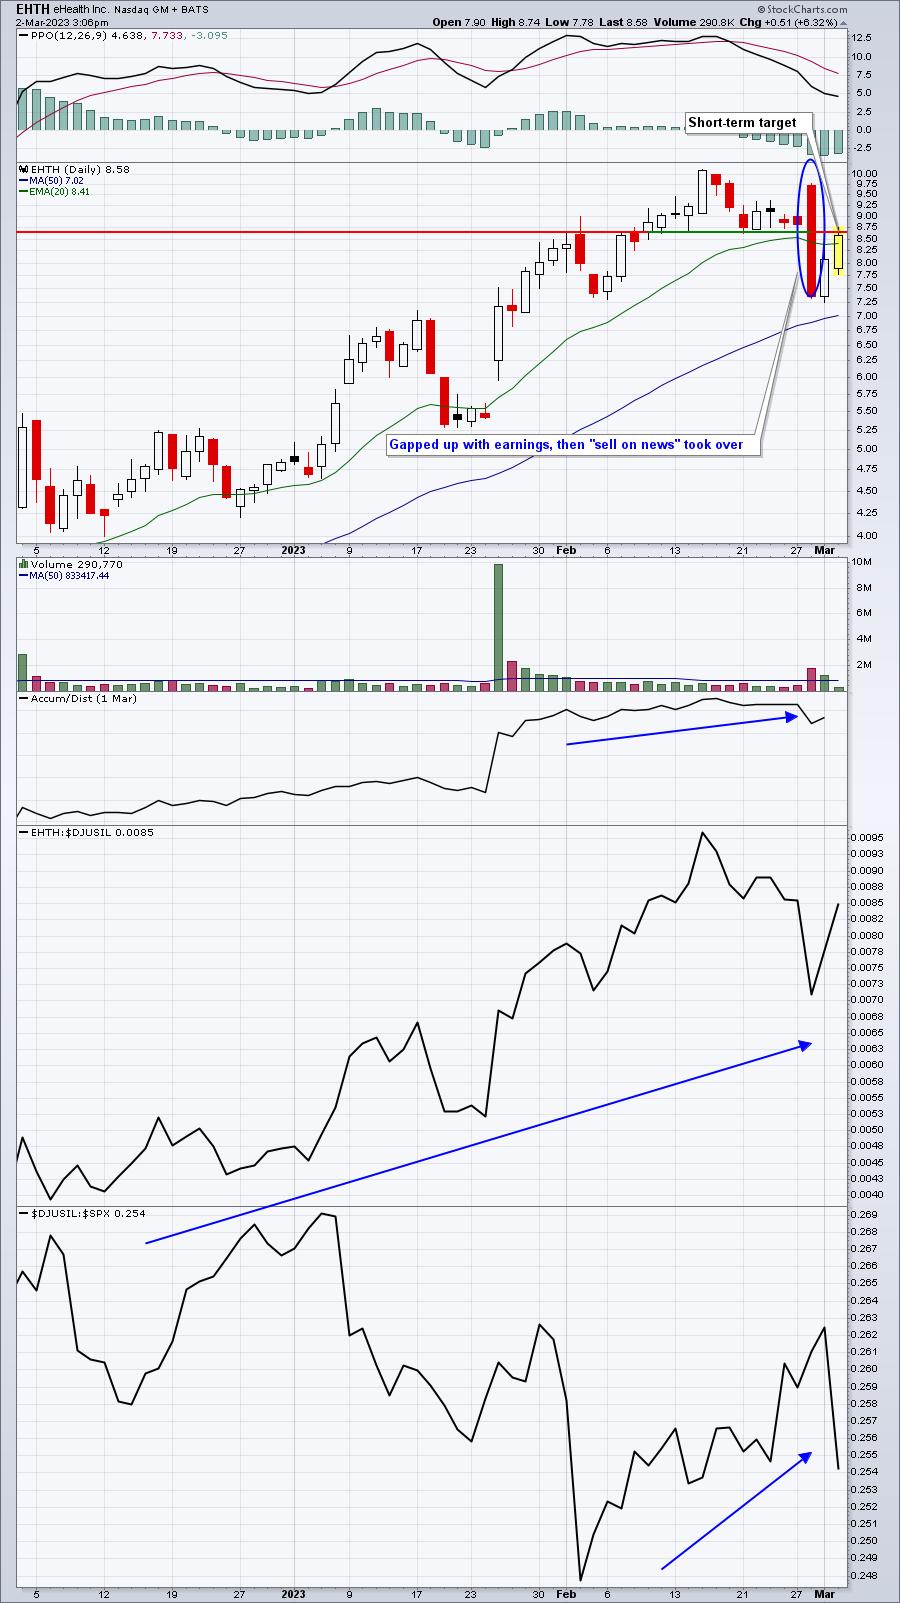
I didn't hit my third entry near 7.00, but I did fill just below 8.00 and then again at 7.40 (close to the early-February low). As EHTH reached a key short-term resistance level, I took profits. It may go right through and set new highs, but a quick 12% profit was too much for me to pass up in just a couple days.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, March 2:
AVGO, COST, TD, BUD, CNQ, VMW, MRVL, KR, DELL, HRL, ARGX, HPE, ZS, BBY, COO, AER, BURL, BILI, ESTC, M, CHPT, SFM, VSCO, JWN, PAGS, PDCO, AI, UTZ, SIX, XPOF
Friday, March 3:
None
Economic Reports
Initial jobless claims: 190,000 (actual) vs. 200,000 (estimate)
Q4 productivity (2nd estimate): +1.7% (actual) vs. +2.5% (estimate)
Q4 unit labor costs (2nd estimate): +3.2% (actual) vs. +1.4% (estimate)
Happy trading!
Tom