
EB Daily Market Report - Wednesday, August 30, 2023
Live All-Day Trading Session
We had an all-day trading session scheduled for today, but due to personal matters, I was required to travel out of town recently and was unable to prepare adequately for this type of event. Therefore, we had to postpone the event. I suspect we'll reschedule during Q4 and have TWO all-day, live trading sessions, one in late October and the other prior to the Thanksgiving holiday in November. We'll post dates as soon as we have them.
I apologize for any inconvenience and certainly appreciate your understanding.
Executive Market Summary
- Futures were mixed overnight and fairly close to the flat line, but did turn positive after the ADP employment report showed a positive jobs number, but one that was below expectations
- It's been another fairly solid day of trading as our key indices and sectors hold onto, and build on, Tuesday's gains
- Technology (XLK, +0.65%) leads the market higher once again, with energy (XLE, +0.49%) rebounding
- Crude oil ($WTIC, +0.52%) moving higher has aided the rebound in the XLE
- Meanwhile, the defensive utilities (XLU, -0.60%) is the only sector with losses above 0.10%
- Computer hardware ($DJUSCR, +1.78%) is helping technology's advance, as Apple, Inc. (AAPL, +1.91%) has recaptured its 50-day SMA
- Cryptocurrencies are struggling today to build upon those rapid gains from yesterday; after surging more than 2000 points yesterday, bitcoin ($BTCUSD, -1.17%) is seeing profit taking today
- The 10-year treasury yield ($TNX) is relatively flat, dropping less than 1 basis point on the session
- HP, Inc. (HPQ, -6.69%) is today's worst S&P 500 performer after providing a disappointing outlook; HPQ is shown below in our ChartLists/Strategies section as it could set up for a short-term rebound
Market Outlook
Let's look at growth (IWF) vs. value (IWD):
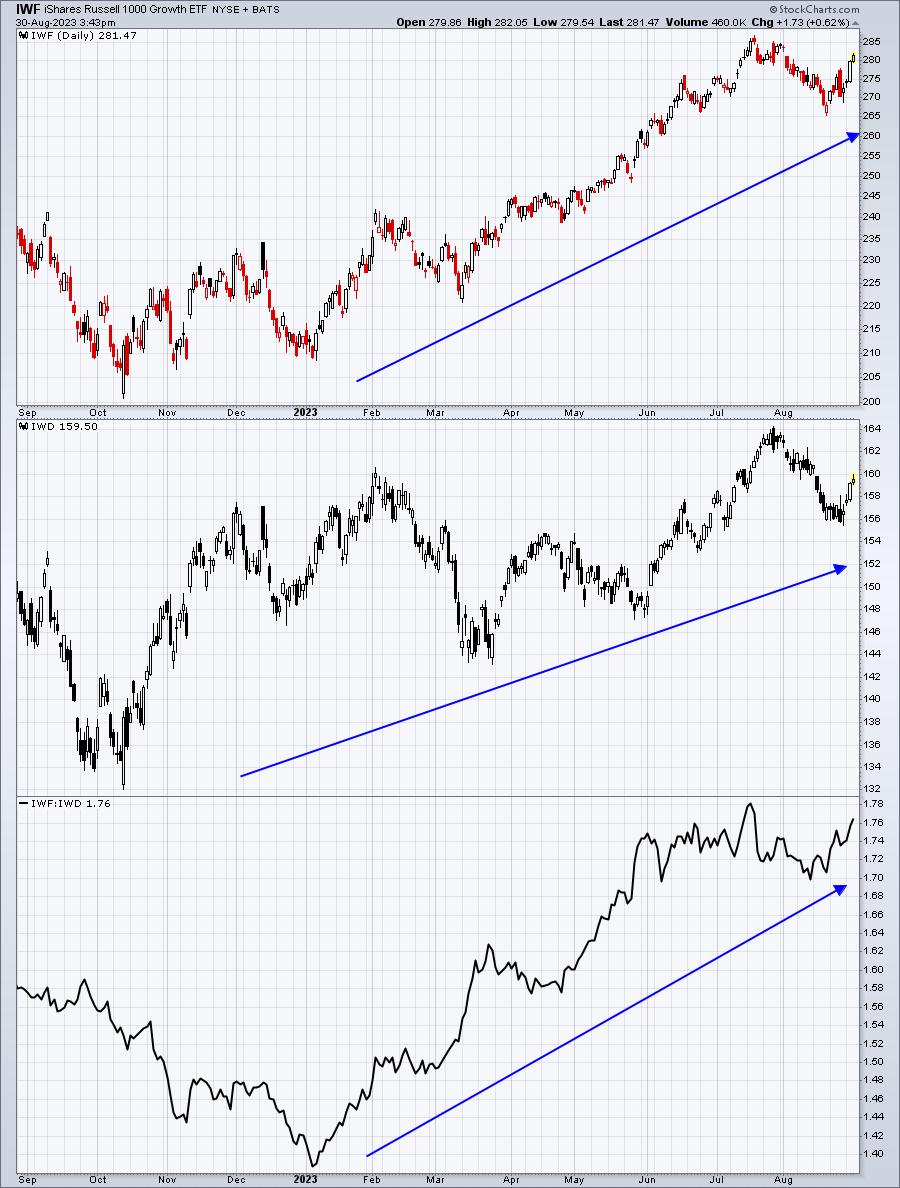
Both the IWF and IWD are bouncing and remain in uptrends. But that bottom intermarket relationship, IWF:IWD, shows money pouring (rotating) from value back into growth and this rotation has been occurring for 2-3 weeks now, not just during this week's advance. Wall Street is quickly moving back into growth, confirming what I believe will be bullish market action through year end and into 2024.
Sector/Industry Focus
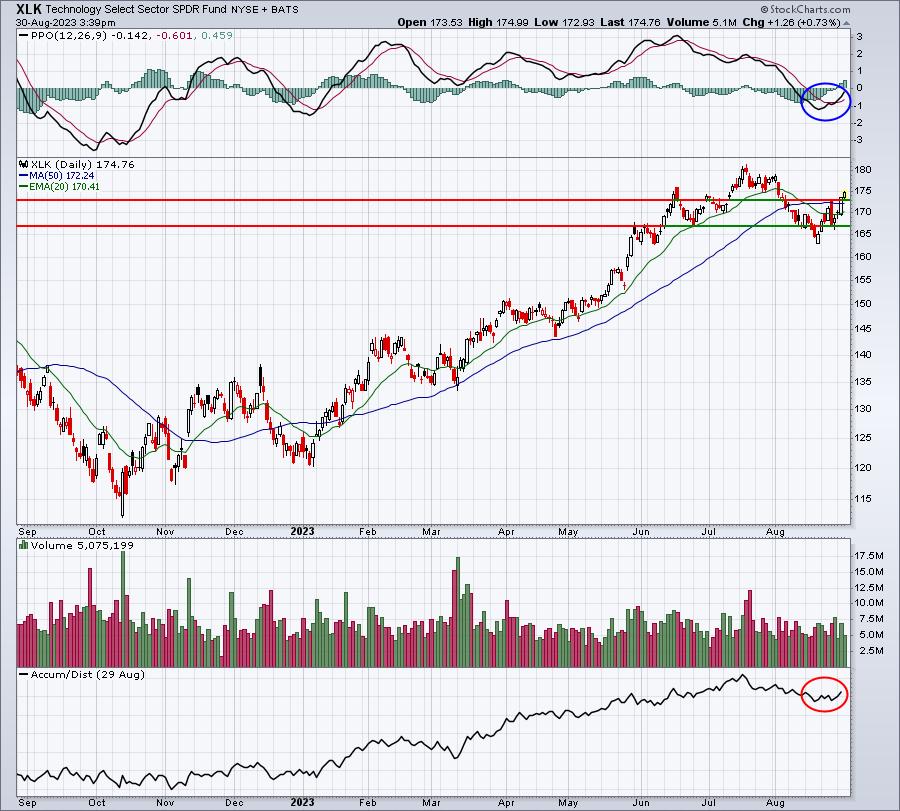
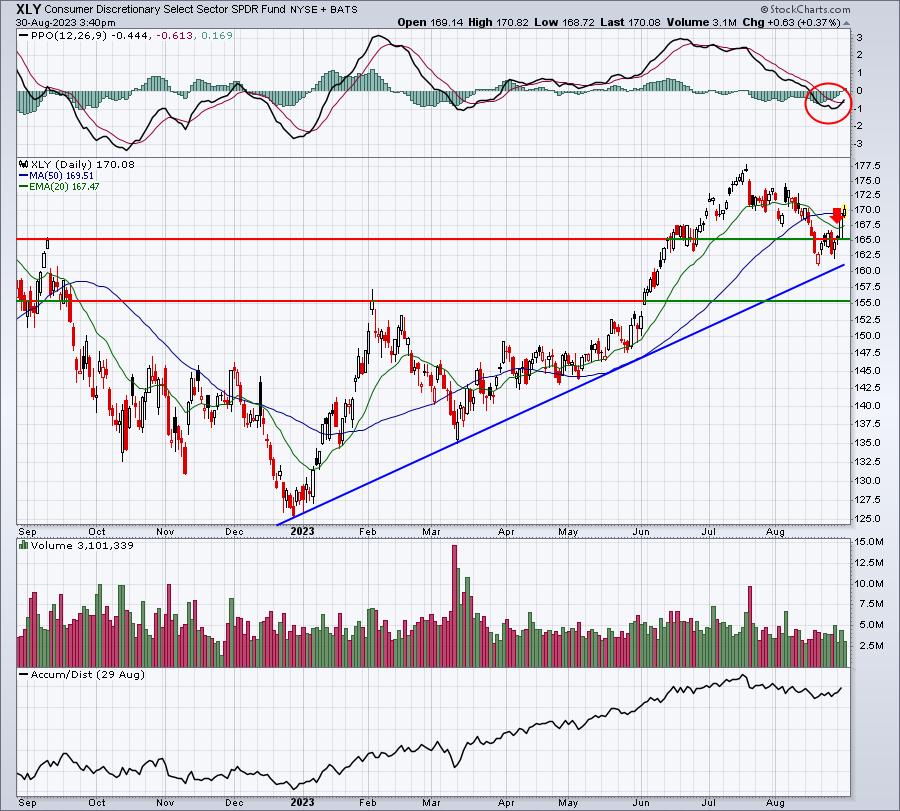
On Monday, I provided charts of the XLK, XLY, and XLC, showing resistance levels that I wanted to see cleared to begin feeling more bullish about the overall market. Those levels have been cleared. Here are the 3 updated charts as a reminder as to what was discussed:
XLK:
XLY:
XLC:
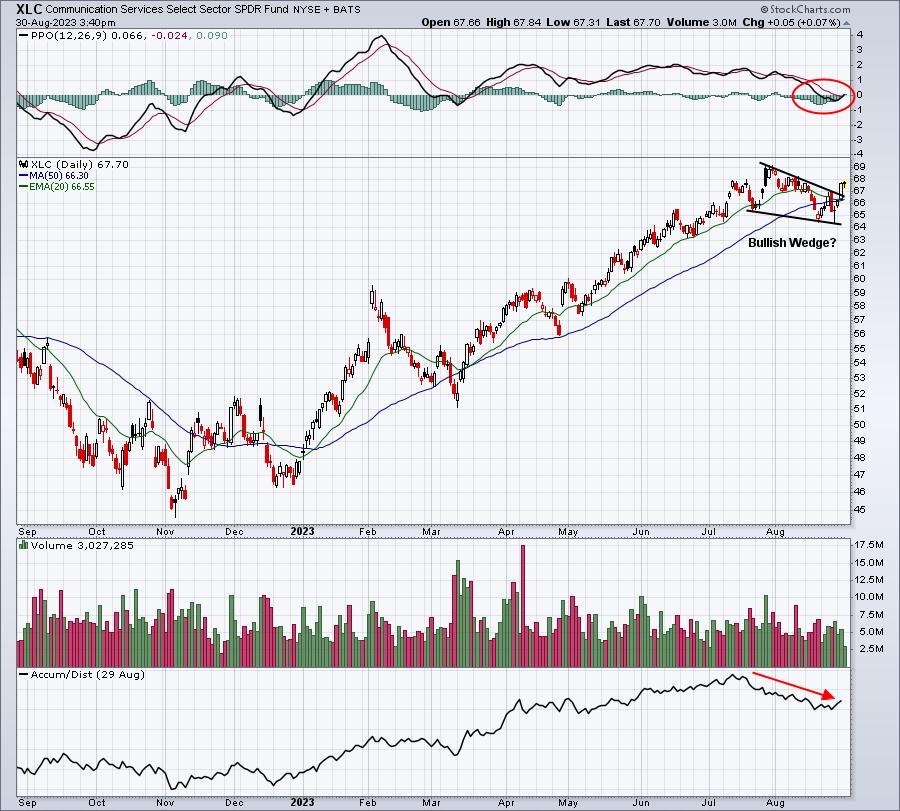
While the price action most definitely has been bullish, I also like the fact that the AD lines for all 3 of these key sectors has turned higher again as well.
ChartLists/Strategies
HP Inc. (HPQ) disappointed with its market outlook and the sellers were out in droves this morning. However, HPQ has bounced back solidly, potentially holding onto a key support level. Technically, today's candle is a "long-legged doji", which can represent a significant reversal. Here's the chart:
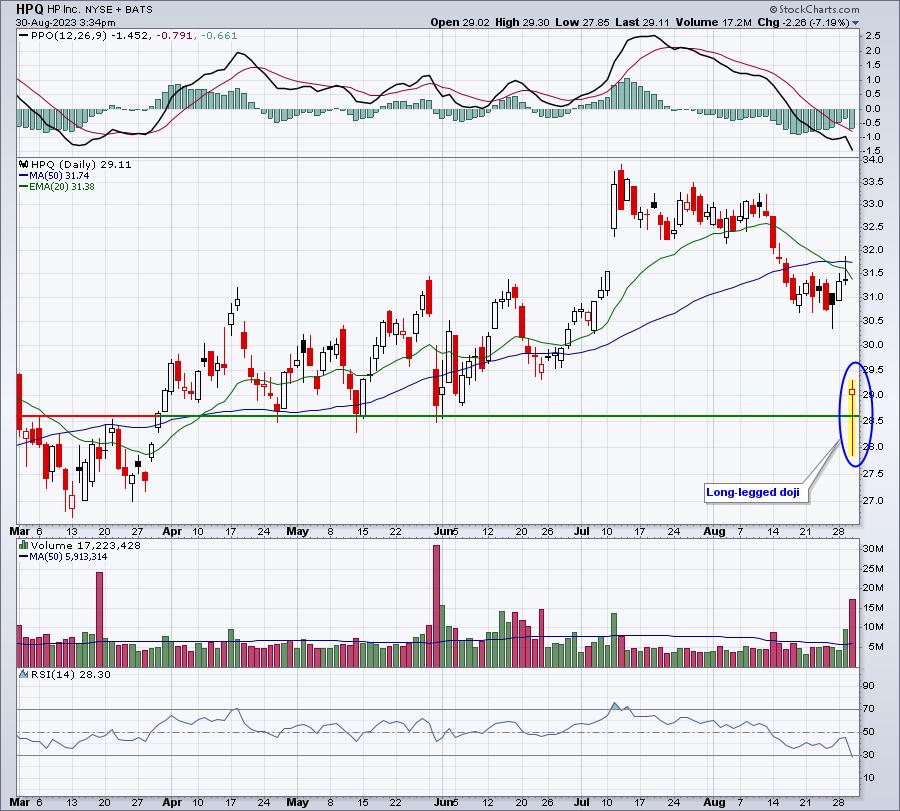
The fact that it dropped so far below 28.00 tells us that new sellers were found and the stock's subsequent recovery increases the odds that a rally could continue. If it does, I'd treat it as a short-term recovery only. Anything back near 30.50-31.00 would likely see additional sellers lining up. At that point, I'd take any profits and RUN!
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Wednesday, August 30:
CRM, CRWD, BF/B, VEEV, COO, OKTA, CHWY, PSTG, FIVE, GEF, PDCO, VSCO
Thursday, August 31:
AVGO, VMW, LULU, DELL, CM, DG, MDB, HRL, BEKE, IOT, CPB, NTNX, CIEN, ESTC, OLLI, SIGN, MOMO
Economic Reports
August ADP employment report: 177,000 (actual) vs. 200,000 (estimate)
Q2 GDP (2nd estimate): 2.1% (actual) vs. 2.4% (estimate)
July pending home sales: +0.9% (actual) vs. -0.4% (estimate)
Happy trading!
Tom