
EB Daily Market Report - Thursday, December 7, 2023
Executive Market Summary
- Futures were higher overnight and we saw our major indices gap up at the opening bell
- Relative strength is found on the NASDAQ 100 today, though all key indices are higher
- Leadership is solid as communication services (XLC, +2.16%), technology (XLK, +1.24%), and consumer discretionary (XLY, +0.71%) lead today's action
- Energy (XLE, -0.81%) again lags the other 10 sectors, adding to its breakdown on Wednesday
- Crude oil prices ($WTIC, +0.17%) are flat, but the inability to stay above $70 per barrel is weighing on energy traders
- The 10-year treasury yield ($TNX) is up 2 basis points to 4.14%, as the TNX hovers near 4.10% as a BIG economic report awaits
- The November nonfarm payrolls will be out early tomorrow morning and that could have a significant impact on both the stock and bond markets
- I'll be on semiconductor watch tomorrow as Broadcom, Inc. (AVGO, +1.83%) reports its latest quarterly earnings after the bell today (Full Disclosure: I am not holding any AVGO into today's earnings report); I'm hoping for a solid report and gap higher, but the heavy volume selling the past 2 weeks leaves me skeptical
- Semiconductors ($DJUSSC, +2.43%) are strong today, led by Advanced Micro Devices (AMD, +9.31%)
- Internet ($DJUSNS, +4.19%) is even stronger as Alphabet, Inc. (GOOGL, +5.29%) jumps; both AMD and GOOGL are lifting optimism for AI chips, prompting many large cap names to perform well on the session
Market Outlook
Tomorrow morning, we'll get the latest nonfarm payrolls information for November. The consensus range is from 110,000 to 240,000, with the consensus estimate set at 180,000. October nonfarm payrolls were 150,000. My belief is that the market would like to see a positive number, but one that is less than consensus. Something around 100,000 would likely keep the Fed on pause and the soft landing hopes alive and kicking.
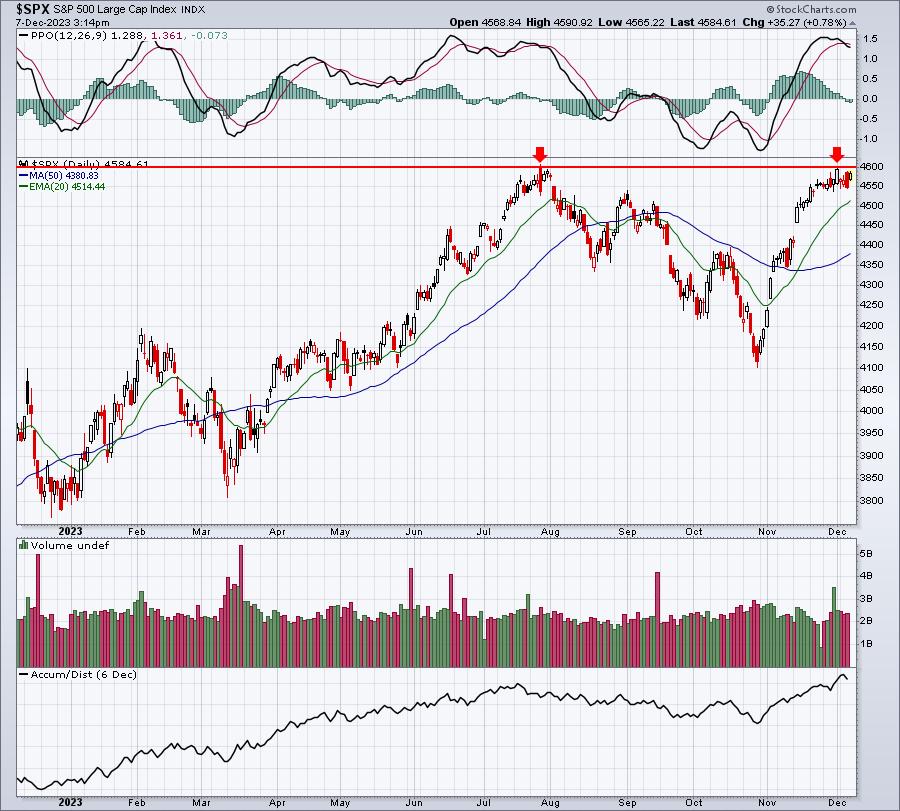
For now, we're just meandering sideways on our major indices, with all eyes remaining on 4600 resistance on the S&P 500:
As for the NASDAQ 100, there are a few ominous short-term clouds around as the daily PPO has rolled over:
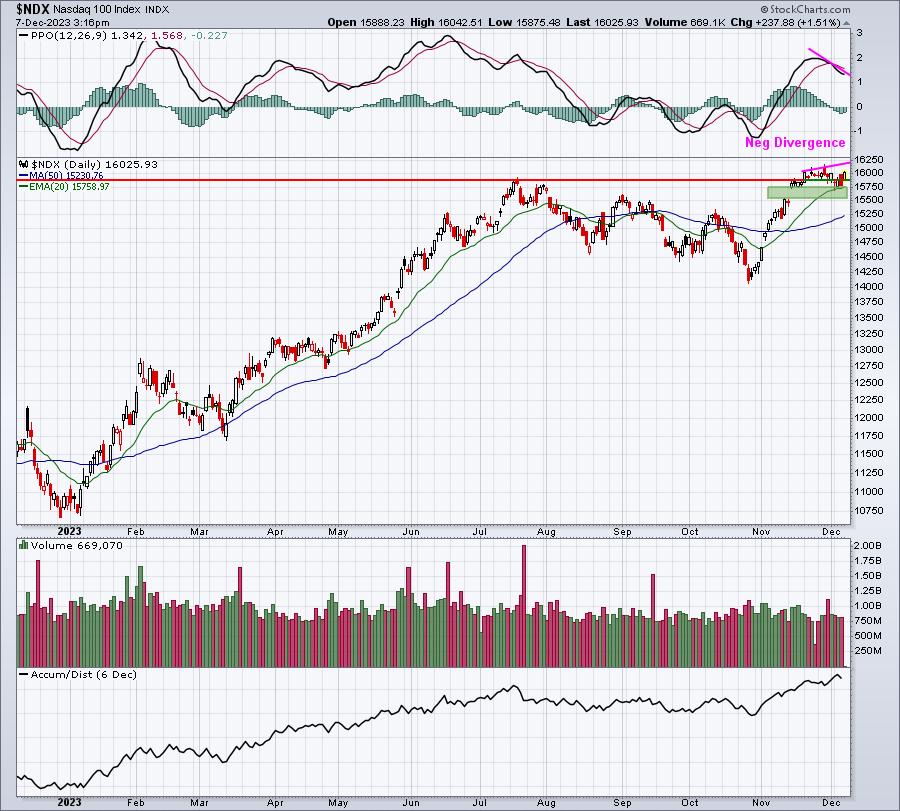
To the downside, we have gap support to aid the bulls on any short-term selling. Meanwhile, we're not far from a breakout, but with a breakout would come a bearish negative divergence. It's almost like we need to be careful what we wish for here.
Sector/Industry Focus
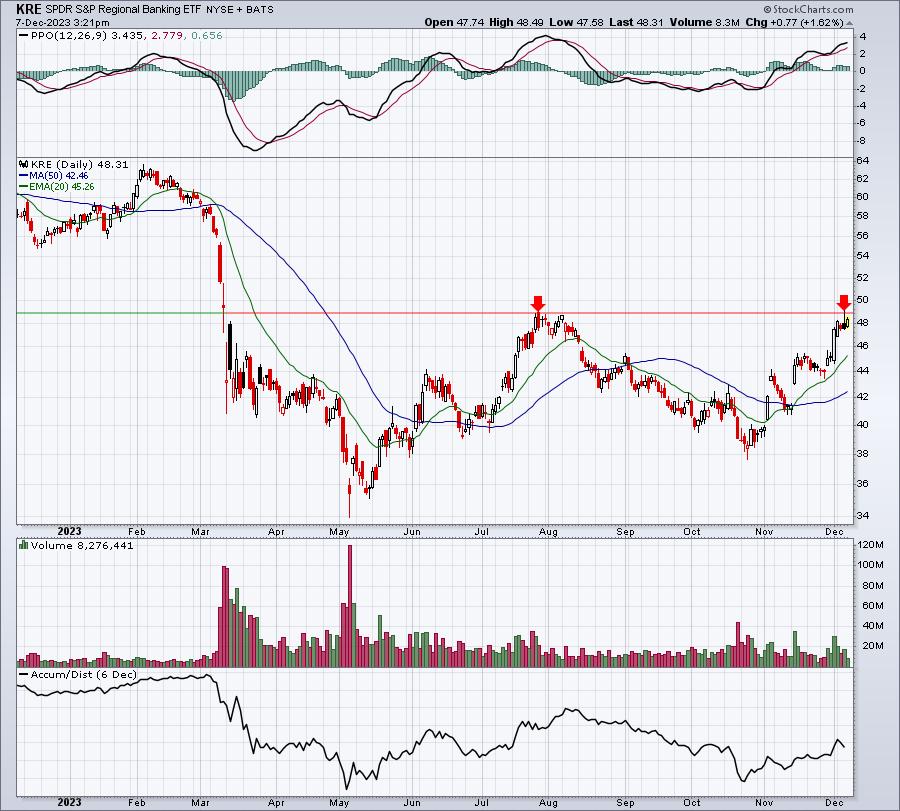
Regional banks (KRE) represent the largest weighting in the Russell 2000 (IWM) small cap index. You can see from the chart below that KRE is at a very important level. Further strength would bode well for the IWM, while failure at resistance would likely hold up IWM progress for a bit:
ChartLists/Strategies
Given next week's historical bearishness and suspect divergences telling us to be careful due to slowing momentum, not to mention a big economic report in nonfarm payrolls to be released tomorrow morning before the opening bell, let's wait until tomorrow to see if any individual stock trades make sense.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, December 7:
AVGO, LULU, DG, COO, DOCU, MTN, GWRE, CIEN, SMAR, RH
Friday, December 8:
MOMO
Economic Reports
Initial jobless claims: 220,000 (actual) vs. 222,000 (estimate)
October wholesale inventories: -0.4% (actual) vs. -0.2% (estimate)
Happy trading!
Tom