
EB Daily Market Report - Thursday, January 25, 2024
Model ETF Portfolio - Wednesday Entry
We sent out a quick post that we entered our Model ETF Portfolio at yesterday's close. The overall market doesn't exactly look great, especially with the last few days showing opening gaps with little follow through. But our portfolios were not designed to sit in cash for extended periods of time. We allowed a few days to see if we could enter our Model ETFs at lower prices, as we did in the last quarter, but the market just hasn't cooperated this time. The 19th through 25th period of calendar months has been the most bearish period of the month since 1950 on the S&P 500. So we had good reason to wait, but it hasn't panned out.
Executive Market Summary
- Futures were higher overnight and our major indices jumped to an early bullish start
- We've seen mostly selling since, however, and this is becoming a common theme of late
- The IWM has fallen back to its key opening gap higher from last week; the small cap bulls need to defend this area in the short-term as it also coincides with its 20-day EMA support
- Crude oil ($WTIC, +2.01%) is continuing its recent rise, and is now closing in on $77 per barrel
- Other commodities like gold ($GOLD, -0.04%), silver ($SILVER, -0.10%), and copper ($COPPER, -0.42%) are lagging
- Surprisingly, the 10-year treasury yield ($TNX) is down 5 basis points to 4.13%, despite a much better Q4 GDP than was expected
- Leadership today is in real estate (XLRE, +1.28%), yesterday's laggard, and communication services (XLC, +1.27%)
- All 6 industry groups in the XLC are having a nice session, led by fixed line telecom ($DJUSFC, +1.97%); AT&T's (T, +2.01%) gain is no doubt helping here
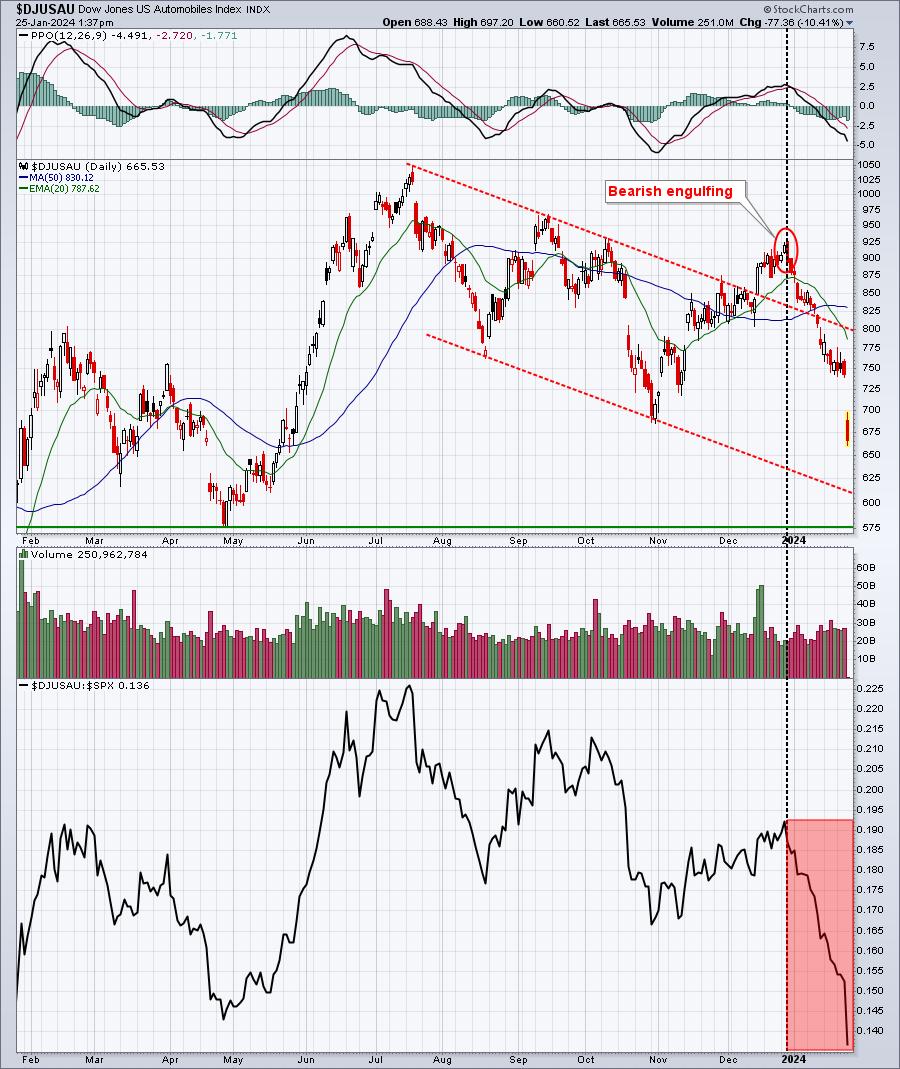
- Meanwhile, consumer discretionary (XLY, -1.49%) is being thrashed after the horrific earnings report from Tesla (TSLA, -12.48%); automobiles ($DJUSAU, -10.23%) are easily today's worst-performing group
- Q4 GDP was robust on the initial reading at 3.3%, well ahead of its 2.0% estimate
Market Outlook
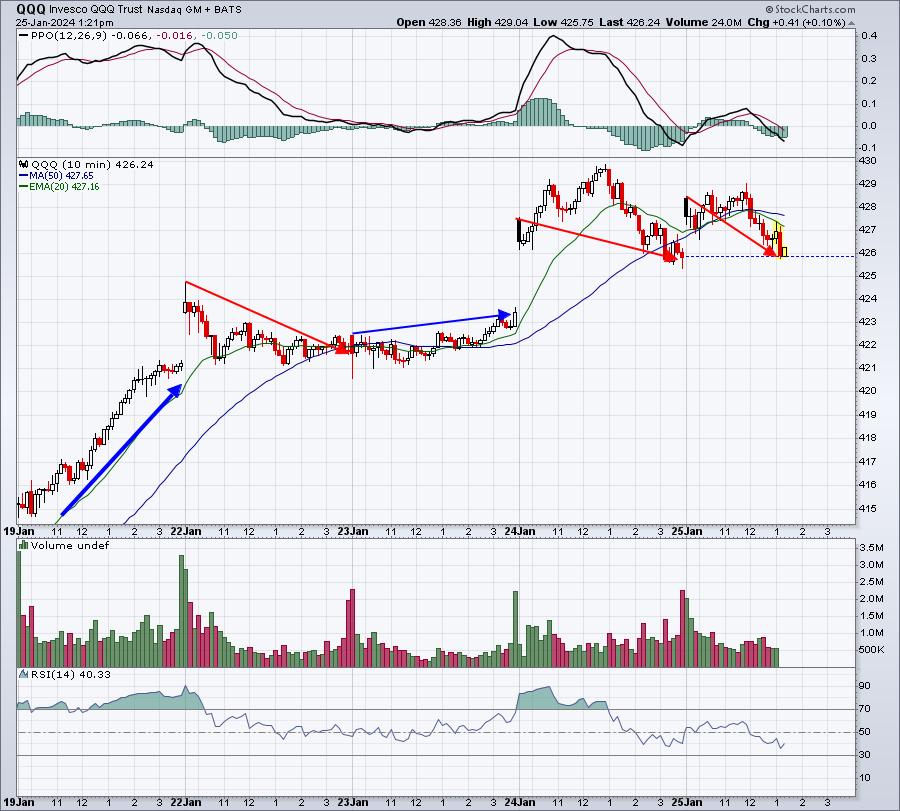
Due to opening gaps higher, this week's market action looks MUCH BETTER than what's actually been taking place. It certainly appears as if we could be setting up for some selling. Morning gaps higher have led to balance of day selling across our major indices, especially the small cap IWM. Check out these intraday charts on the QQQ and IWM:
QQQ:
IWM:
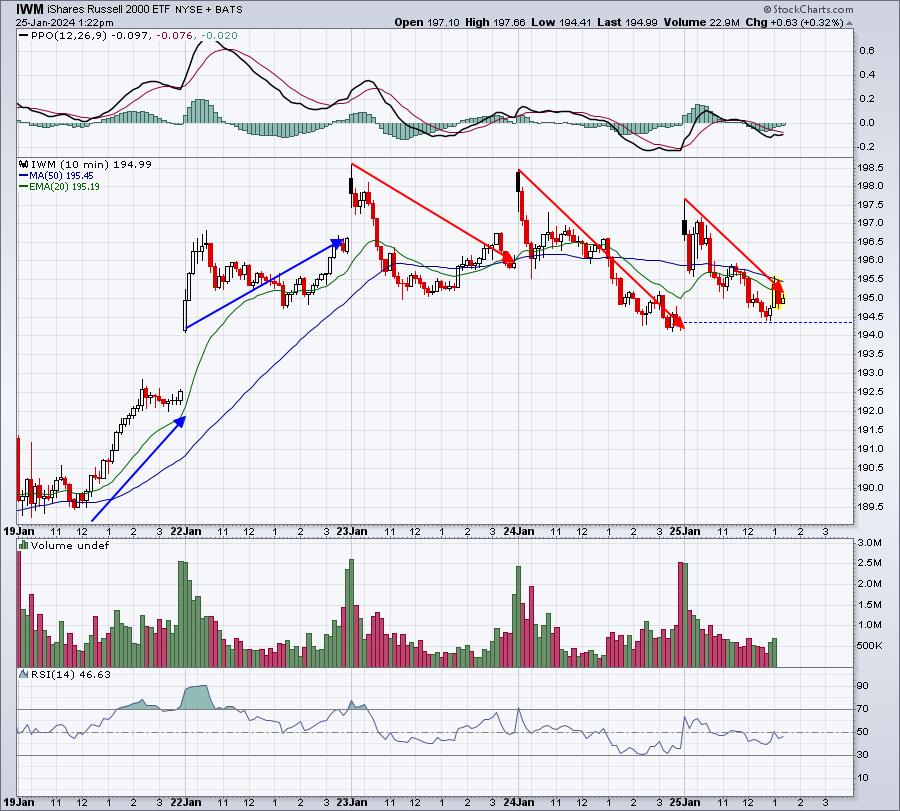
If you recall, it was the gap downs and morning weakness that I called out in June 2022, suggesting potential manipulation that allowed the big Wall Street firms to accumulate stocks at rock bottom prices. The opposite has been taking place this week as strong opens have led to selling throughout the day. This type of action starts to look like a top forming. Now, it's only been a few days and the manipulation that I pointed out in 2022 occurred over weeks - even a few months. A strong finish today could begin to offset these short-term worries. But I have to be honest in saying I just don't like the short-term intraday action right now.
Failure to hold rising 20-day EMAs would be the next logical step if, in fact, we see further downside action in the days/weeks ahead.
One other thing I'll add. Semiconductors ($DJUSSC) were strong earlier, but appear to be reversing. There's still some time left in the day, but these stocks have been moving parabolically higher. If they take a meaningful drop from here, the QQQ could be preparing for a short-term drop of anywhere from 3-7%, in my view. Check out the DJUSSC today on a 3-month chart, so you can clearly see the reversal potentially in play:
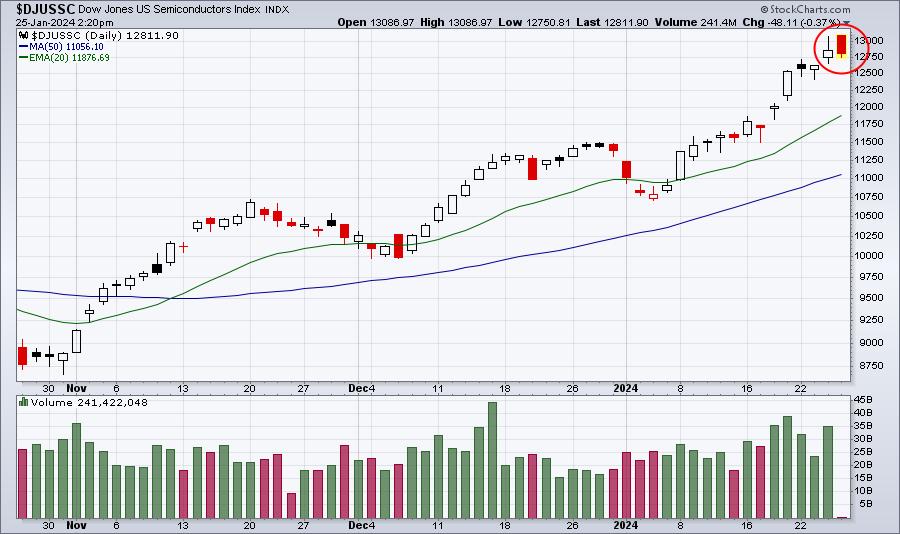
It's not quite a dark cloud cover candle and certainly not to the level of a bearish engulfing candle, but we can clearly see a big drop from the opening bell. I'm watching to see if the selling intensifies in the final hour or two, or if we resume a path higher into the close. If you're trading a number of semiconductor stocks, you might want to watch to see how we close today.
Sector/Industry Focus
Automobiles ($DJUSAU) are heavily influenced by the direction of Tesla, Inc. (TSLA). But the chart on the DJUSAU hasn't been right technically for a long, long time. And now we know why. The TSLA news hit. They missed their revenue estimate. They missed their EPS estimate. Then they talked about a slower growth rate ahead. This is the triple whammy for a growth stock and TSLA has a cult following. It's been giving us warning signs in its price action over the past several weeks, while the overall market kept pushing higher. Another warning sign hit this morning when TSLA opened beneath its key price support. For me, that's usually a sign that things will get worse before they get better. Check out both the auto chart and the TSLA chart:
Automobiles ($DJUSAU):
TSLA:
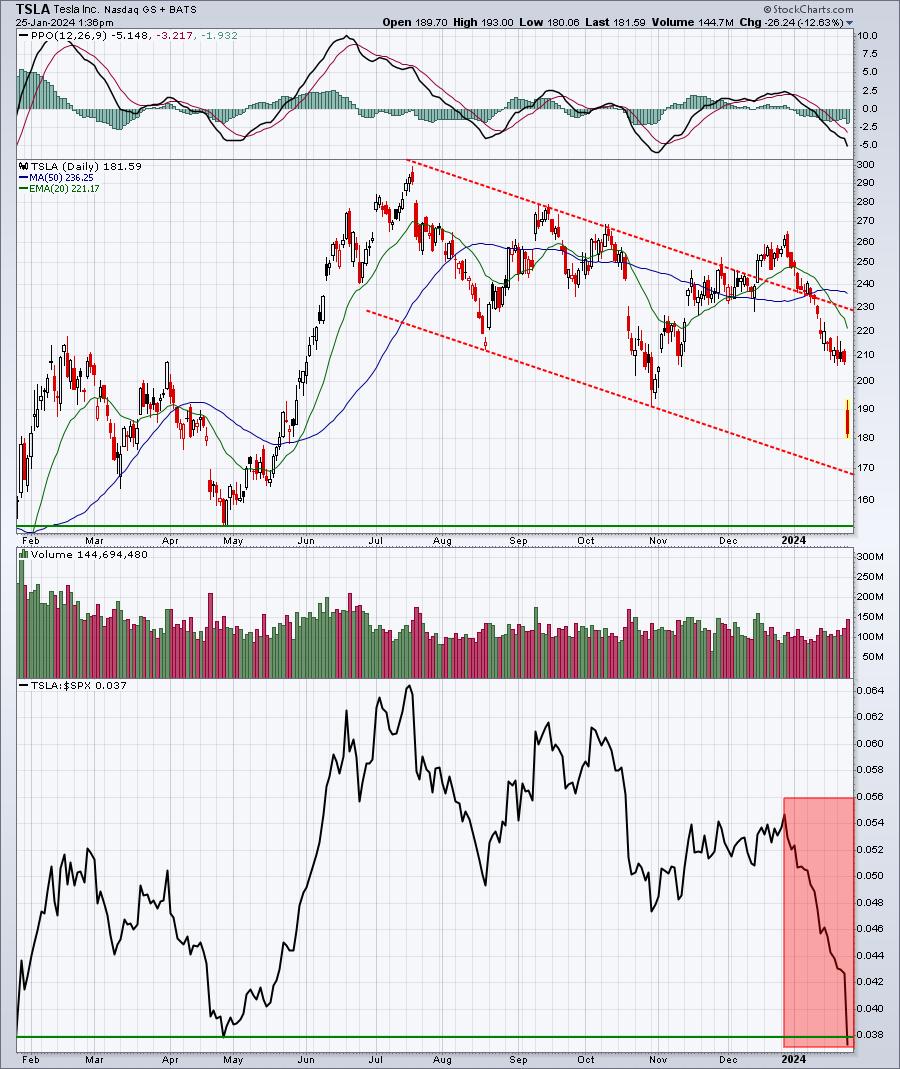
We always discuss investing in leading stocks in leading industry groups. While a bullish argument could have been made for TSLA a month or so ago, it's difficult to make bullish arguments now. Growth stocks like TSLA have their foundations torn apart when they talk about "slower growth rates". Missing estimates and reducing future growth rates nearly always require immediate re-valuations and this appears to be exactly what's happening to TSLA today (and over the prior several weeks).
ChartLists/Strategies
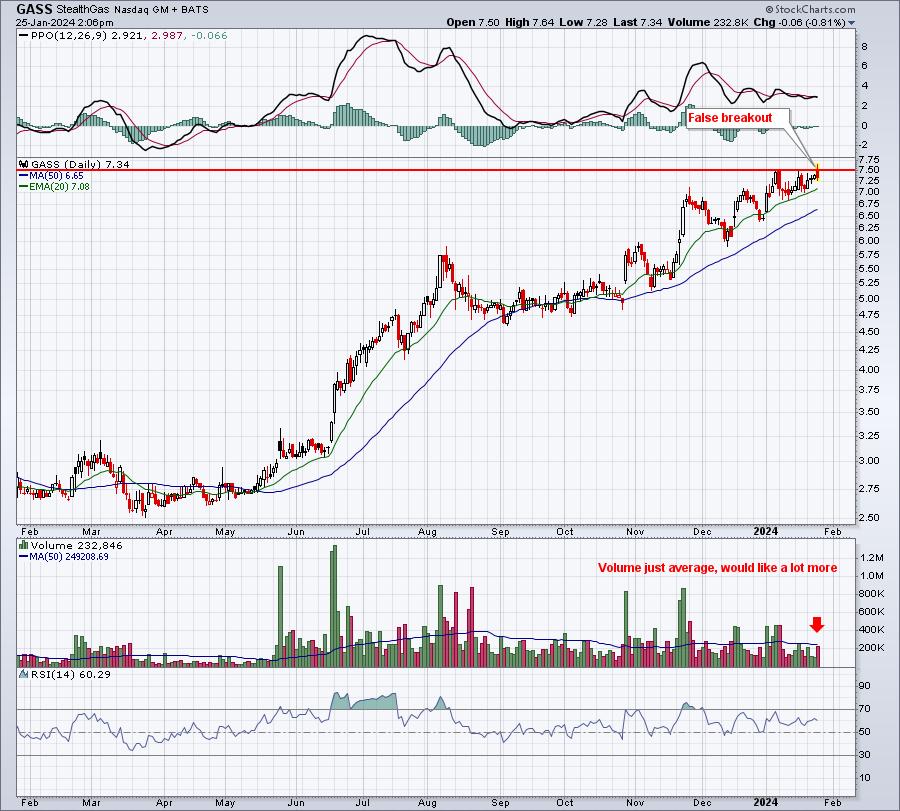
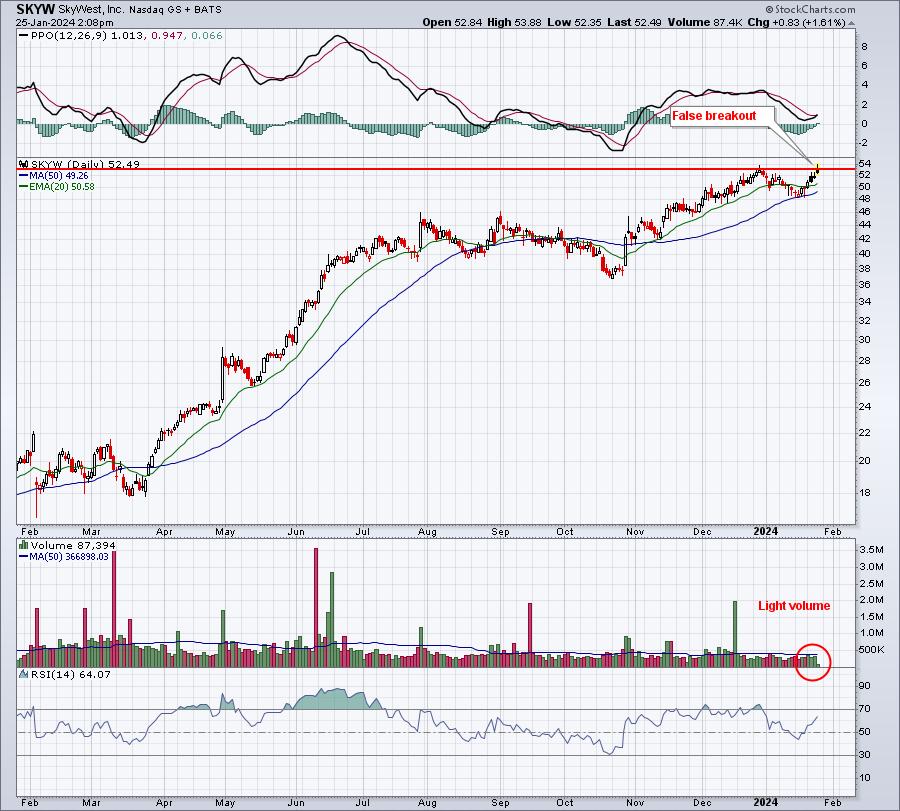
Here are 3 stocks (not necessarily on our ChartLists) that hit 52-week highs, but haven't confirmed a closing breakout:
GASS:
SKYW:
CTSH:
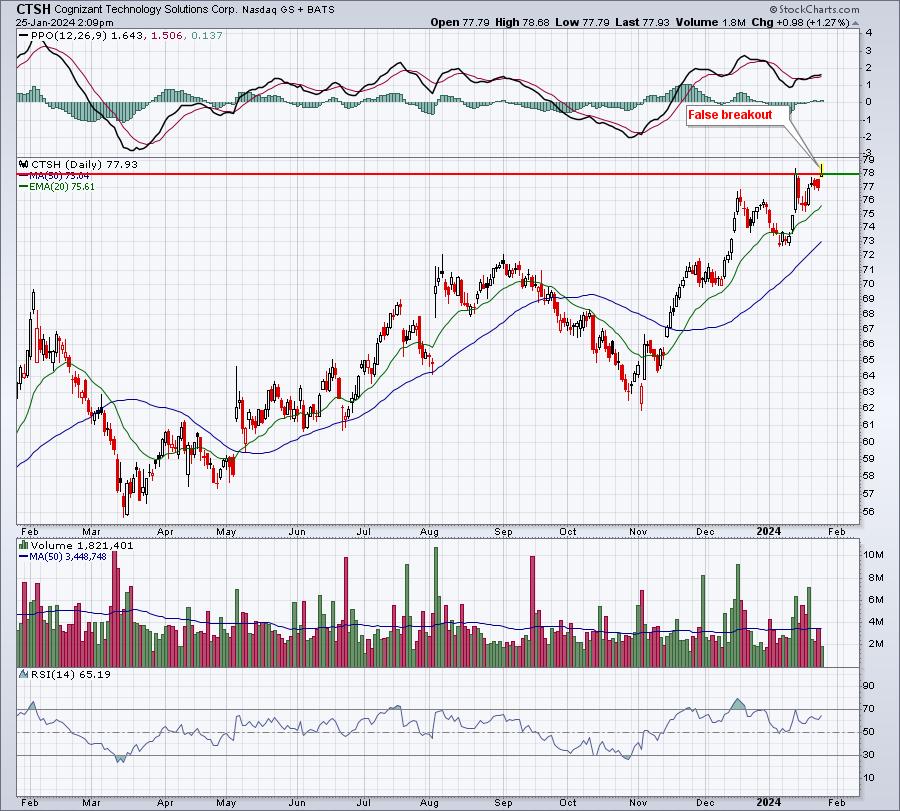
Things could change into today's close and perhaps one or more of the above do make closing breakouts. But if these stocks finish where they are right now, I would not be expecting further strength tomorrow. I don't like long tails (intraday highs) to the upside and failures by the close.
I'm also not liking many reversing candles that are forming today. Be careful on these short-term "attempted" breakouts and failures.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, January 25:
V, INTC, TMUS, CMCSA, UNP, NEE, MMC, BX, KLAC, SHW, NOC, AJG, HUM, COF, VLO, LHX, DOW, XEL, FICO, WY, MBLY, NOK, WDC, LUV, MKC, AAL, ORI, EXP, CFR, OLN, MUR, ALK, CNX, XRX, NTCT
Friday, January 26:
AXP, CL, NSC, BAH, ALV, GNTX, BMI
Economic Reports
Q4 GDP (initial reading): 3.3% (actual) vs. 2.0% (estimate)
Q4 PCE - annual rate: 2.8% (actual) vs. 2.5% (estimate)
Initial jobless claims: 214,000 (actual) vs. 200,000 (estimate)
December durable goods: +0.0% (actual) vs. +1.0% (estimate)
December durable goods ex-transports: +0.6% (actual) vs. +0.2% (estimate)
December new home sales: 664,000 (actual) vs. 650,000 (estimate)
Happy trading!
Tom