
EB Daily Market Report - Thursday, February 1, 2024
The January Effect - Revisited
We will be hosting the "January Effect - Revisited" event at 5pm ET today. January provides us clues as to the most likely market direction for the balance of the year. And it's been rather uncanny as to its accuracy. This should be a relatively short event and one I hope you can attend.
Room instructions have been sent out in a separate email and tonight's event will be recorded for those unable to attend LIVE.
Executive Market Summary
- Futures were higher overnight as our major indices attempted to rebound from Wednesday afternoon's selloff
- Leading the charge today has been the NASDAQ 100, gaining roughly 1.2% at last check
- 10 of 11 sectors are higher led, somewhat suspiciously, by consumer staples (XLP, +1.62%) and materials (XLB, +1.57%)
- Energy (XLE, -0.02%) is the only sector in negative territory on the day
- Crude oil's ($WTIC, -2.28%) decline back to $74 per barrel is no doubt weighing on the XLE
- Most commodities are lower today, with gold ($GOLD, +0.20%) and silver ($SILVER, +0.57%) being the primary exceptions
- The 10-year treasury yield ($TNX) has been falling rapidly, tumbling another 10 basis points today to 3.86%
- The bond market is screaming that inflation is no longer an issue (listening Fed Chief Powell?)
- Railroads ($DJUSRR, +3.01%) are breaking out, an important development for transports ($TRAN, +0.56%) and our economy in general
- AAPL, AMZN, and META all report their quarterly earnings results in the next hour or so
Market Outlook
Here's the big question right now. Are we topping, even if just in the near-term, and beginning to roll over? Well, there are a few clues that we can consider. First, we had previously been trending higher on the NASDAQ 100, but the recent breakdown on the hourly chart remains bearish until the following happens:
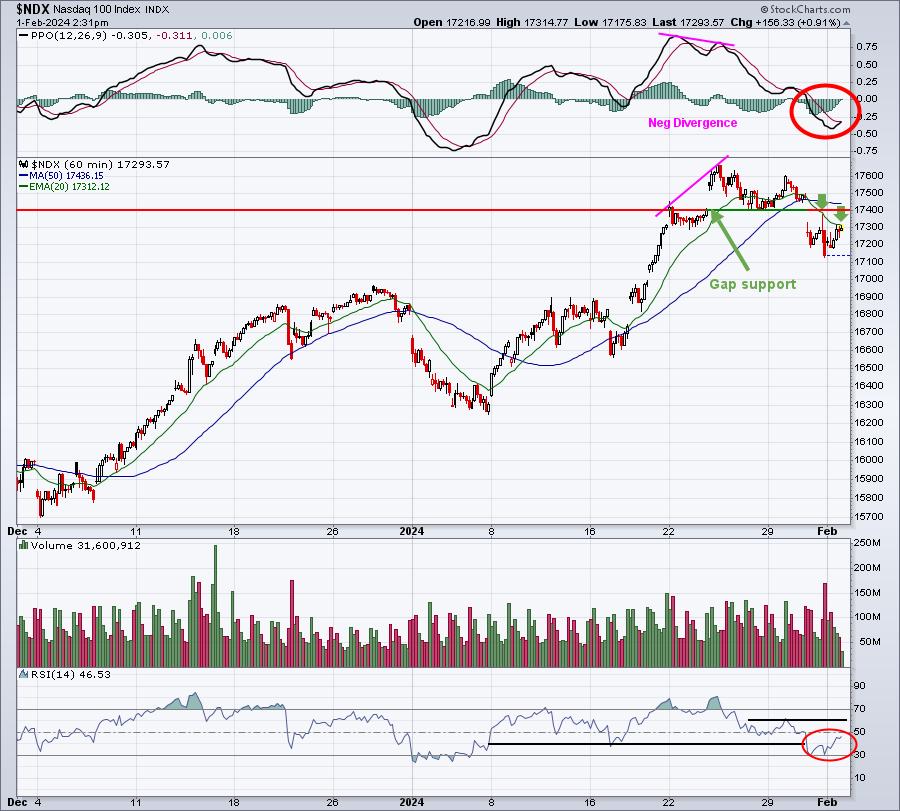
The breakdown beneath gap support, the PPO zero line and RSI 40 all suggest that there's a significant chance that this is the beginning of a consolidation period, or perhaps even the start of a bigger selloff. After all, it's been awhile and yesterday's poor action occurred on very heavy volume. That volume accelerated in the final hour after Fed Chief Powell had spoken.
The NASDAQ 100 does have an opportunity to right the ship as three powerhouses report their quarterly results tonight. First, we have Apple, Inc. (AAPL), which quite honestly doesn't look that great on its chart right now. However, both Amazon.com (AMZN) and Meta Platforms (META) look very strong on both an absolute and relative basis. Because of their heavy weighting in the S&P 500 and NASDAQ 100, these 3 stocks have the capability to lead yet another rally. Of these 3, I really like META this afternoon the most, but AMZN could "deliver the goods" as well.
Sector/Industry Focus
The small caps (IWM) have really struggled since the FOMC announcement yesterday and there are significant technical and fundamental reasons for it. Fundamentally, Fed Chief Powell delivered a blow to the group by saying it's very unlikely that we'll see a fed funds rate cut in March, delaying what will eventually lead to improving net interest margins. There's not much that's more important to banks than the difference between interest income and interest expense. Personally, I believe this is a very short-term blow to banks ($DJUSBK), but the impact on small- to mid-size regional banks (KRE) is being felt much harder. Let's take a quick look at the KRE and establish the key levels to watch:
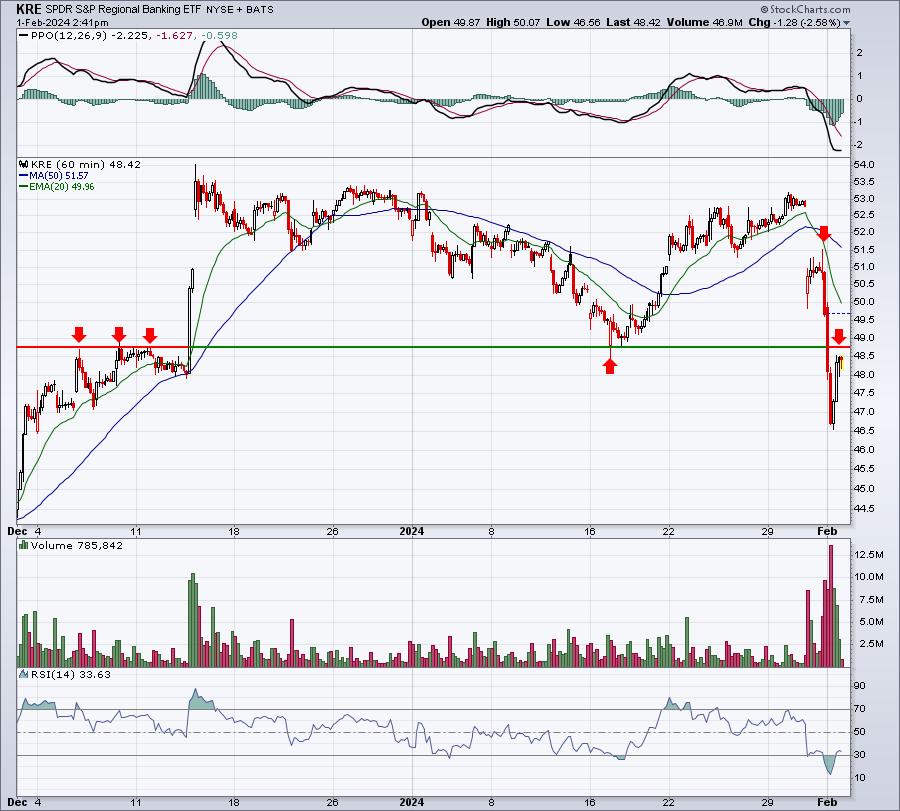
This is the hourly chart, showing that the 48.75 level is now a resistance level that needs to be cleared. And you can see how the volume picked up late yesterday afternoon as the recent advance in the KRE stopped in its tracks and reversed extremely hard.
Let's also look at the KRE daily chart:
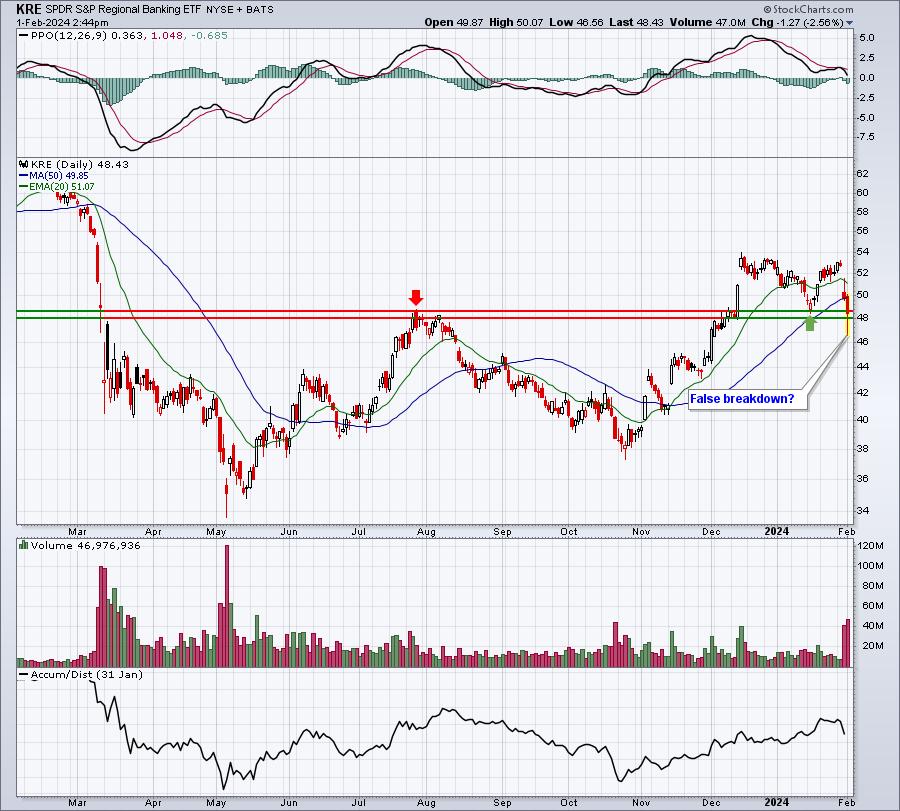
There is little doubt how important the 48.00-48.75 support level is after glancing at this chart. We were WAY BELOW support this morning and we've recovered nearly all of the breakdown. A strong finish this afternoon and false breakdown is the bulls' argument for a short-term recovery. It's important to note that regional banks represent the largest portion (close to 10%) of the IWM. So if we are looking for the small cap IWM to rebound, it'll very likely need to start with the KRE. A strong finish would be bullish for both, while the opposite would be true on an afternoon selloff.
ChartLists/Strategies
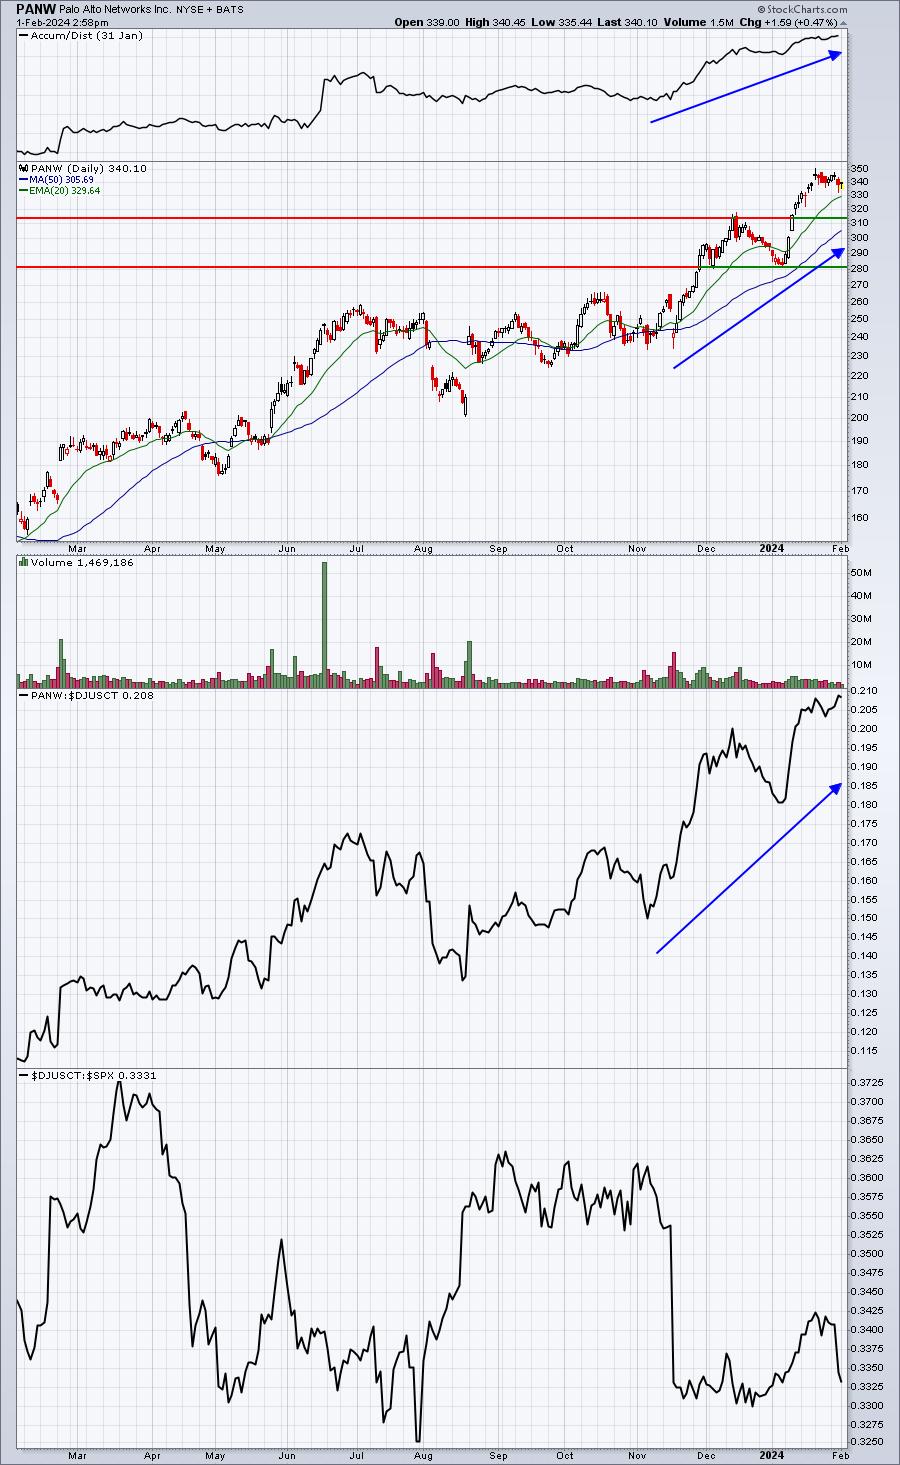
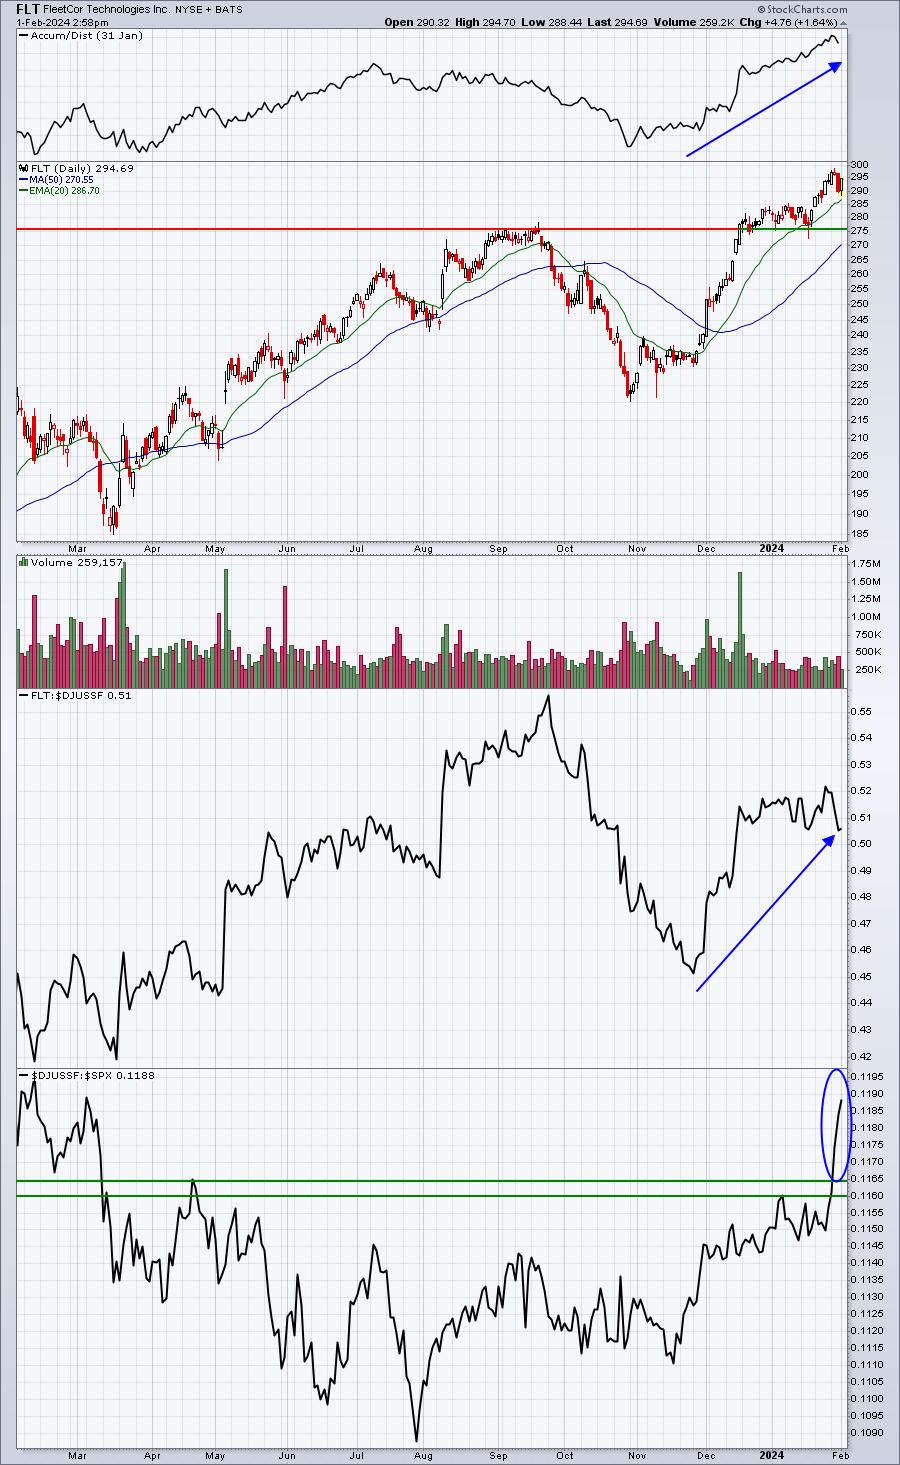
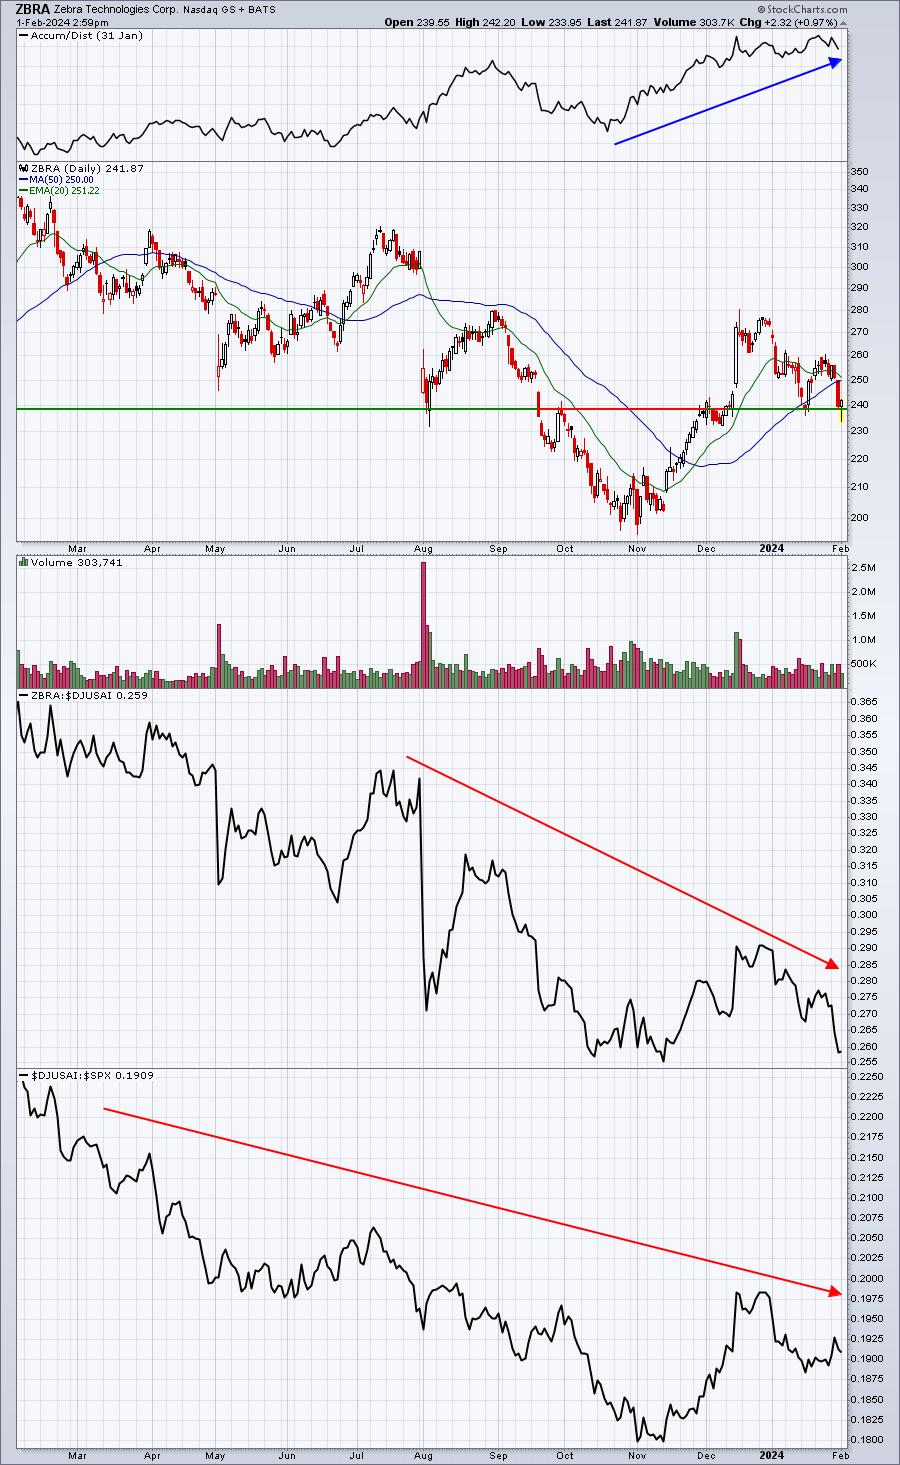
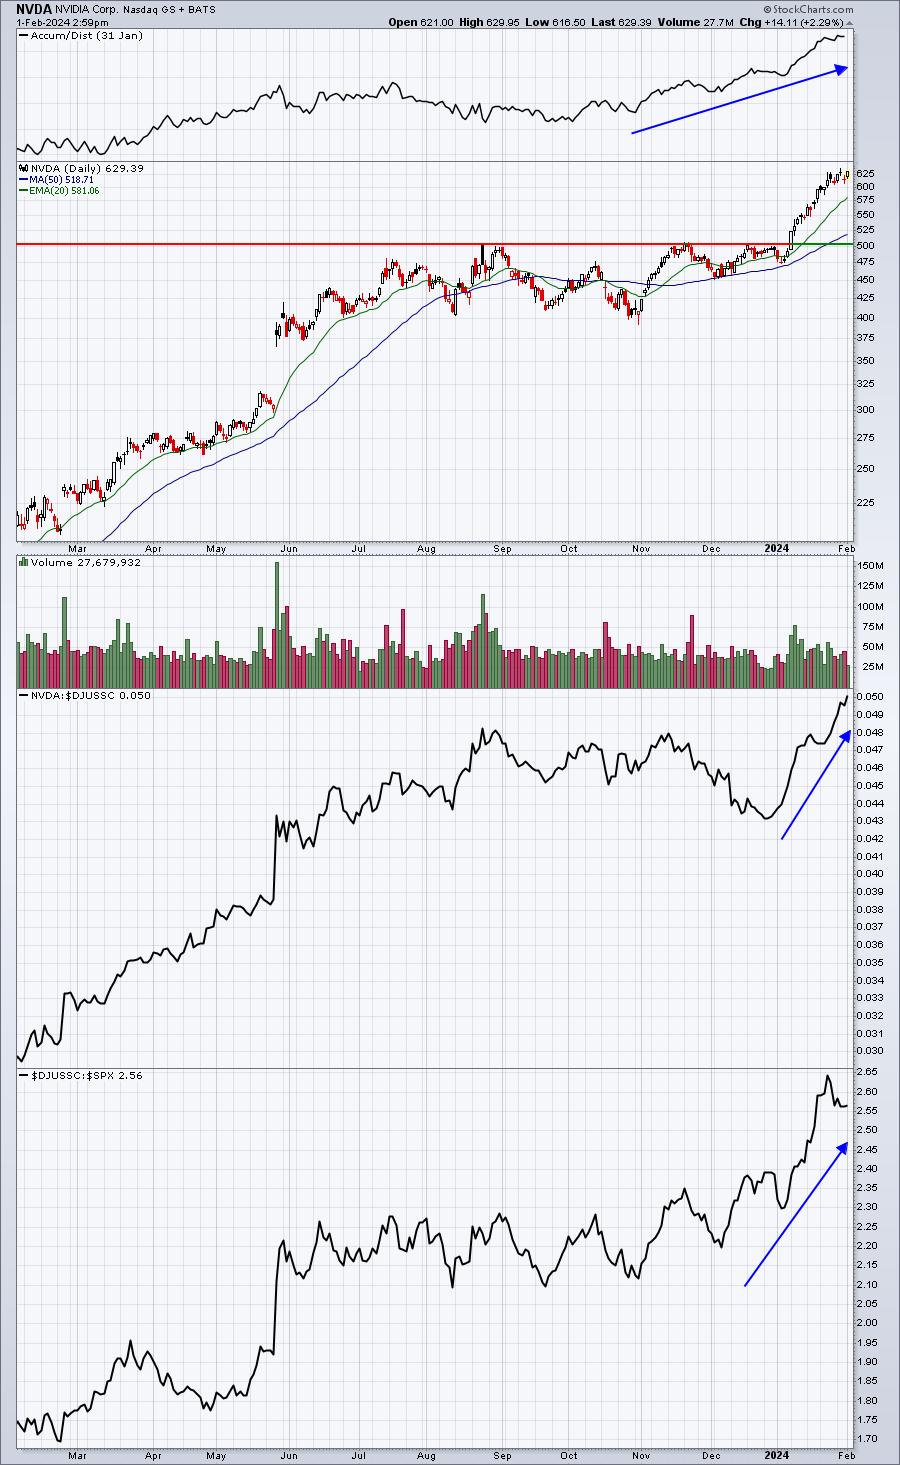
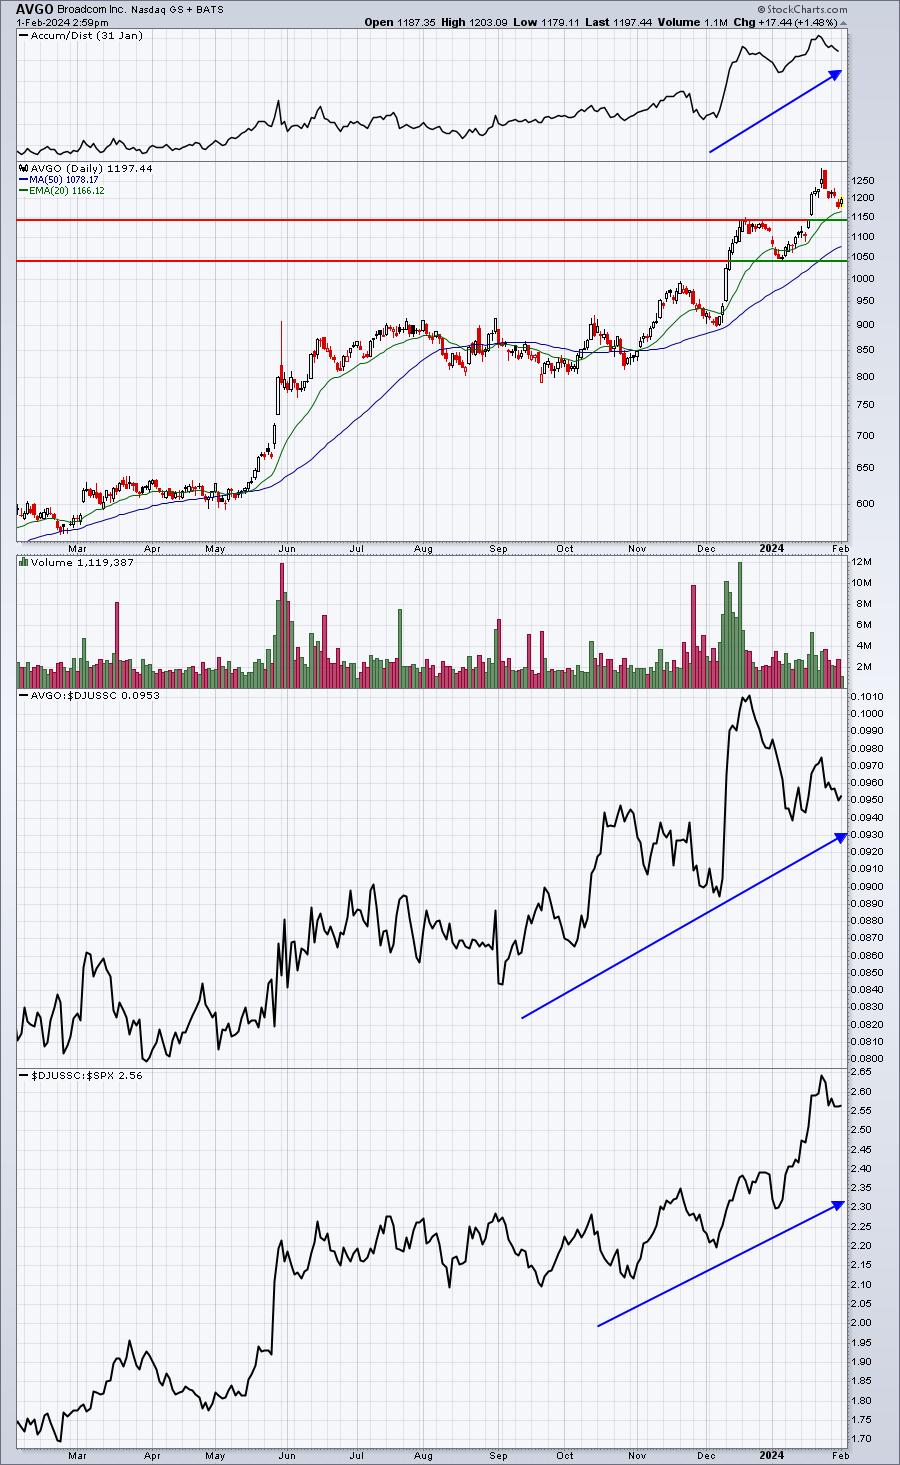
I have completed a MORE fully-annotated Seasonality ChartList (SEASCL) for February to provide more technical analysis of these charts. Personally, I believe the technical view of a chart is much more important than its seasonal periods of strength or weakness. As I look at the 19 stocks on the February SEASCL (the 20th stock, SPLK, was bought several months ago and has shown little movement since, so I deleted it similarly to SGEN in January), here are the best, in my view, based solely on technical analysis:
PANW:
FLT:
ZBRA:
NVDA:
AVGO:
MELI:
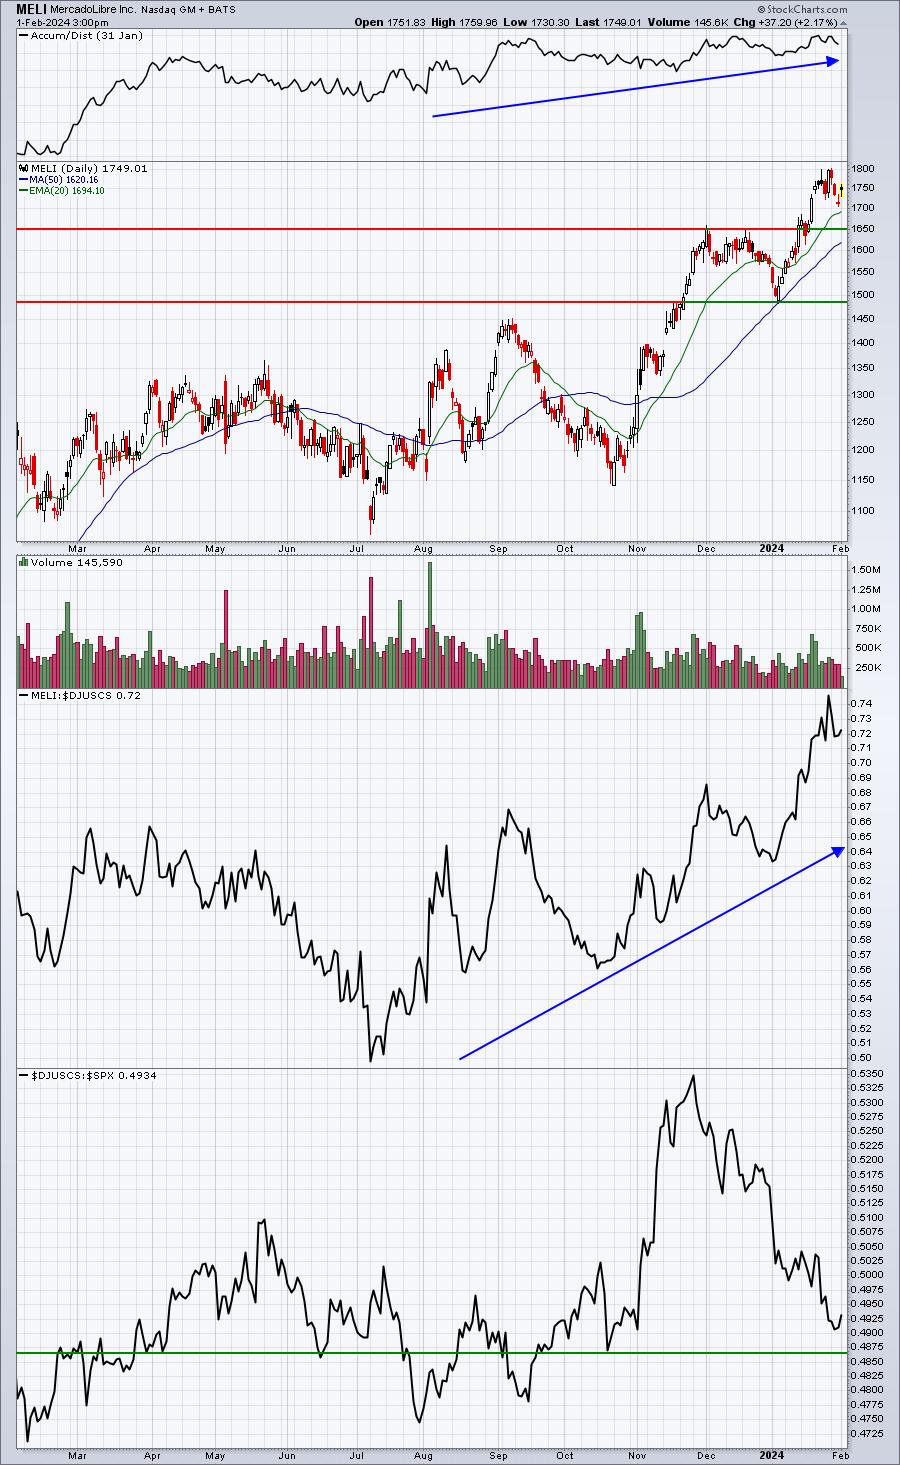
ZBRA doesn't look as strong as the other 5, but ZBRA is potentially printing a hammer at price support that could lead to a strong February ahead. It'll be interesting to see how these 6 stocks perform relative to the other 13.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, February 1:
AAPL, AMZN, META, MRK, SHEL, HON, SNY, ETN, ITW, MO, BDX, TEAM, PH, EPD, TT, ING, MCHP, TAK, RCL, CAH, HIG, WEC, RCI, TSCO, BR, DOV, ASX, DECK, SIRI, LPLA, CLX, BALL, HOLX, CMS, GEN, BIP, SWK, DGX, RVTY, IP, OTEX, TECH, RGA, X, WRK, HII, CPT, EMN, SKX, HLI, DLB, ENSG, MTSI, ATKR, FCFS, JHG, KEX, LAZ, PFSI, KMPR, COUR, HUBG, SKYW, VIAV, PTON, OCSL, SBH, WNC
Friday, February 2:
XOM, ABBV, CVX, REGN, BMY, CI, AON, CHTR, MFG, GWW, IMO, LYB, CHD, CBOE, SAIA, TWST
Economic Reports
Initial jobless claims: 224,000 (actual) vs. 215,000 (estimate)
Q4 productivity: +3.2% (actual) vs. +2.3% (estimate)
Q4 unit labor costs: +0.5% (actual) vs. +2.1% (estimate)
January PMI manufacturing: 50.7 (actual) vs. 50.3 (estimate)
January ISM manufacturing: 49.1 mil (actual) vs. 47.4 mil (estimate)
December construction spending: +0.9% (actual) vs. +0.5% (estimate)
Happy trading!
Tom