
EB Daily Market Report - Thursday, February 8, 2024
Executive Market Summary
- Futures were fairly flat overnight and our major indices opened rather flat
- Intraday, we've seen some money rotate into small caps (IWM, +1.52%) and mid caps (MDY, +0.88%) as the S&P 500 challenges key psychological resistance at 5000
- Energy (XLE, +1.30%) and real estate (XLRE, +0.62%) are our strongest sectors today, helping to explain why the NASDAQ 100 (QQQ, +0.23%) has been quiet on a relative basis
- Clothing & accessories ($DJUSCF, +4.73%) is having a very strong session, led by Polo Ralph Lauren (RL, +17.53%) and Tapestry (TPR, +7.52%) after both reported strong quarterly earnings
- The 10-year treasury yield ($TNX) is up 6 basis points to 4.16%, once again testing the upper end of its recent trading range
- Crude oil's ($WTIC, +3.55%) surge to $76.50 is helping lift the XLE
- Bitcoin ($BTCUSD, +2.85%) is up 1257.55, moving back through 45000 in the process
- Walt Disney (DIS, +11.37%) easily surpassed quarterly estimates and it's leading the the Dow Jones higher
Market Outlook
The historical pattern over the next week remains quite strong. Here are the annualized returns for each of the following indices through next Thursday, February 15th:
- S&P 500 (since 1950): +14.59%
- NASDAQ Composite (since 1971): +36.70%
- Russell 2000 (since 1987): +45.00%
While the current rally always seems to remain overbought and we certainly have signs of slowing momentum, history tells us not to bet against this rally continuing into and perhaps through next Thursday. Next Friday is somewhat bearish for the S&P 500 and NASDAQ, but remains bullish for the Russell 2000.
Sector/Industry Focus
Let's check in on the Dow Jones U.S. Clothing & Accessories Index ($DJUSCF):
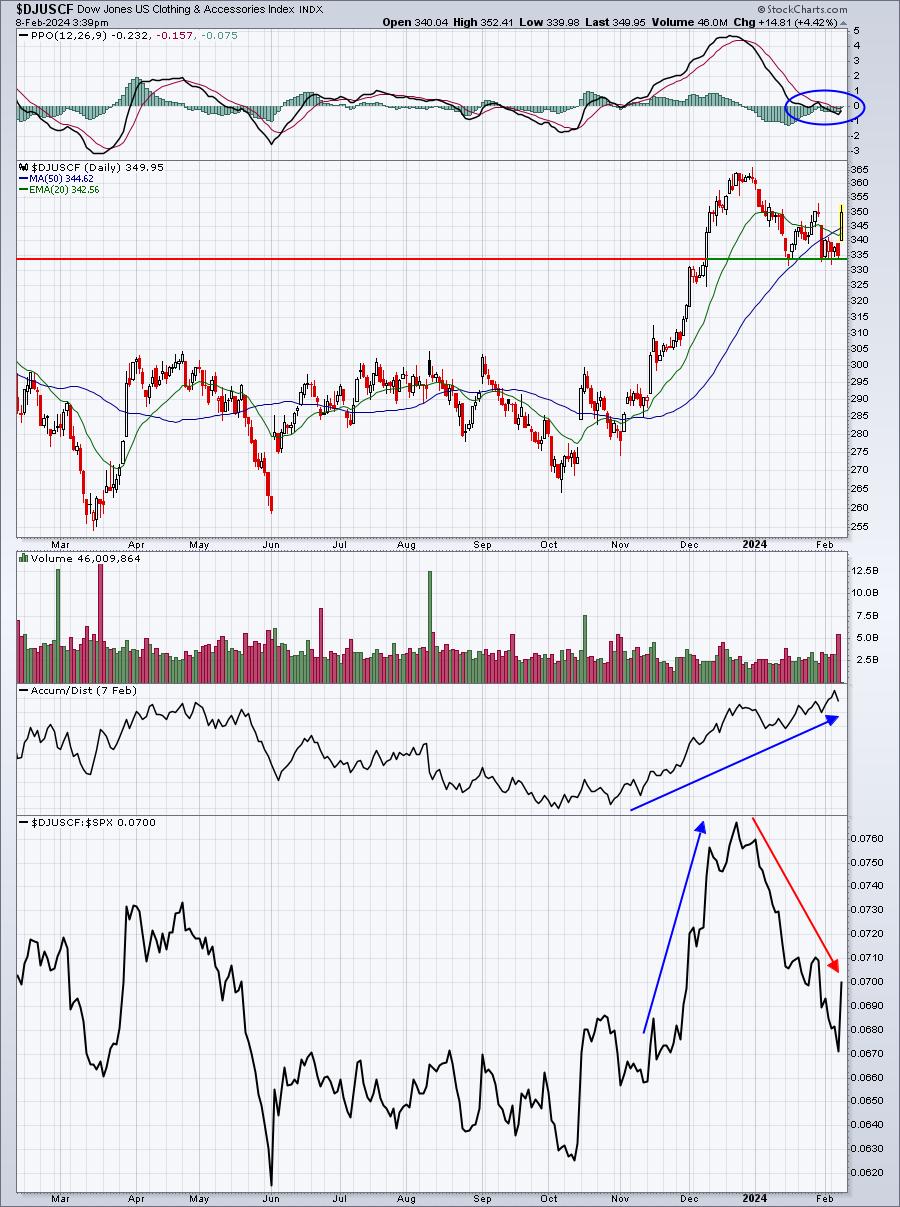
I like the attempted breakout on the DJUSCF, but just keep in mind this group usually only provides us short-term trades. We had tremendous relative strength to close out 2023, but the relative strength in 2024 has been the exact opposite. The AD line has remained strong, suggesting that the big Wall Street firms have likely been supporting this group, even while the price action has been quite weak. The PPO is at its centerline support area, so a breakout here above 350-352 could easily result in further gains tomorrow and into next week.
ChartLists/Strategies
Here was one chart that looked interesting to me after recent strong earnings results:
MOH:
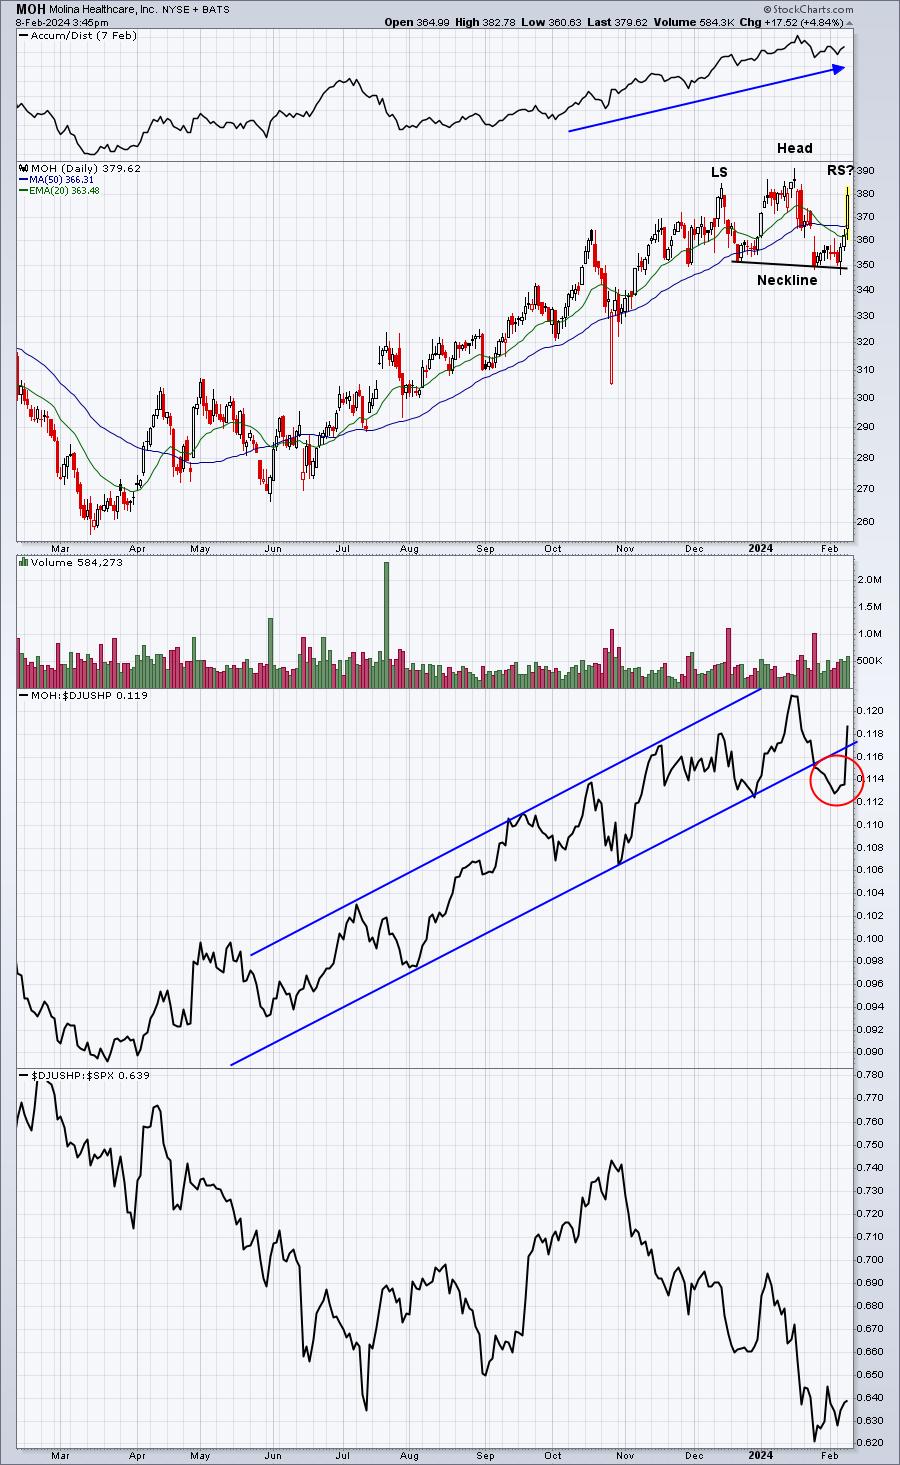
Head & shoulders topping patterns do not confirm until a breakdown beneath the neckline occurs. But it's at least worth noting that a potential topping pattern is present. The AD line remains strong and MOH could simply break out above recent highs. Doing so would negate the H&S pattern. Failing to reach that recent high, however, keeps this topping pattern in play. MOH is up on solid recent earnings, but will it be enough?
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, February 8:
AZN, SPGI, PM, COP, DUK, ICE, TRI, BN, TDG, APO, MSI, DXCM, HSY, KVUE, ARES, BCE, TTWO, PINS, NET, ZBH, MTD, TROW, ILMN, MT, DTE, EXPE, CCJ, FE, VRSN, BAX, K, DT, SNA, MAS, AFRM, IPG, KIM, BAP, REG, TFII, WMS, ITT, CYBR, RL, TPR, PCTY, THC, TPX, WEX, BILL, BWA, ONTO, MHK, BYD, CPRI, DOCS, HOG, TEX, NSP, POWI, SYNA, LITE, HAE, GTS, UAA, BDC, PBH, LSPD, PI, RAMP, LGF/A, SPB, MWA, SWI, OMCL
Friday, February 9:
PEP, ENB, OWL, FTS, MGA, WPC, PAA, CTLT, COOP, NWL
Economic Reports
Initial jobless claims: 218,000 (actual) vs. 222,000 (estimate)
December wholesale inventories: +0.4% (actual) vs. +0.4% (estimate)
Happy trading!
Tom