
EB Daily Market Report - Tuesday, April 9, 2024
Executive Market Summary
- Futures were slightly higher overnight and our major indices did gap up at the opening bell
- Unfortunately, we saw mostly selling today, until the bond market closed at 3pm ET, at which time we've seen equities rebound
- Crude oil prices ($WTIC, -1.32%) have fallen back to $85 per barrel, but other commodities continue their ascent, including gold ($GOLD, +0.66%) and silver ($SILVER, +1.36%)
- The 10-year treasury yield ($TNX) finished down at 4.36%, heading into a key CPI report, which will be released Wednesday morning before the opening bell
- It's another day of bifurcated action, with small caps (IWM, +0.40%) leading the way
- Defensive groups lead as real estate (XLRE, +1.01%) and utilities (XLU, +0.37%) are at the top of the sector leaderboard
- Financials (XLF, -0.79%) are lagging
- Insurance companies are struggling as full line insurance ($DJUSIF, -2.99%) is today's worst-performing industry group; other insurers are down in sympathy
- Moderna (MRNA, +6.16%) is leading the S&P 500 on today's session, threatening its high since September
Market Outlook
I've spoken a couple times in the past 24 hours about price support on the QQQ. Well, here's one more time:
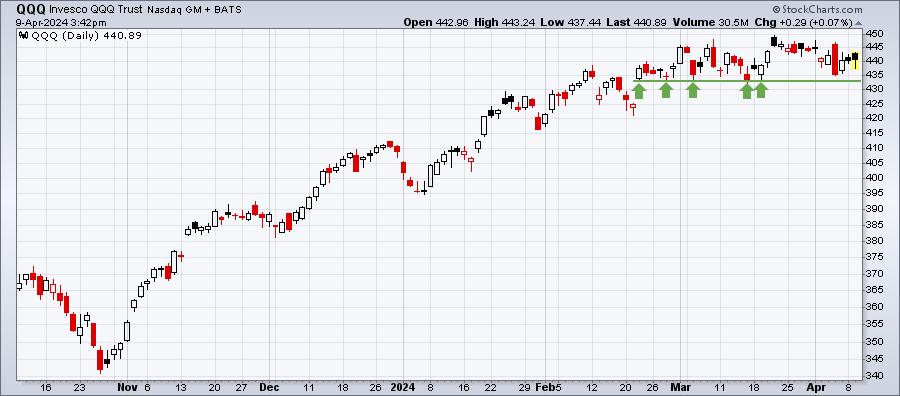
Now keep in mind that short-term price support isn't a "do or die" scenario. It's simply that I wouldn't expect lower prices on the QQQ, unless, or until, we see a close below the 433 level.
Sector/Industry Focus
I posted a chart of the industrial metals ($GYX) in the EB Weekly Market Report yesterday and showed that the correlation between industrial metals prices and the benchmark S&P 500 is actually quite positive, meaning that U.S. equities tend to go higher when industrial prices are rising. It's a sign of strengthening global demand. Today, I'm reposting this chart, but looking at it from a different angle - inflation. Most market participants have very short-term memories and only look at the most recent surge in industrial metals prices from 2020 to 2022 (blue-shaded area), noting that it resulted in surging inflation at both the producer and consumer levels. But I want you to look at the 3 prior surges in industrial metals prices (red-shaded areas). NONE of them resulted in an alarming increase in Core CPI:
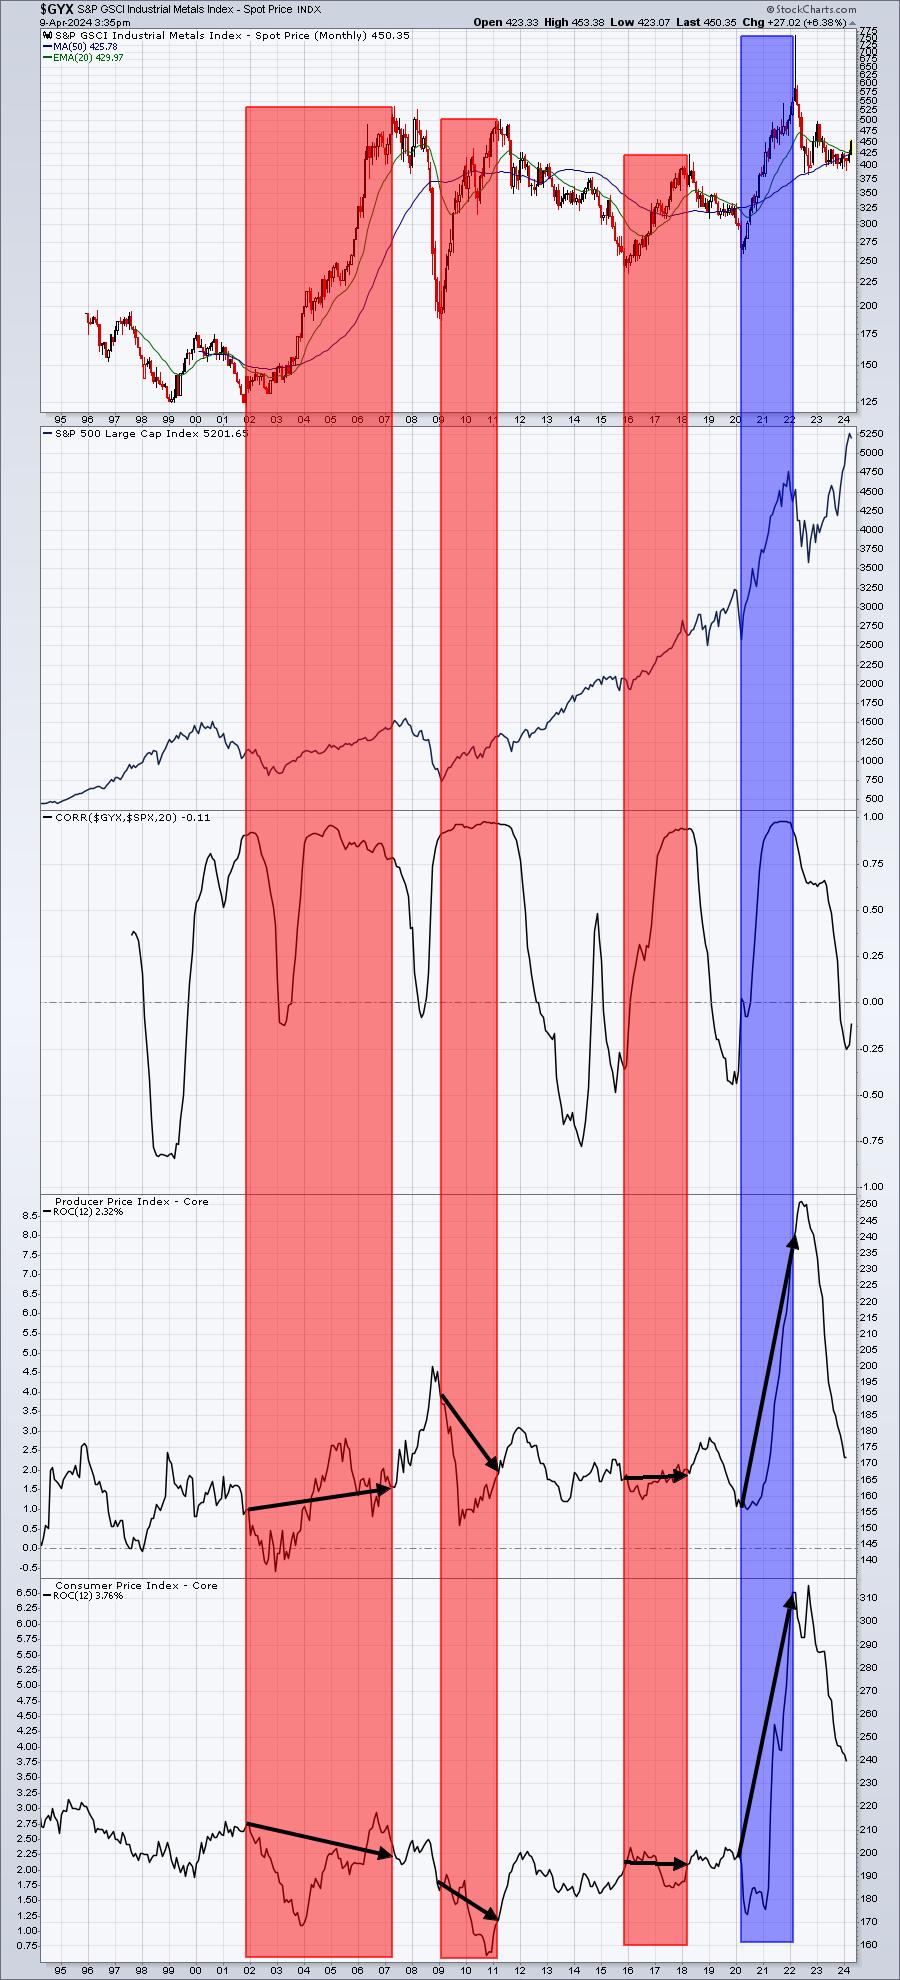
Don't just assume that the recent move higher in industrial metals prices will trigger higher inflation. That is NOT what history tells us.
ChartLists/Strategies
Here are a couple stocks that recently raised guidance and have pulled back to or near what could be very significant support:
SIG:
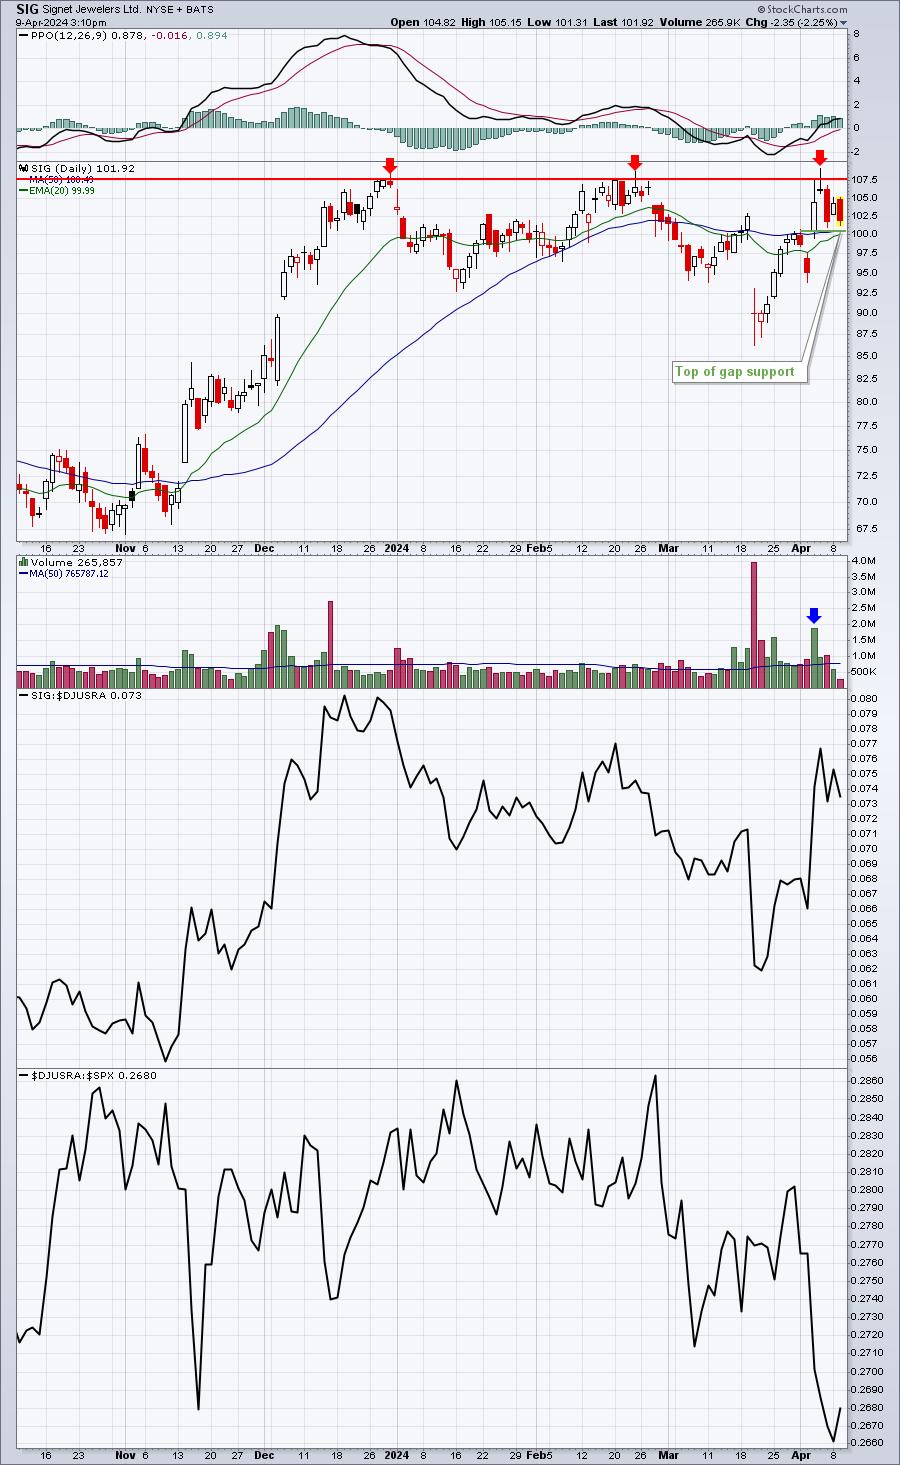
There's been a lot of buying since the big gap down on March 20th. The $20 rally ended last week at key price resistance near 107.50. SIG has since moved back and is approaching a key gap support level, which is almost squarely on both its 20-day EMA and 50-day SMA. I wouldn't be shocked to see a recovery from here, possibly leading to a triple-top breakout.
GPS:
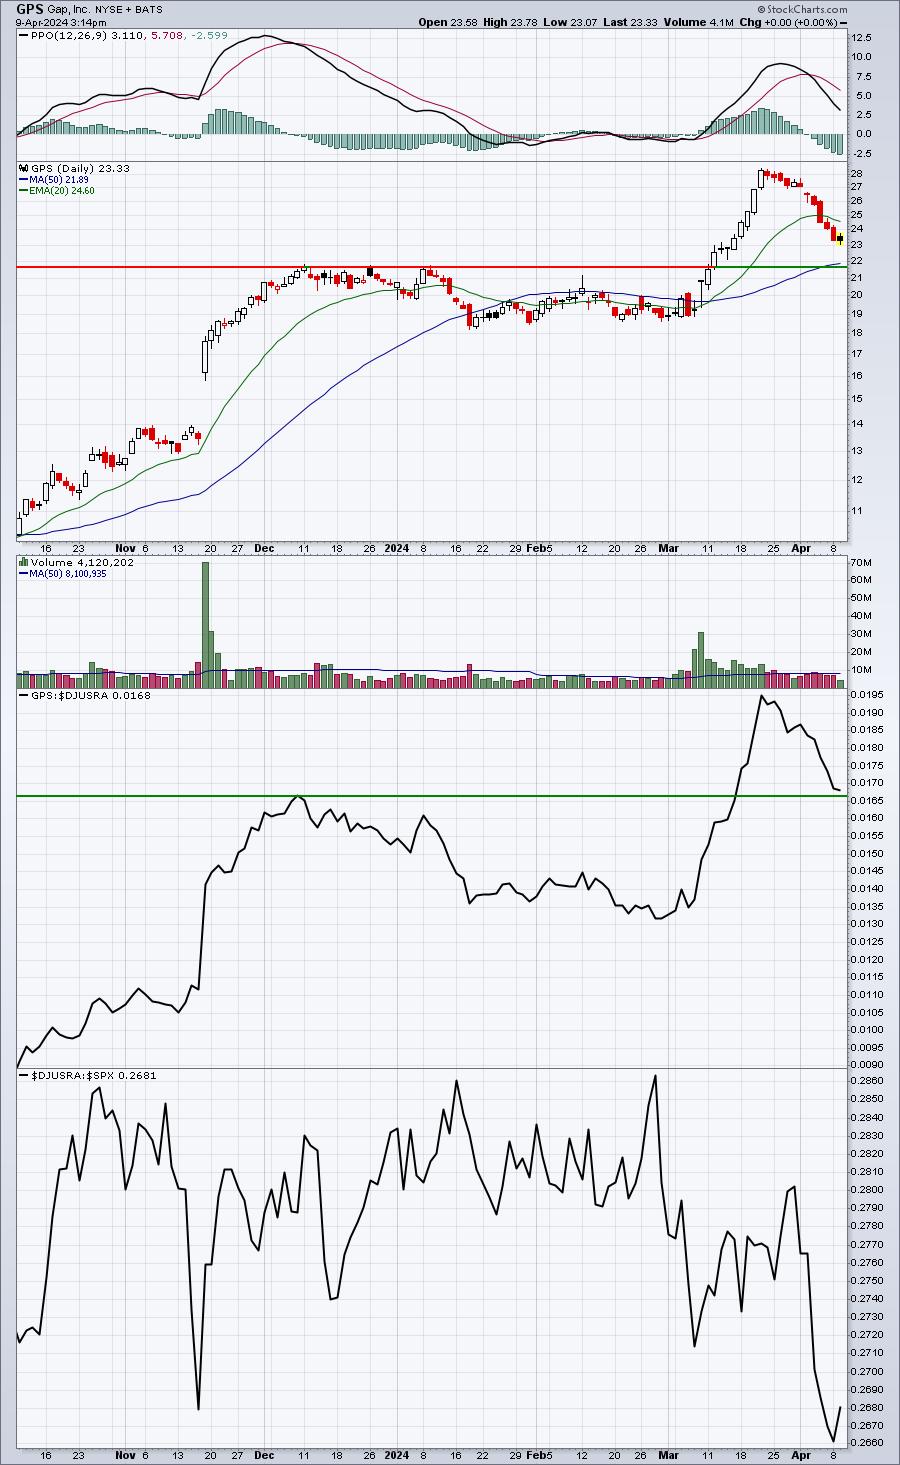
GPS has been a wild ride. After closing above its open for 9 out of 10 days and gaining roughly 50%, GPS topped just above 28. GPS is currently below today's open, which would mark the 11th time in the last 12 days that its close finished beneath its open. Straight up, then straight back down. There has been one distinguishing feature between the uptrend and downtrend, however. Check out the volume. The volume was higher than normal every day during the uptrend and it's been lower than normal nearly every day of the downtrend. When GPS finally reverses this current downtrend, it would appear that the reward-to-risk would be set up rather nicely.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, April 9:
WDFC, NEOG, TLRY, SGH
Wednesday, April 10:
DAL
Economic Reports
None
Happy trading!
Tom