
EB Daily Market Report - Special CPI Report - Wednesday, April 10, 2024
The next 10 days or so will be extremely interesting. This morning, the March CPI report was released and I'll discuss that a bit in a minute. Tomorrow morning, we'll get the latest March PPI report and, on Friday, earnings season will kick off with notable large banks like JP Morgan (JPM), Citigroup (C), and Wells Fargo (WFC) lining up to deliver their latest quarterly results. Throw in next Friday's April monthly option expiry and we're certainly set up to see significant volatility.
Speaking of volatility, let's look at the Volatility Index ($VIX), because new highs in the VIX can translate into selling acceleration. Here's what the VIX looks like right now vs. recent price lows on the S&P 500:
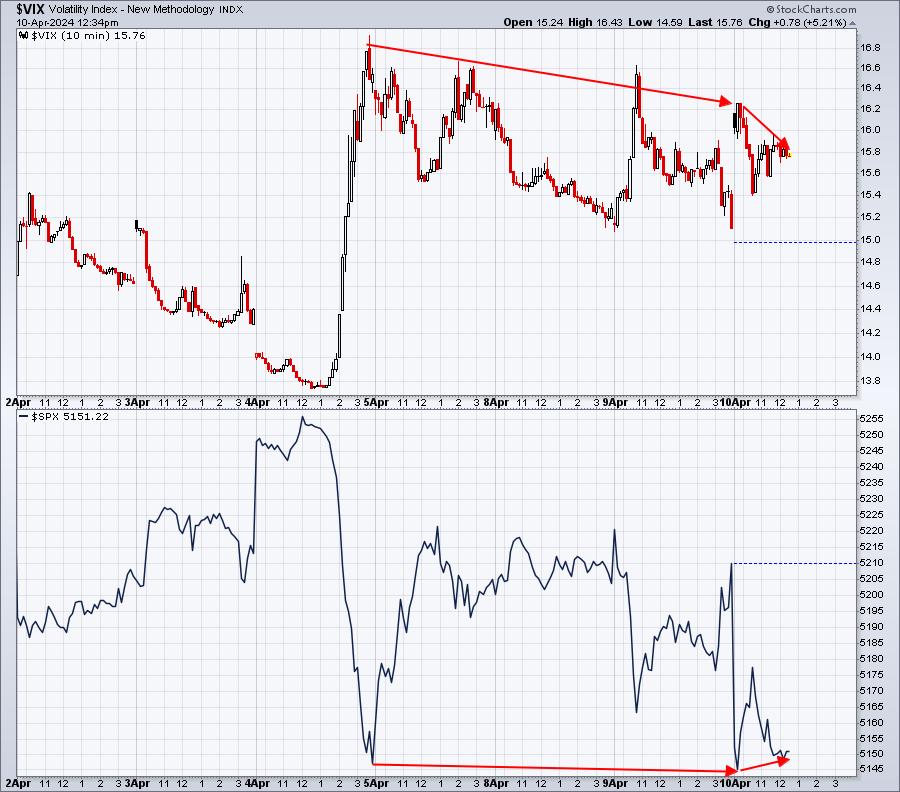
This may not be worthwhile at all, but I do find it somewhat surprising. This morning, the S&P 500 took out the low from last Thursday, the day that Minneapolis Fed President Neel Kashkari said at 2pm ET that we might not see any rate cuts in 2024, jarring U.S. equities for the next two hours. The VIX quickly spiked to near 17 on the FedSpeak of one non-voting member. This morning, we received the news we didn't want to hear (at least the bulls didn't want to hear it), as March CPI was reported higher than expected. Maybe I'm crazy, but I'd be much more concerned about ACTUAL economic data suggesting the potential of higher inflation and a delay in rate cuts than I would be the FedSpeak that we've all grown accustomed to hearing the past few years.
Yet look at the VIX. The VIX was much higher on Thursday's Fed (Kashkari) comments. Today, the S&P 500 fell a couple points lower than Thursday's low, but the VIX never got close to 17. Also, as the S&P 500 approaches its morning low for another breakdown or double bottom, the VIX has settled down even further. In my opinion, part of this behavior can be attributed simply to the relief factor. March CPI is behind us.
Listen, we're only 4 hours from the higher inflation news being reported. We need to watch a number of things and this dialogue will extend into the next several days, possibly a few weeks. It's entirely possible that we fall further - today or down the road. But it will be VERY important to see how various areas perform relative to the benchmark, because that will tell us the REAL story. Where is the money going? Does Wall Street begin to hibernate from growth stocks in preparation of a much larger inflation-related drop?
Here's today's Sector Summary, highlighting which areas are outperforming and which are underperforming. Keep in mind the S&P 500 is down 1.10% right now:
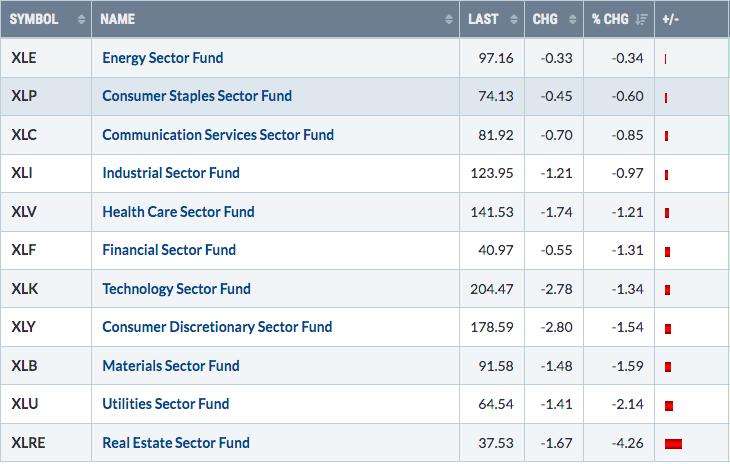
All 11 sectors are lower, but the weakness is mostly concentrated in the value-oriented sectors like real estate (XLRE), utilities (XLU), and materials (XLB). This can certainly change, but the initial reaction isn't one that screams to me to GET OUT. Instead, it's saying to STAY THE COURSE.
If I look at the 5 aggressive sectors (XLK, XLY, XLC, XLI, and XLF) over the past few days to see if money has started to rotate away from aggressive areas, this is what I see:
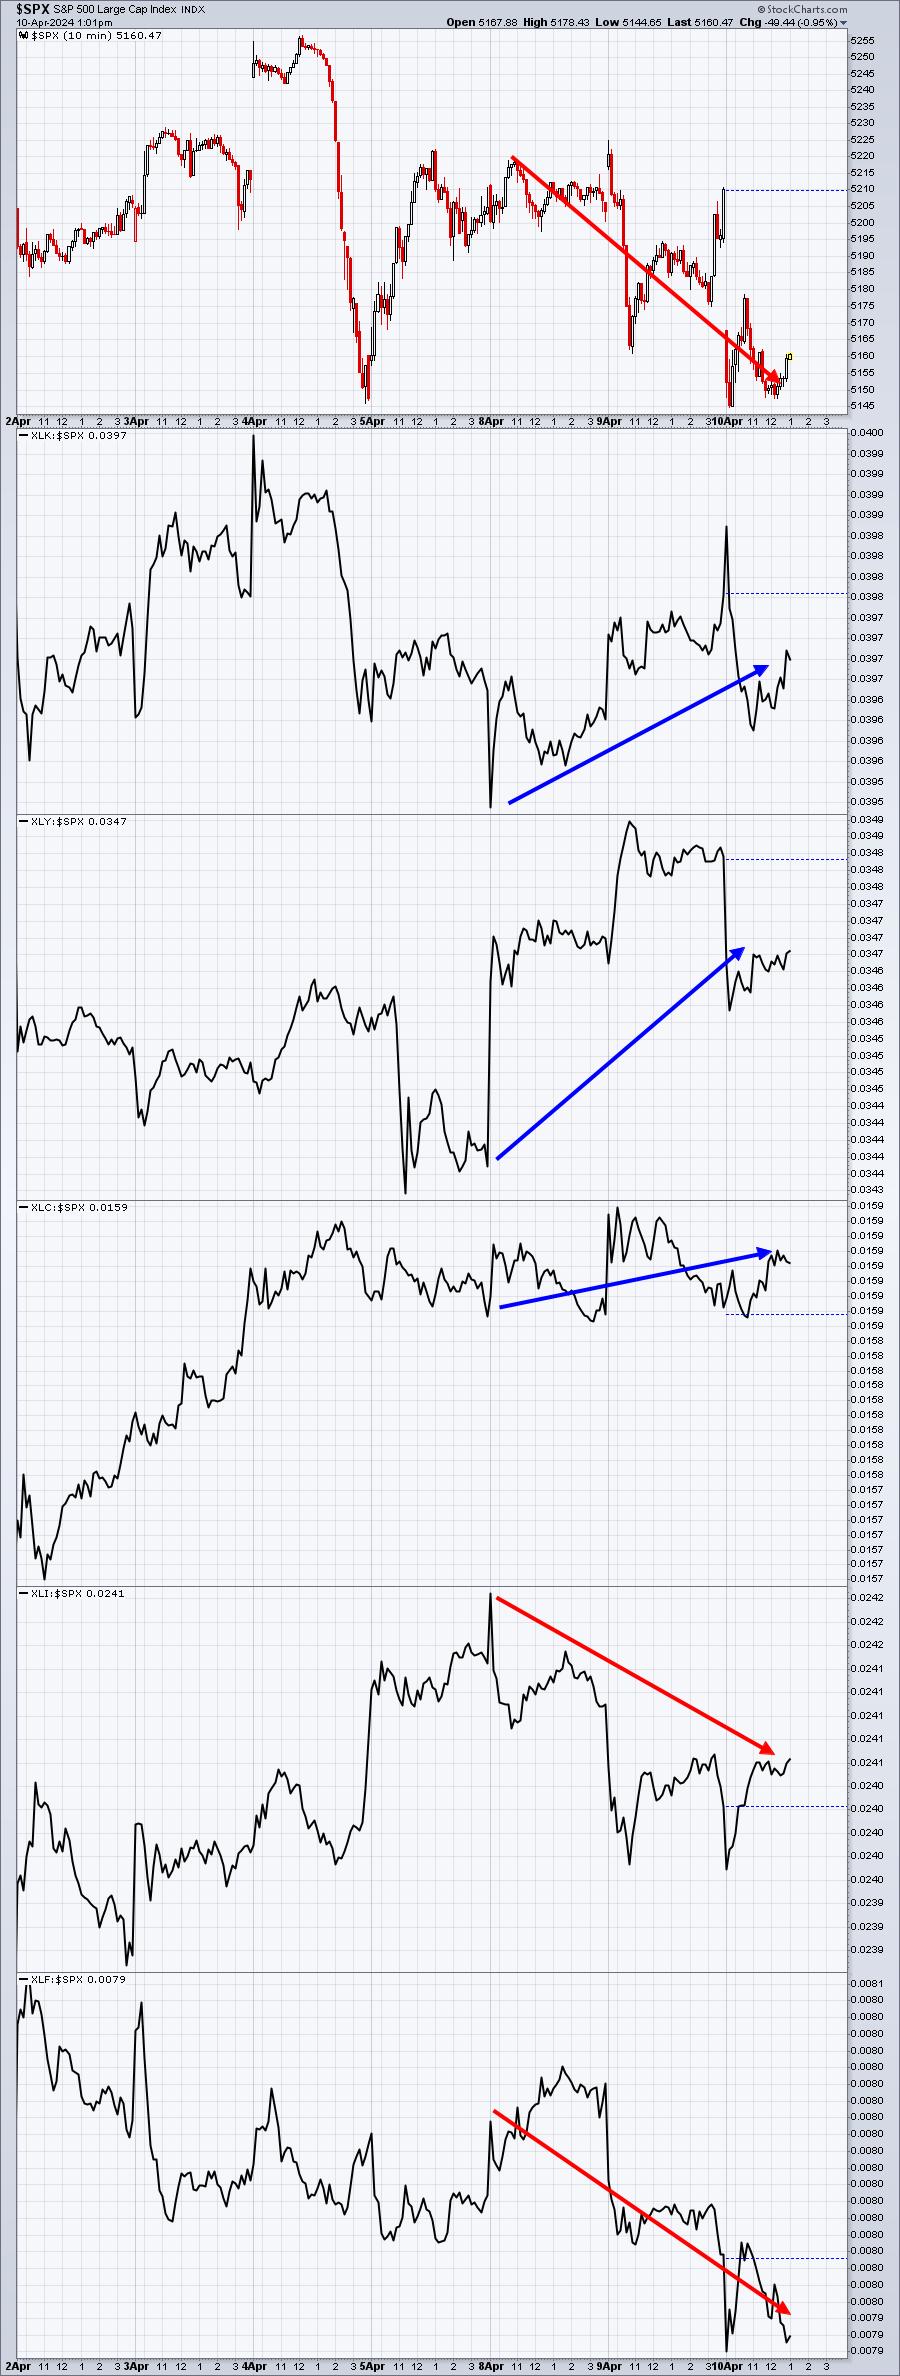
The growth portion of our aggressive sectors - XLK, XLY, and XLC - are trending HIGHER, not lower. The value portion - XLI and XLF - are weakening. This is NOT how the stock market rotates when inflation expectations are raised.
I don't want to make any major conclusions based on a few hours of trading, or even the last few days or a week. We'll get more information over the next several days and we'll adjust to that information. But, to me, the early signs point to this being a very short-term issue.
Let's see how we finish this afternoon and go from there.
Happy trading!
Tom