
EB Daily Market Report - Thursday, May 30, 2024
Spring Special
Our Spring Special is still running and it's our BEST deal of the year. It ends this Sunday, June 2nd at midnight, so be sure to take full advantage quickly! For more details, CLICK HERE.
Executive Market Summary
- Futures were lower overnight and this morning on most of our major indices; small caps (IWM) were an outlier as they benefited from lower treasury yields
- The 10-year treasury yield ($TNX) is down over 7 basis points today after weak economic news
- April pending home sales fell 7.7% unexpectedly, though home construction stocks ($DJUSHB, +1.94%) have held up well
- Q1 GDP was revised lower and below consensus at 1.3%, while the annual PCE rate came in at 2.0%, well below the prior 2.5% level and below consensus - potentially giving reason for the Fed to consider lowering rates
- Commodities are lower just about across the board today with crude oil back below $78 per barrel
- Copper ($COPPER, -2.87%) has fallen significantly from its recent high of 5.20 to today's price of 4.66; it's been quite a drop in less than two weeks
- Software ($DJUSSW, -3.61%) is down significantly after Salesforce.com (CRM, -19.51%) missed its revenue estimate, weighing on technology (XLK, -1.58%), today's worst-performing sector
- 9 sectors are higher, led by real estate (XLRE, +1.23%), but weakness in both technology and communication services (XLC, -0.46%) is holding back our major indices.
- HP Inc.'s (HPQ, +20.13%) solid quarterly results have it at the top of the S&P 500 leaderboard, while CRM is the S&P 500's worst performer
Market Outlook
I don't look for leadership from banks ($DJUSBK) to sustain a secular bull market advance, but I like to see banks participate to the upside. They're the lifeblood of our economic system and healthy banks typically lead to strong economic periods and a rising stock market.
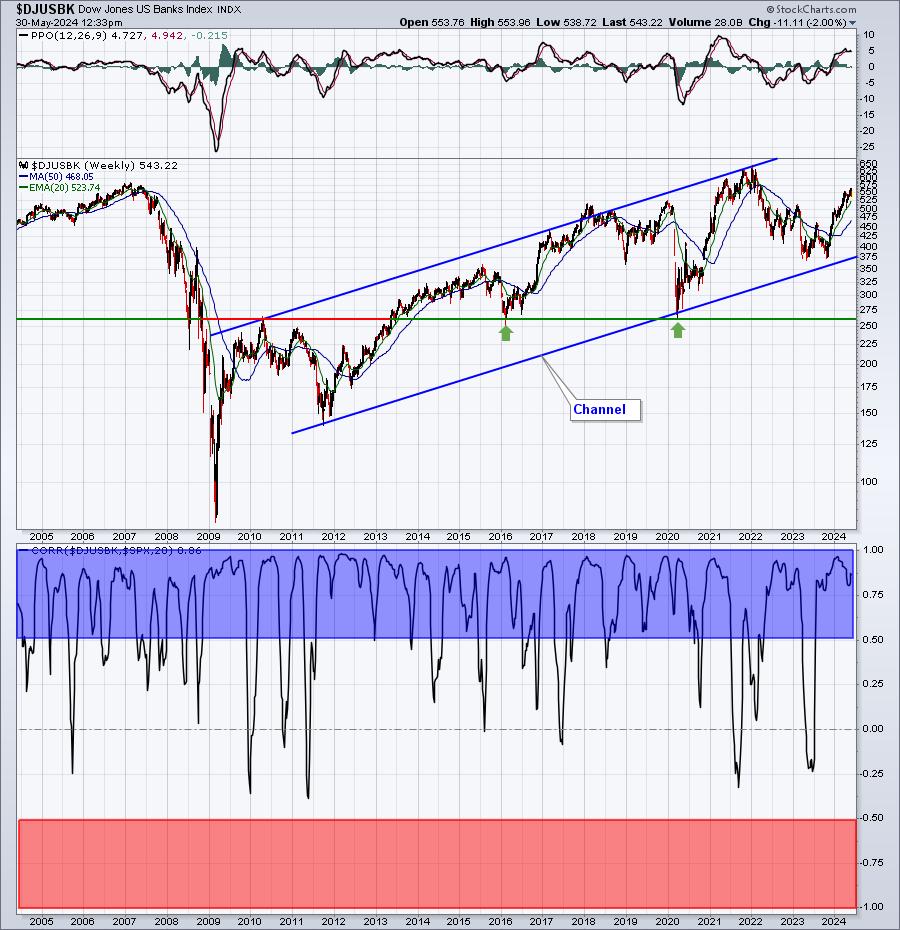
Check out that positive correlation between banks and the S&P 500 over the last two decades. Not ONCE have we seen a move into the -0.50 to -1.00 inverse correlation range. Very few areas of the stock market can make that claim. So we REALLY want to see banks performing well. Currently, banks are trending higher within a long-term secular bull market advance in the S&P 500. It's difficult to bearish the S&P 500 when banks are moving higher, because of how closely these two are tied.
Sector/Industry Focus
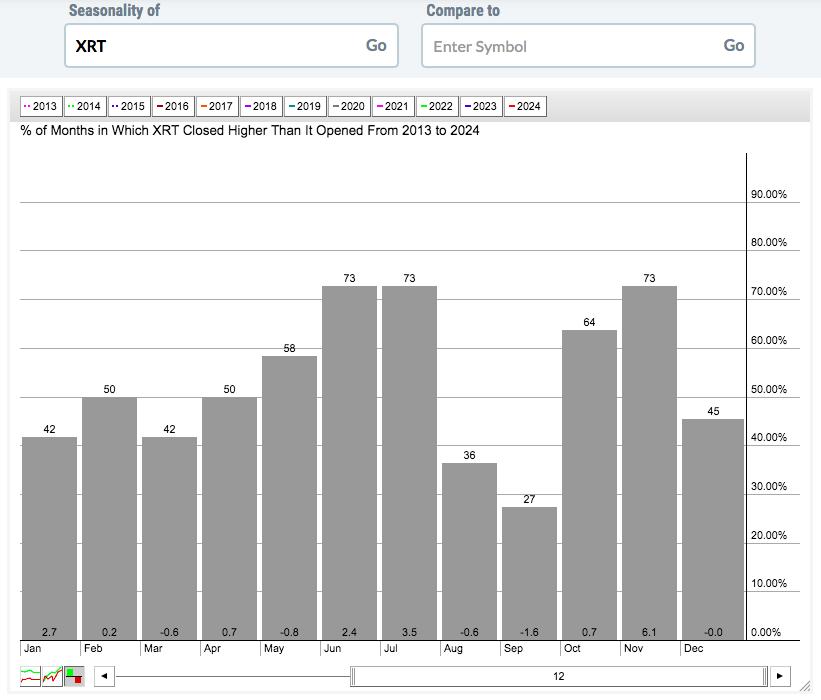
Since the secular bull market began in 2013, retail stocks (XRT) have produced solid results in June and July and the start of these two months is right around the corner. Here's how the XRT has performed in all 12 calendar months over the past 12 years:
Technically, the XRT seems to have bottomed in the near-term and is beginning another leg higher:
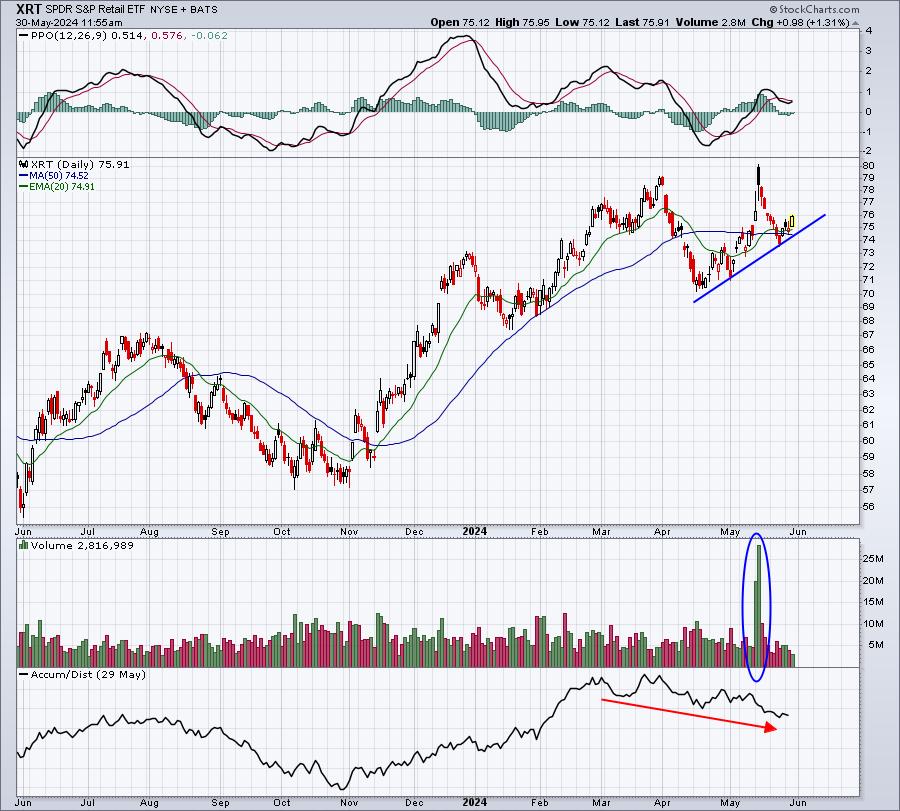
Seasonality is nothing more than a secondary indicator, but when it aligns positively with the technical outlook, it gives me more confidence in the trade. The only problem I see here on the chart is that the AD line is not following price action higher. It's not a deal-breaker, but I'd certainly feel better if the AD line turns higher in the coming days and weeks.
ChartLists/Strategies
Whenever stocks go through a period of sideways action or even a short-term downtrend, I like to look for solid stocks that have fallen to test their rising 20-day EMAs. Here are two with great long-term track records that have done exactly that - pulled back to test their rising 20-day EMAs.
MSFT:
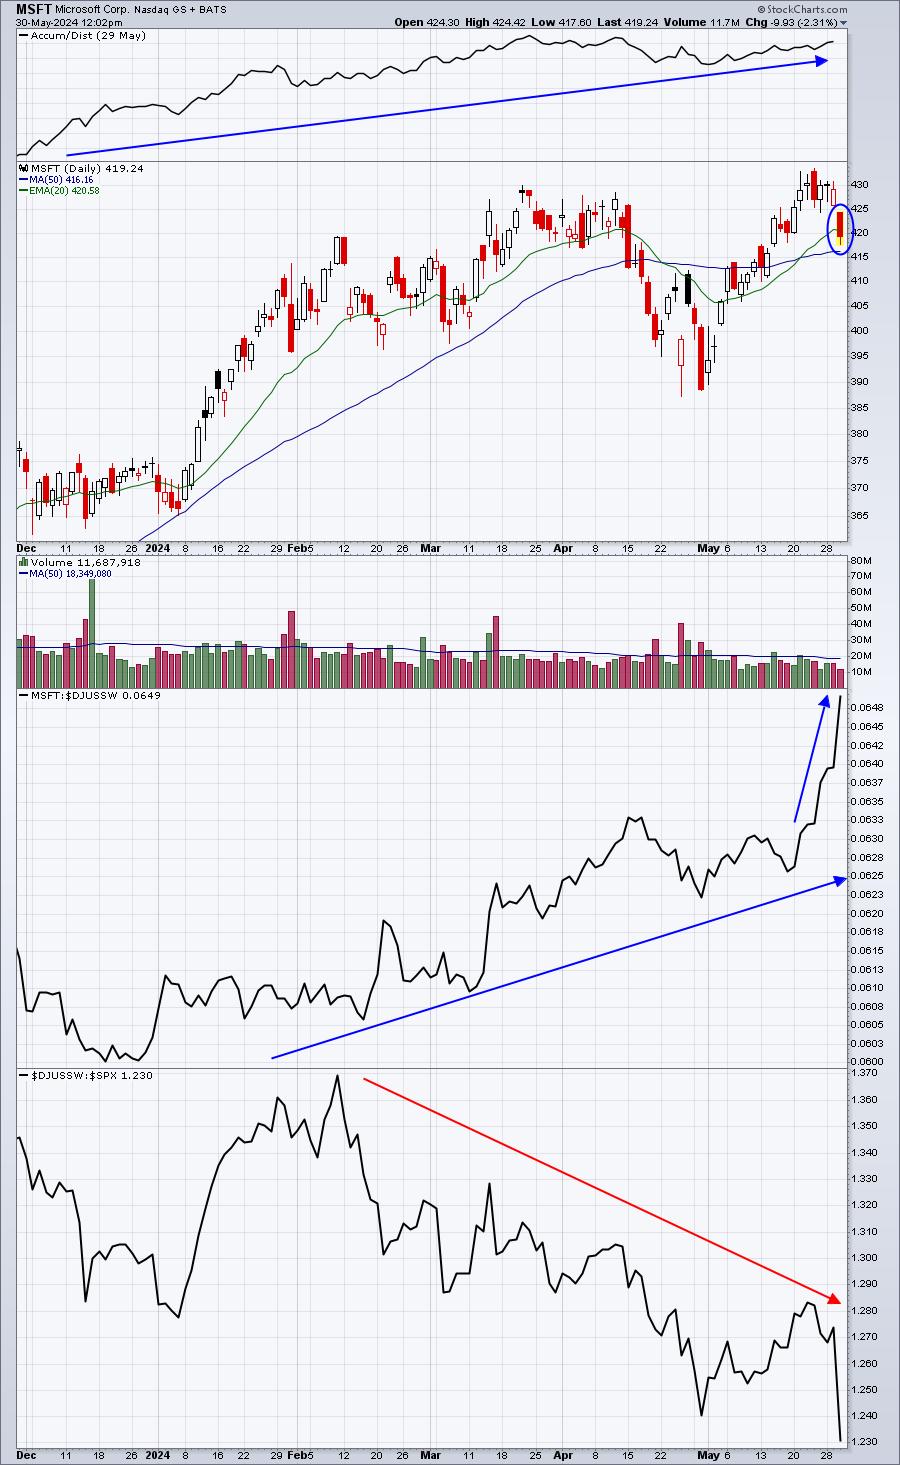
MSFT has the largest market cap in the world. It's a software leader and it's been one for decades. Any time we see a short-term pullback in MSFT, it's generally a great buy point. Also, given its very strong AD line, it's not hard to imagine MSFT rallying this afternoon back above its 20-day EMA, closing in the upper half of today's trading range.
ONTO:
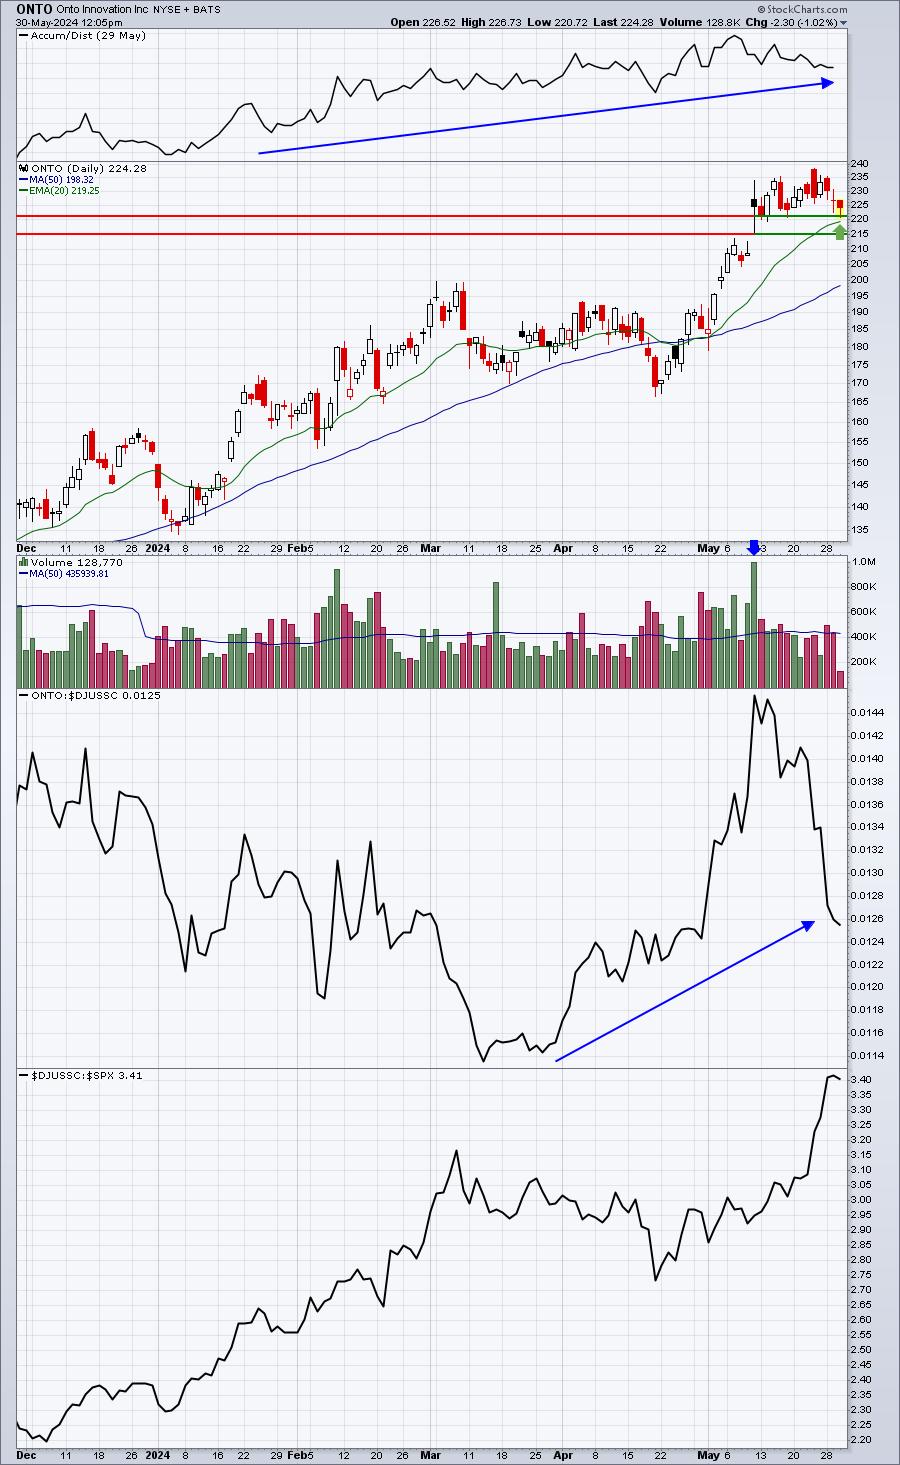
ONTO's latest price high represented a 10-year RELATIVE high vs. semiconductors ($DJUSSC) - no small task given how strong the overall group has been. ONTO didn't quite reach its 20-day EMA, but after falling from 238 to just under 221, that's close enough for me. The strong AD line suggests ONTO is more likely than not going to finish in the upper half of today's candlestick.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, May 30:
COST, RY, DELL, MRVL, CM, VEEV, DG, ZS, MDB, NTAP, HRL, COO, ULTA, BBY, BURL, ESTC, GPS, JWN, ASAN, KSS, FL, AMBA, PD, GES, PHR
Friday, May 31:
None
Economic Reports
Initial jobless claims: 219,000 (actual) vs. 217,000 (estimate)
Q1 GDP (2nd estimate): 1.3% (actual) vs. 1.5% (estimate)
Q1 PCE - annual rate: 2.0% (actual) vs. 2.2% (estimate)
April pending home sales: -7.7% (actual) vs. +0.3% (estimate)
Happy trading!
Tom