
EB Daily Market Report - Tuesday, June 4, 2024
Spring Special EXTENDED
Our Spring Special has been extended a couple days to make sure that everyone is able to benefit from our BEST deal of the year. Hurry before it ends! For more details, CLICK HERE.
Executive Market Summary
- Futures were bifurcated overnight, but all of our major indices opened lower this morning
- Defensive stocks are leading as real estate (XLRE, +1.21%) and consumer staples (XLP, +0.84%) are the only two sectors in positive territory
- Weakness is found mostly in materials (XLB, -1.25%) and energy (XLE, -1.24%), though 9 out of 11 sectors are lower
- The 10-year treasury yield ($TNX) is down for the 4th consecutive session, this time down 9 basis points to 4.31%
- For the 2nd straight day, however, small caps (IWM, -1.30%) have not capitalized on rapidly-declining yields - more on this below
- Cryptocurrencies have turned up again, with bitcoin ($BTCUSD, +1.88%) leading the charge; bitcoin is only 1500 off its all-time high, which is approximately 72000
- Commodities are lower across-the-board, with the most concerning drop being copper ($COPPER, -2.77%); copper is a global economic indicator and it's fallen from 5.20 to 4.53 in just the last 2 weeks
- Crude oil ($WTIC, -0.88%), another global economic indicator, hit $73 per barrel earlier today, its lowest level since early February - and consistent with economic downturns
- CrowdStrike Holdings (CRWD, -0.89%) is a leading stock in software ($DJUSSW, +0.00%) and will report its latest quarterly results after the closing bell today
Market Outlook
I'm growing a bit more nervous, if I'm being honest. I'm not talking about the long-term. We remain in a secular bull market and long-term investors, in my opinion, shouldn't be overly concerned about a long-term secular, or even cyclical, bear market at this time.
But there are more and more signs that suggest to me that the Fed needs to cut rates NOW. If they focus too long on inflation and keep rates too high for too long, they risk turning a mild period of economic weakness into something much deeper. That's what small caps, transports, and now copper prices are telling me.
Small cap stocks (IWM, -1.25%) are losing ground for the second consecutive session, despite a big drop in the 10-year treasury yield ($TNX). That's completely inconsistent with this intermarket relationship over the past several months. When yields rise or fall, they can do so for different reasons. When inflation is a concern, falling rates will typically help stocks as it's a signal that the bond market is less concerned about inflation. Rising rates for inflationary concerns normally will hurt equity prices. I'm wondering if stocks are beginning to react to falling rates in a negative manner, because investors are growing less concerned about inflationary pressures and are instead starting to react to recent signs of economic weakness. Friday's big reversal did not favor growth stocks the way it should have. Now the IWM is reacting negatively to falling rates. We already know transports ($TRAN), which struggle mightily during economic weakness, have been underperforming for many weeks.
Check out the IWM:
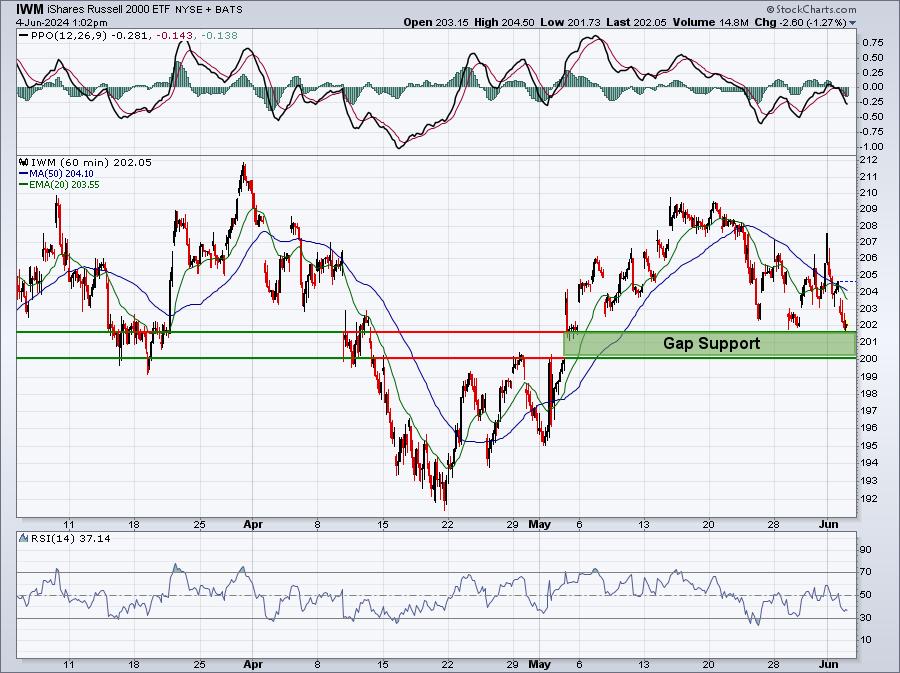
Personally, I will move more towards cash if the IWM fails to hold the gap support zone above. I'll do so, because the IWM is simply not trading in the manner it should. Also, transports opened higher this morning, only to see lots more intraday selling, giving at the least the appearance of further distribution. There will be HUGE economic reports and a Fed meeting over the next 7-10 days. It starts with the ADP employment report tomorrow morning, then comes the May nonfarm payrolls on Friday morning. If we see disappointing jobs data, I suspect we'll see a further drop in the TNX, with the bond market beginning to demand rate cuts. Will the Fed listen under this scenario? I don't know, but when they announce their interest rate decision next Wednesday (June 12th), they'll do so with the May CPI data in hand. That May CPI report will be released the morning of that rate decision. I'm sure the Fed wants to get inflation right, which it needs to. However, it waited too long to raise rates, and if they wait too long to cut, economic weakness could grow much deeper than necessary.
The Fed is definitely in a box and many different asset classes are now suggesting it's time to cut rates.
To summarize, let me once again emphasize that I'm VERY BULLISH the long-term. I am talking about what COULD be a quick selloff given the economic news and Fed meeting upcoming. I really want to see the IWM hold that gap support zone above.
One last key point on copper ($COPPER). Copper has always been a very reliable signal of global economic strength. I was quite happy to see copper prices jump to 5.20 recently, which represented an all-time high. However, it's now looking more and more like a false breakout. We're still in a long-term uptrend as long as copper remains above 4, so it's got plenty of downside room. Still, falling back that quickly suggests that perhaps we'll have to wait awhile longer before global economic activity surges.
A nice afternoon rally on the IWM would be welcome news, from a bullish perspective. We'll see.
Sector/Industry Focus
Specialty retailers ($DJUSRS) have an affinity for June. They've outperformed the S&P 500 roughly two-thirds of Junes since 2013, the time this secular bull market started. Their average June outperformance is 1.4%, which ties January as its best relative month. Technically speaking, the DJUSRS is consolidating after a surge higher in early May:
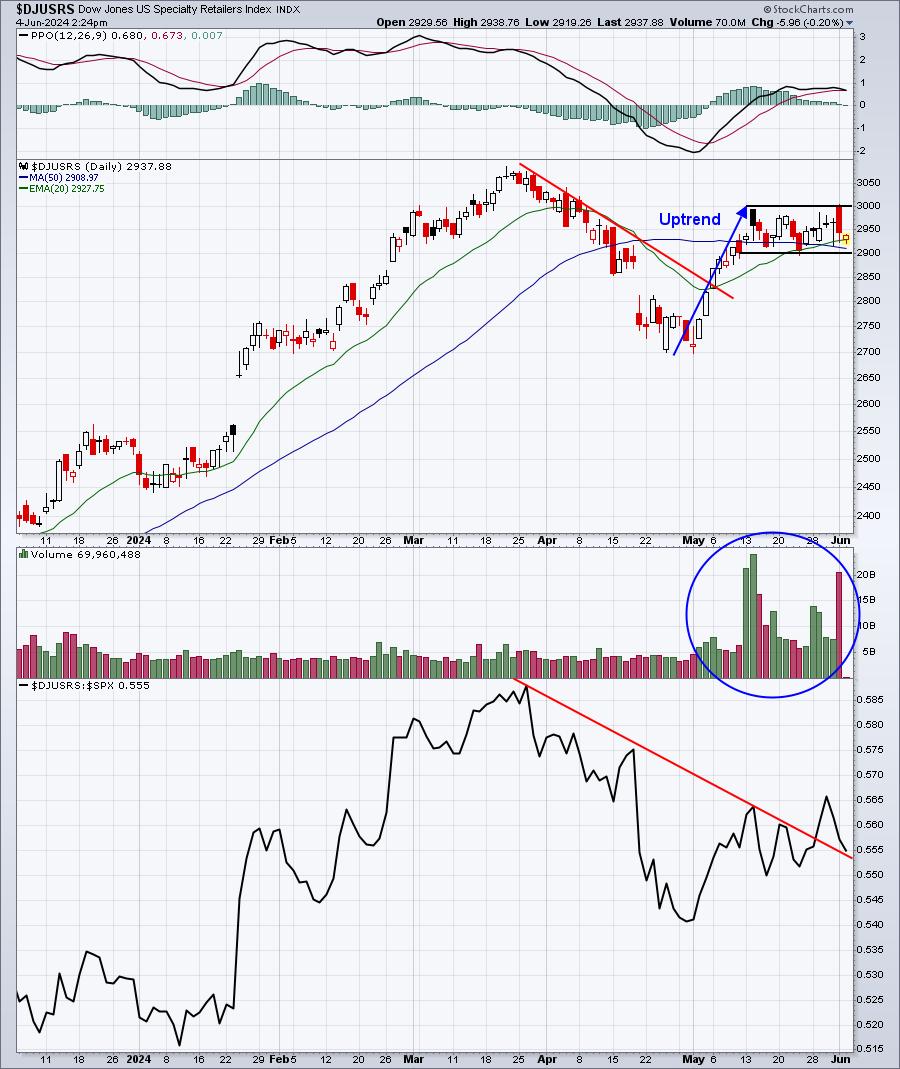
It appears that both an absolute downtrend and a relative downtrend have been broken, which is good news for the group. As long as the DJUSRS doesn't lose price support at 2900, I see higher prices ahead. A breakdown, however, would also include breaches of both key moving averages.
ChartLists/Strategies
On today's Trading Places LIVE, I spent some time talking about Super Micro Computer (SMCI), suggesting that market makers could be manipulating retail traders in order to build up inventory for its institutional clients. We saw it recently with Apple, Inc. (AAPL) when it traded in the 160s/170s. Now we see AAPL back near all-time highs again.
Below are two charts of SMCI and I've provided two different intraday analyses. The first is a breakdown of intraday trading on SMCI in 2024 year-to-date. The second is a similar breakdown, but only for the month of May. Check it out:
SMCI - 2024 Year-to-Date:
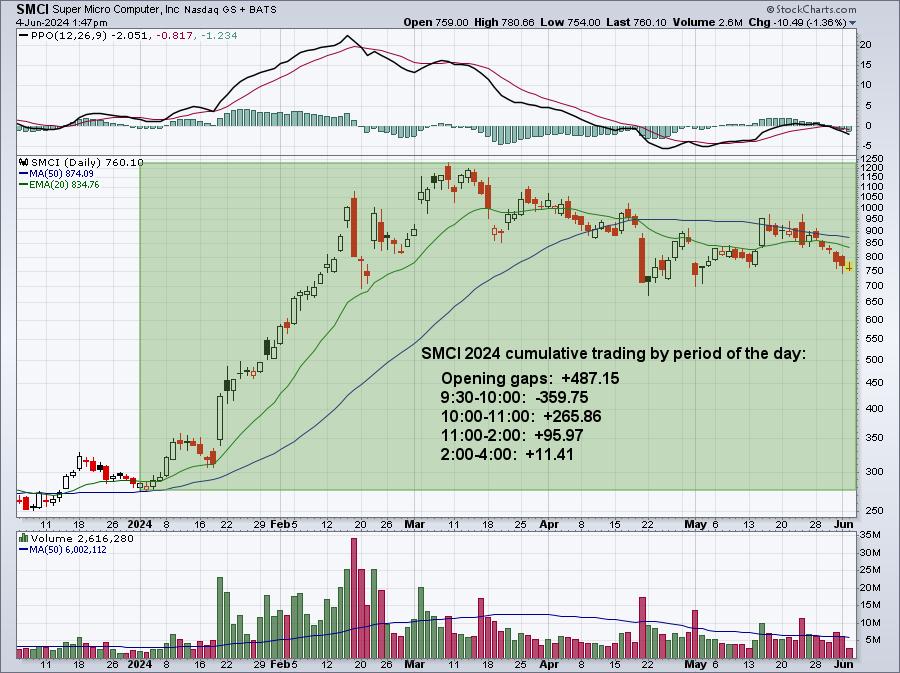
The "net" has been accumulation in SMCI throughout 2024. However, the time period from 10am ET to 4pm ET has been particularly strong, representing accumulation, in my view. From the March 7th close through the April 30th close, however, there was much distribution ahead of SMCI's quarterly earnings report, which was released just after that April 30th closing bell. But here's what has happened to SMCI's intraday trading since those earnings were released:
SMCI - May 2024
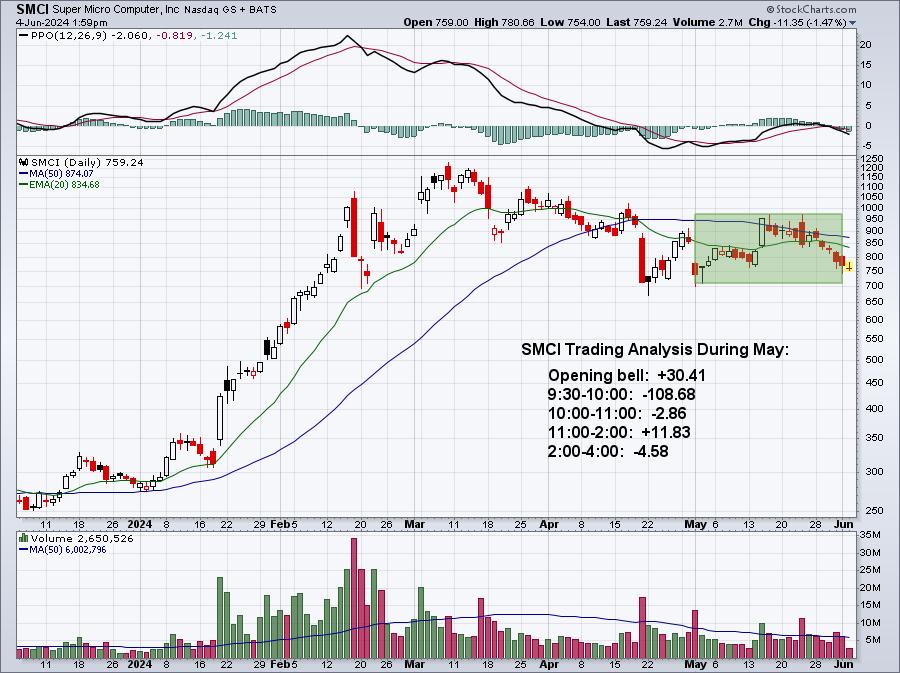
This certainly isn't meant to suggest SMCI goes higher from here. But it is trading differently than it was prior to its earnings report. We've gone from distribution throughout the day to distribution only through 10am ET. The 10am ET to 4:00pm ET period during May was essentially a wash, with a slight rise during this period. That's completely different than the pure distribution all day long in the 6-7 weeks prior to earnings.
We are beginning to watch the intraday action on SMCI and many other key stocks (think Magnificent 7 and a few others). The purpose of this research will be to help us identify potential turning points on key charts BEFORE the price actually begins to rise. It's helped thus far on AAPL and it was a big reason why I called a bottom on the SPY in June 2022. As we analyze more data, we'll be sure to report our findings to all of you.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, June 4:
CRWD, FERG, HPE, BBWI, CNM, GWRE, DCI, PVH, VRNT
Wednesday, June 5:
LULU, DLTR, BF/A, CPB, FIVE, THO, SMAR, OLLI, SMTC, VSCO
Economic Reports
April factory orders: +0.7% (actual) vs. +0.7% (estimate) - March factory orders revised lower from +1.6% to +0.7%
April JOLTS: 8.06 million (actual) vs. 8.40 million (estimate)
Happy trading!
Tom