
EB Daily Market Report - Thursday, September 26, 2024
Event on Saturday
We will be hosting our latest event, "History of Q4 Market Bottoms", on Saturday morning at 10:00am ET. Members DO NOT need to register. You are automatically registered. A recording of the event will be provided, just in case you cannot make the live event.
There is a FREE ebook giveaway for those who register, but since members do not need to register, we are providing access to this ebook by simply following THIS LINK or you can go to the Member Portal on our website and click the link there.
Room instructions will be sent to you on Saturday morning prior to the 10am ET start time. There will also be a link provided on the Member Portal to access the room.
Executive Market Summary
- Futures were higher overnight and our major indices gapped higher at the opening bell
- The Dow Jones has done the best job of hanging onto those opening gains
- Meanwhile, the NASDAQ 100 filled the gap and moved back to breakeven, though we've seen strength return from 1-2pm ET
- The market is bifurcated with 8 sectors higher and 3 lower; generally speaking, aggressive stocks are outperforming their value counterparts
- Materials (XLB, +2.08%) is today's strongest sector, while energy (XLE, -1.63%) underperforms
- Crude oil prices ($WTIC, -3.16%) are taking another big hit, this time dropping to $67 per barrel
- Many other commodities are higher, especially copper ($COPPER, +3.47%)
- Cryptocurrencies continue to improve, with bitcoin ($BTCUSD, +3.09%) and etherium ($ETHUSD, +2.20%) leading
- Micron Technology (MU, +15.17%) is today's best-performing S&P 500 stock after posting quarterly earnings well ahead of consensus estimates AND raising guidance
- As a result of MU's strength, semiconductors ($DJUSSC, +1.68%) are again showing strength and threatening their August high and their overhead gap resistance from the July 17th gap lower
Market Outlook
I thought it would be a good time to see where we stand in the current secular bull market channel. Let's see how much room we have to the upside, before we begin to bang on the door of channel resistance, while also looking at downside potential:
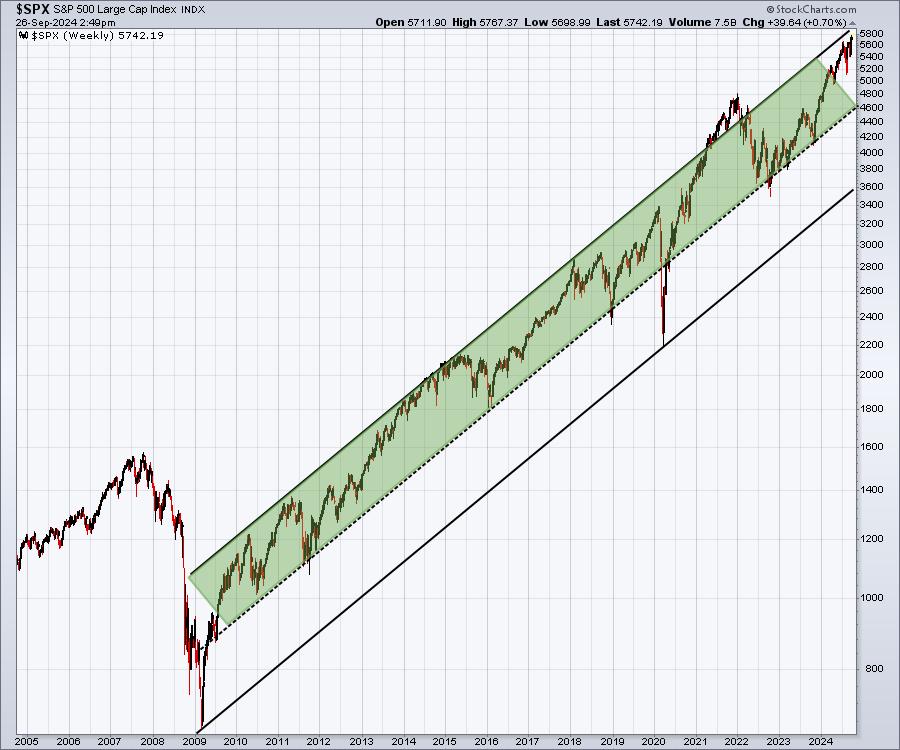
The green-shaded area represents the top half of the current bull market channel. We've moved down to establish key lows in 2009 during the financial crisis and again in 2020 during the pandemic. It takes a LOT of fear and weakness to reside in the lower half of the channel. Nearly ALL of the secular bull market trading takes place in the upper half of the channel, so that's really what I expect to see during the balance of 2024 and throughout 2025.
Sector/Industry Focus
While technology (XLK) has been consolidating on an absolute basis and weakening on a relative basis (since June), other sectors have shown significant improvement. This has led to a market where many asset classes, indices, sectors, etc. are participating in this secular bull market. Rotation is a CRITICAL piece necessary for bull markets to thrive. Yesterday, in my brief DMR, I highlighted several sectors, including XLV, XLI, XLRE, and XLP, that were showing excellent absolute strength. Well, let's add materials (XLB) to this list:
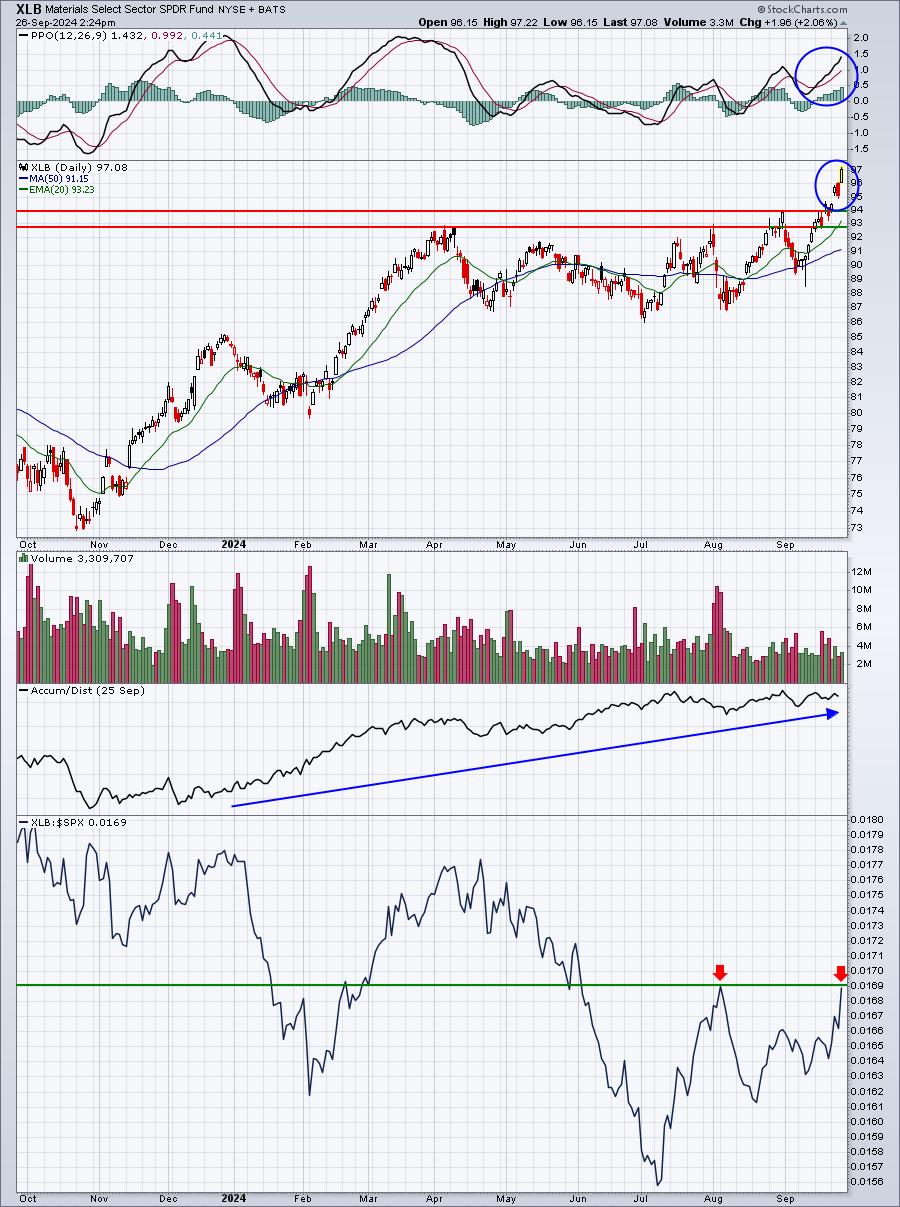
The price chart shows that the XLB has already broken out. The bottom panel, however, shows whether the XLB is leading to the upside, or simply going along for the ride. Clearly, the XLB has shown significant relative strength off its July relative low. However, can the XLB sustain this relative strength long enough to clear the early-August relative high? If it can, then there's an increased chance that the XLB shows more leadership into October.
ChartLists/Strategies
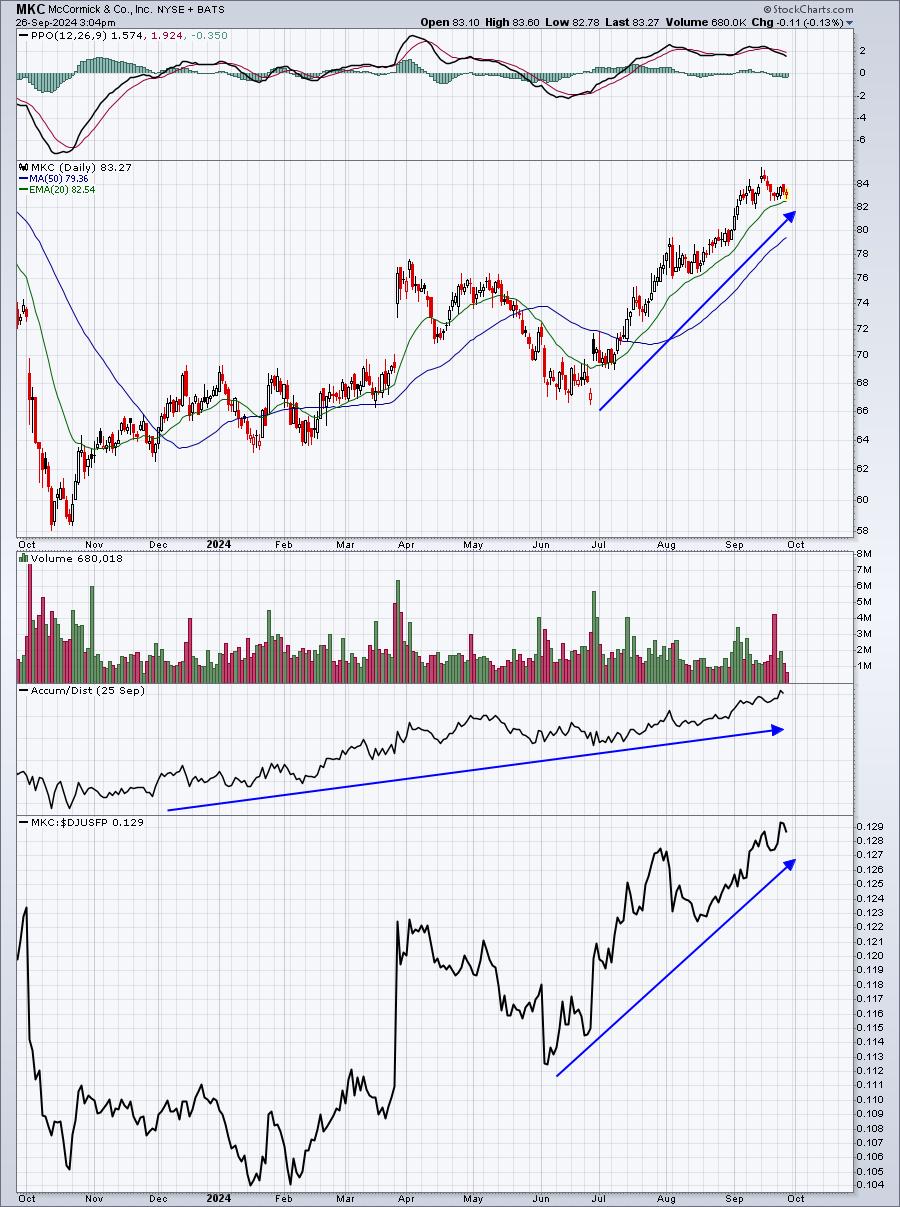
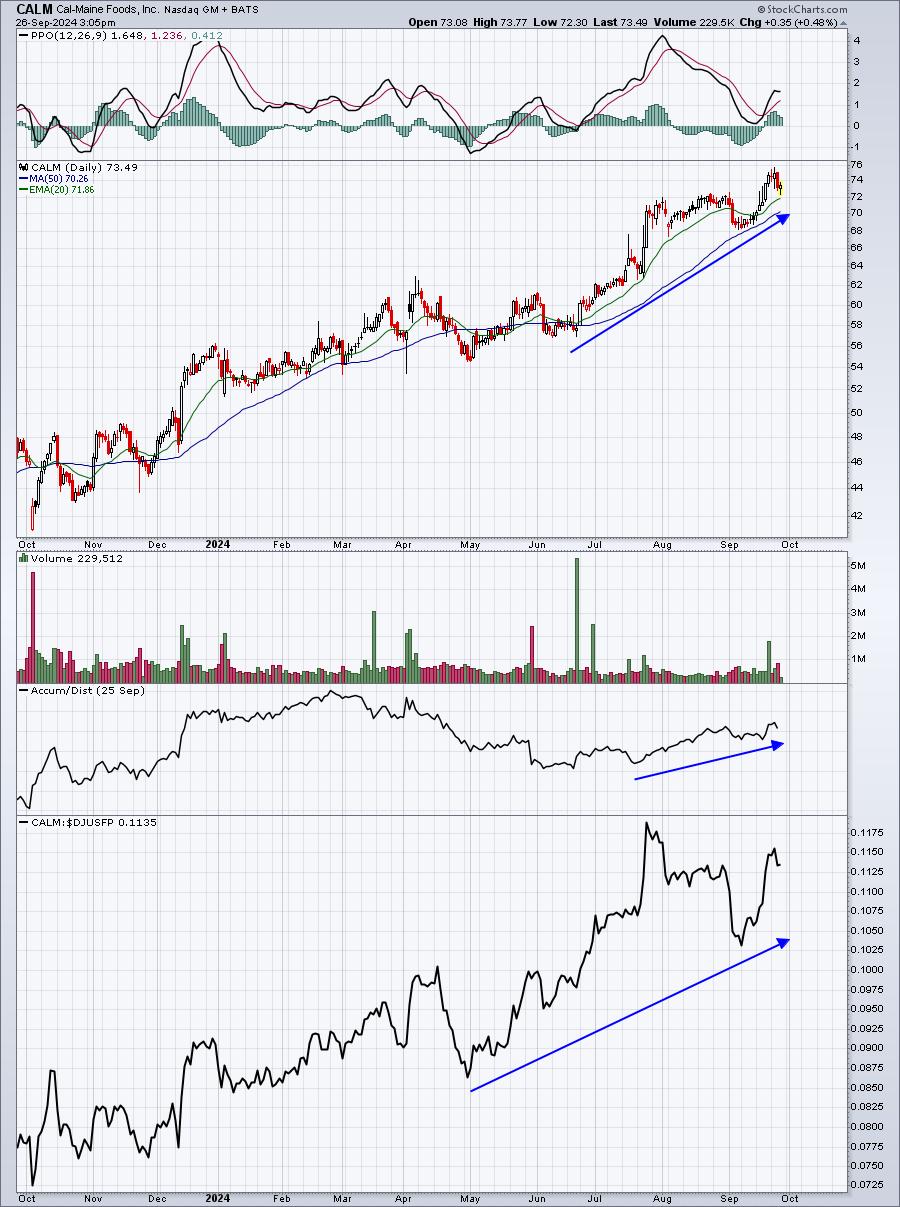
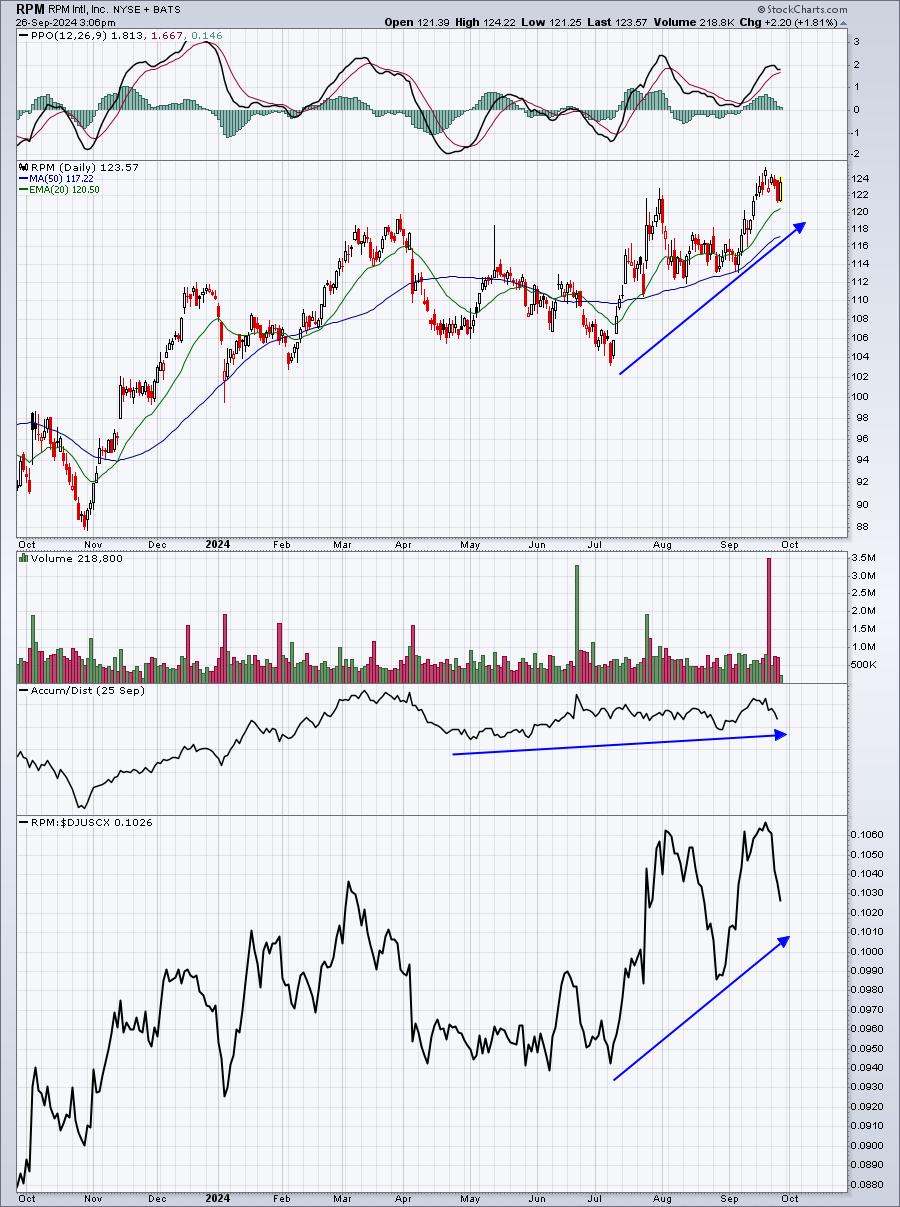
Looking ahead at companies that will be releasing quarterly earnings results by Friday, October 4th, here are 4 that appear to be trading well ahead of those quarterly results:
MKC:
CALM:
RPM:
CAG:
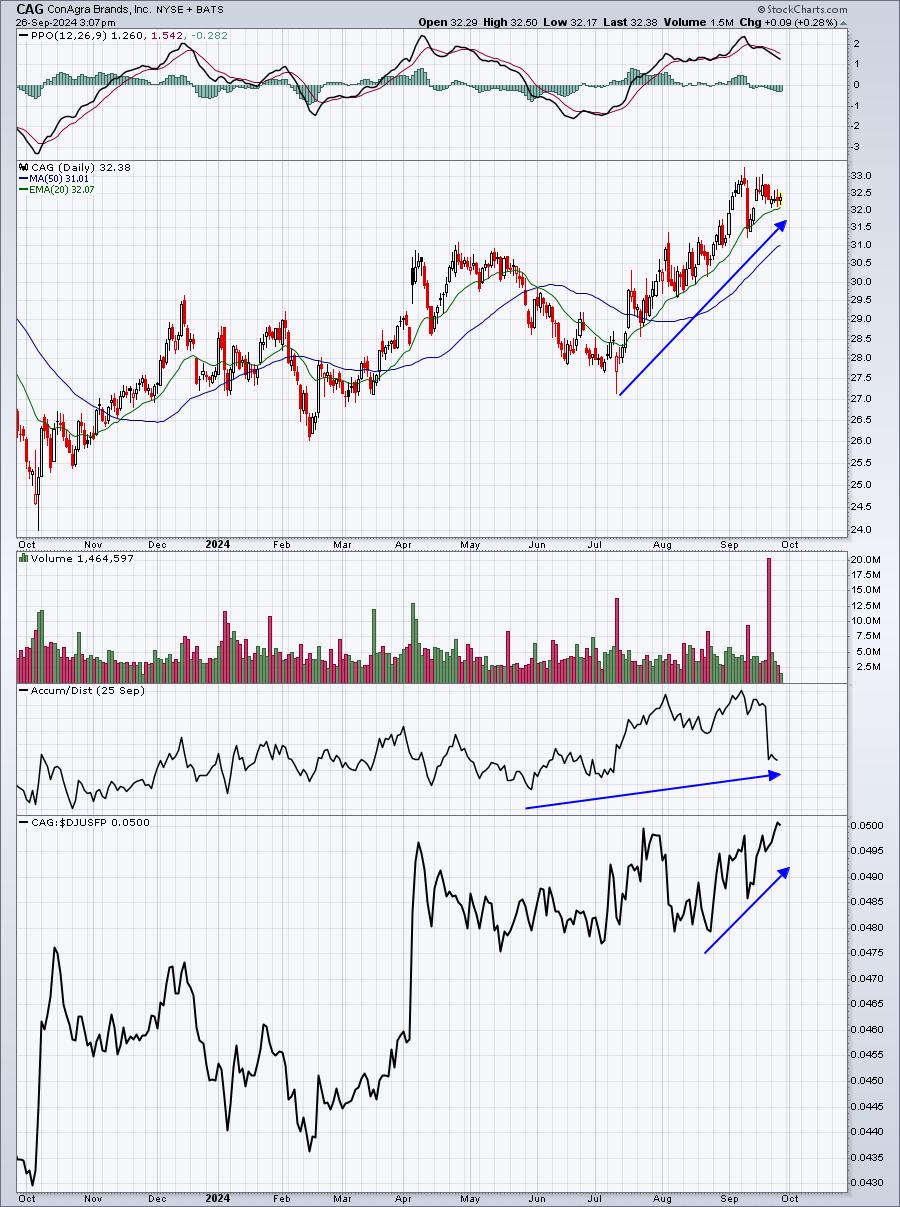
RPM is a materials stock, but the other 3 are staples stocks. On a relative basis, it appears to me that the more defensive- and value-oriented stocks are trading better on a relative basis.
Earnings Reports
Here are the key earnings reports for the next two days. I include all companies with market caps of $10 billion or more and also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Thursday, September 26:
COST, ACN, JBL, KMX, SNX, MTN, BB
Friday, September 27:
None
Economic Reports
Initial jobless claims: 218,000 (actual) vs. 224,500 (estimate)
Q2 GDP (2nd estimate): 3.0% (actual) vs. 3.0% (estimate)
August durable goods: +0.0% (actual) vs. -0.2% (estimate)
August durable goods ex-transports: +0.5% (actual) vs. -0.1% (estimate)
August pending home sales: +0.6% (actual) vs. +3.1% (estimate)
Happy trading!
Tom