
EB Daily Market Report - Tuesday, October 1, 2024
Executive Market Summary
- Futures were slightly lower overnight and our major indices gapped lower
- Selling has intensified across most areas of the market, with selling a tad stronger on the NASDAQ 100
- Energy (XLE, +1.91%) is where most of today's strength lies, while technology (XLK, -2.27%) is being hit hard
- Semiconductors ($DJUSSC, -3.01%) are under pressure once again and computer hardware ($DJUSCR, -3.19%) reversed yesterday's strong gains; Apple, Inc. (AAPL, -3.21%) is testing its 20-day EMA
- Middle East tensions, particularly those between Iran and Israel, have fueled higher crude oil prices ($WTIC, +4.44%), but also a much higher Volatility Index ($VIX, +11.48%)
- As I've said before, the VIX remaining at or near the 17 level suggests U.S. equities won't handle bad news well - exactly what we're seeing this morning, in my opinion
- The 10-year treasury yield ($TNX) is down 8 basis points to 3.72%, as money rotates more towards safety
- Defense stocks ($DJUSDN, +2.90%) are benefiting from Middle East tensions with Northrop Grumman (NOC, +4.24%) and Lockheed Martin (LMT, +3.79%) among today's S&P 500 leaders
- Paychex, Inc. (PAYX, +4.90%) is surging after reporting quarterly earnings ahead of estimates
Market Outlook
Tensions in the Middle East are absolutely adding to the increased volatility, but U.S. equities were already set up for a potential decline after printing a very bullish sentiment reading last week. Remember, sentiment readings are contrarian, so bullish developments in sentiment typically result in bearish market reactions. That's the case today. Check out the 5-day SMA of the equity only put call ratio that I published early yesterday in the EB Weekly Market Report:
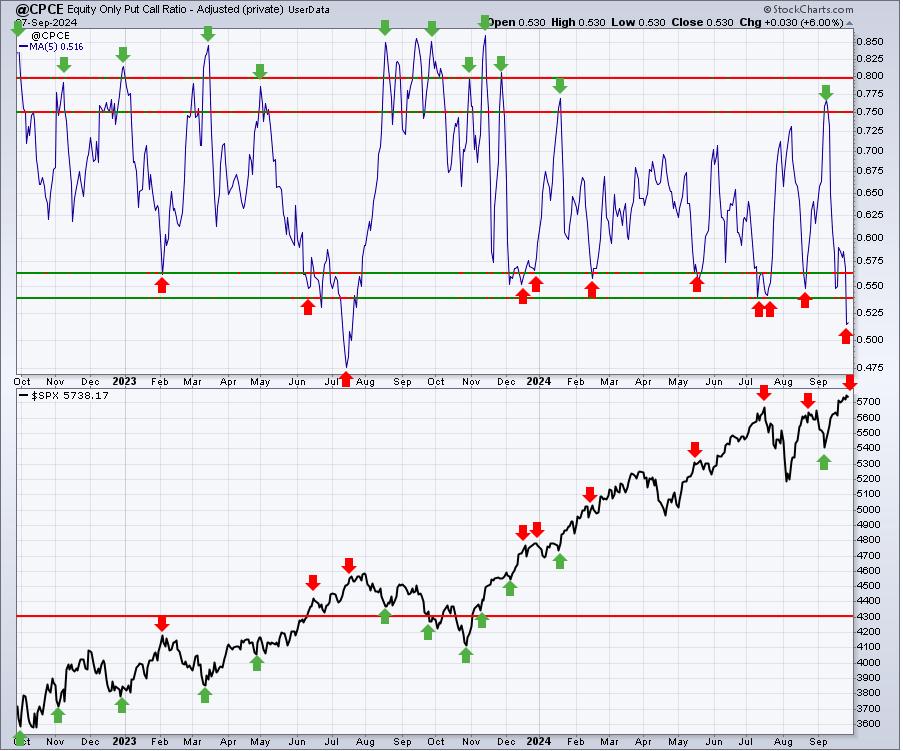
Thursday's 5-day SMA was .516 (shown above). The latest reading on Friday was a 5-day SMA of .53. These types of bullish $CPCE readings typically result in short-term selling, which is exactly what we're seeing today. It doesn't help that the Volatility Index ($VIX) surged to near 21 this morning.
Sector/Industry Focus
Growth (IWF, -1.49%) vs. value (IWD, -0.20%) is once again an issue today as growth stocks are taking a relative beating. Check out the S&P 500's latest at a breakout and where our key relative sustainability ratios were positioned:
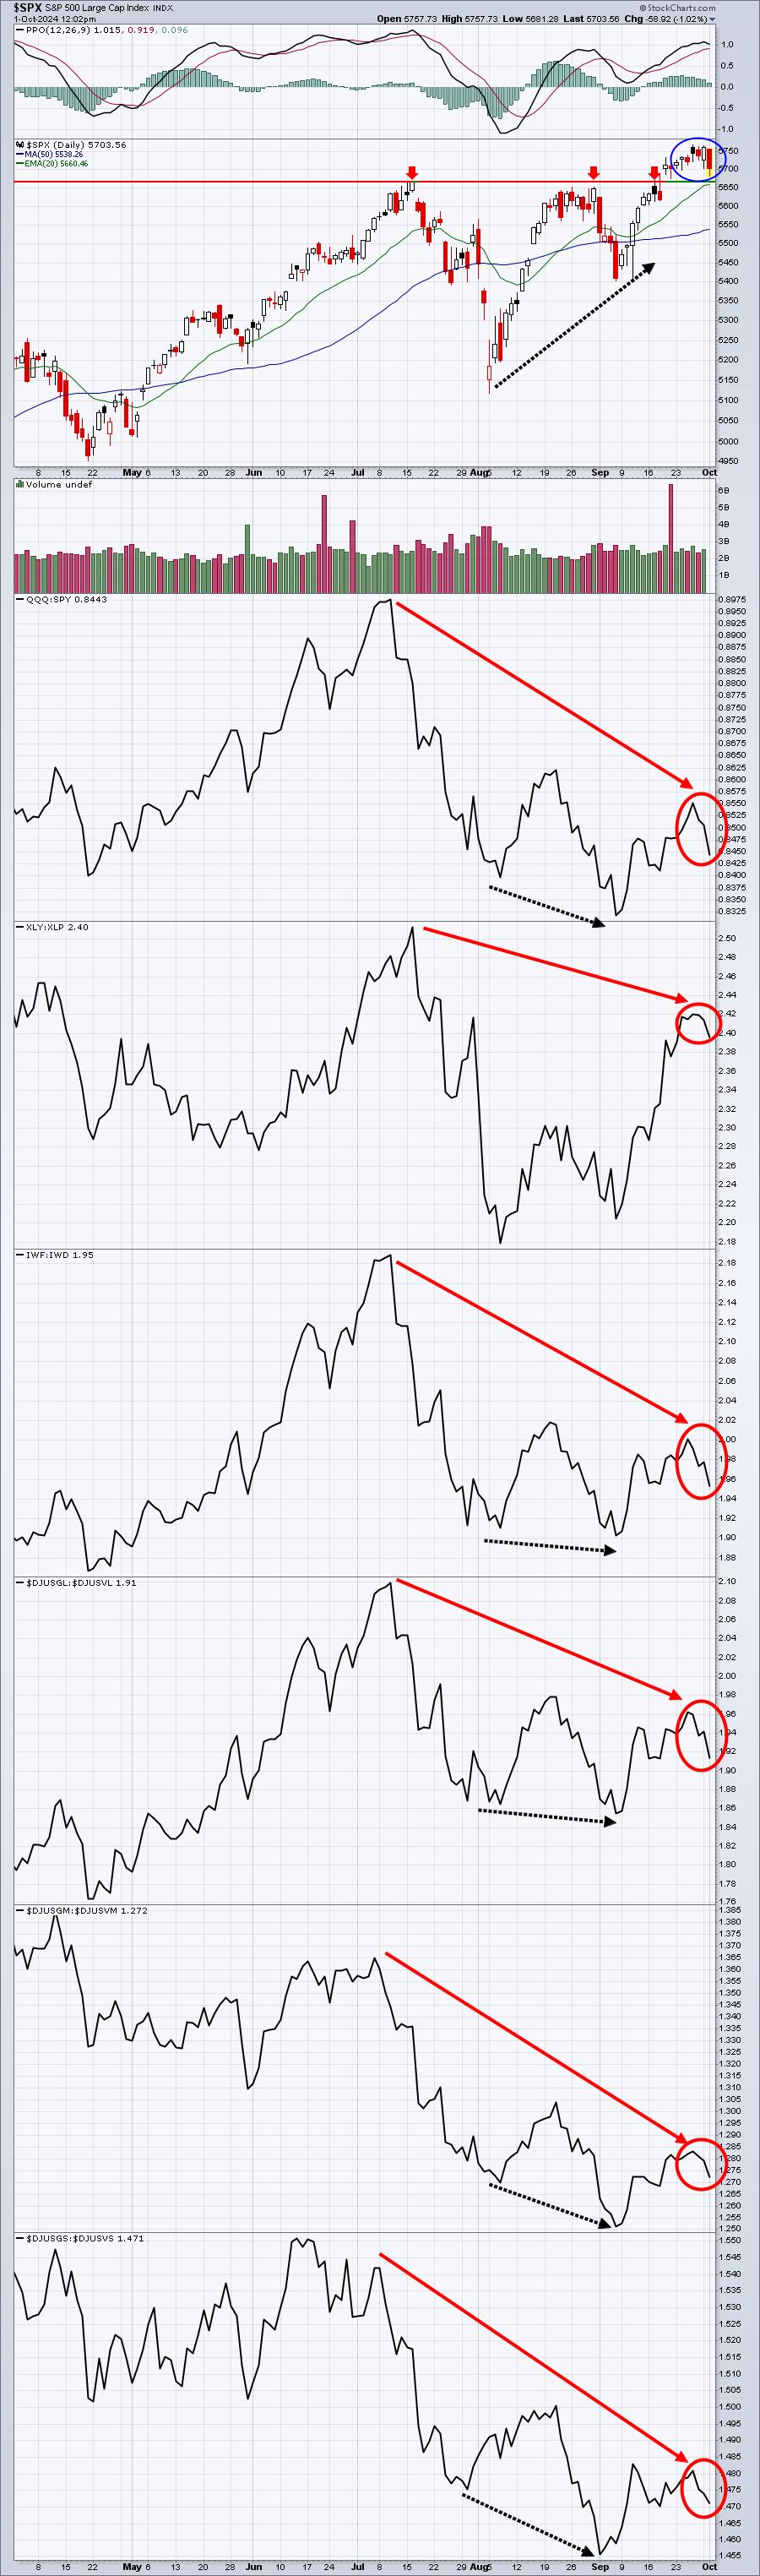
One major problem that the S&P 500 is facing is its continuing attempt to advance significantly, while growth stocks and sustainability ratios are rolling over and apparently heading lower. The dark red circles highlight one of the biggest, if not the biggest, market issue right now. Sentiment is a problem, for sure, but lack of support from aggressive areas makes this recent S&P 500 breakout challenged at best.
ChartLists/Strategies
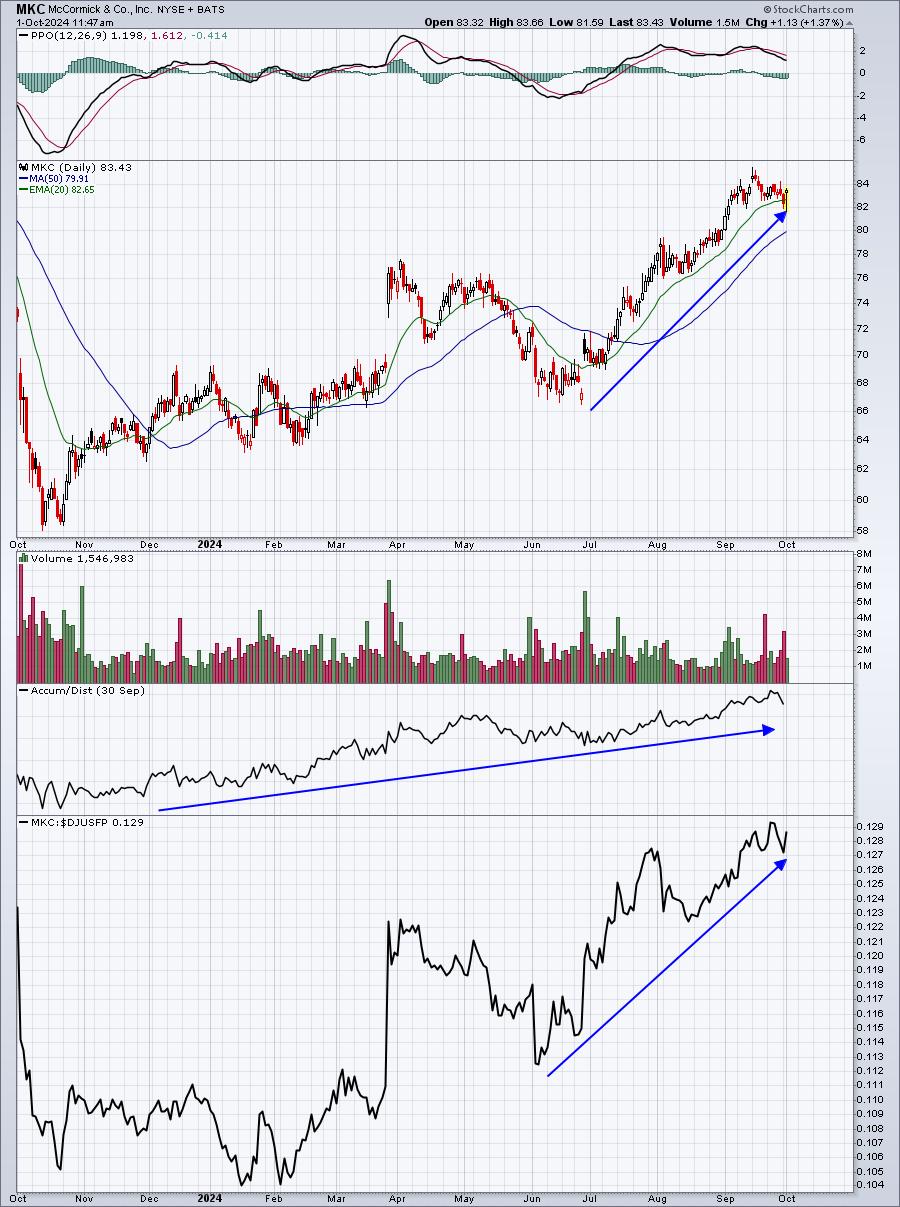
I provide 4 stocks last week that looked solid on a relative basis as we approached their earnings reports. The stocks were MKC, CALM, RPM, and CAG, mostly defensive stocks. MKC reported this morning, easily beating both revenue and EPS consensus estimates. MKC gapped up earlier, pulled back, but has once again strengthened. Check out the MKC chart:
CALM will report its earnings later this afternoon, while RPM and CAG will both report tomorrow morning before the opening bell.
Earnings Reports
Here are the key earnings reports for the next two days. I include all companies with market caps of $10 billion or more and also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, October 1:
NKE, PAYX, MKC, LW, AYI, CALM
Wednesday, October 2:
RPM, CAG, LEVI, NG
Economic Reports
September PMI manufacturing: 47.3 (actual) vs. 47.0 (estimate)
September ISM manufacturing: 47.2 (actual) vs. 47.6 (estimate)
August construction spending: -0.1% (actual) vs. -0.3% (estimate)
August JOLTS: 8,040,000 (actual) vs. 7,700,000 (estimate)
Happy trading!
Tom