
EB Daily Market Report - Tuesday, October 29, 2024
Executive Market Summary
- Futures were lower overnight and our major indices did gap down at the opening bell
- We've seen relative strength today in NASDAQ 100 shares, as we prepare for several Mag 7 stocks to report their quarterly results, including Alphabet (GOOGL, +1.89%), which is set to report this afternoon
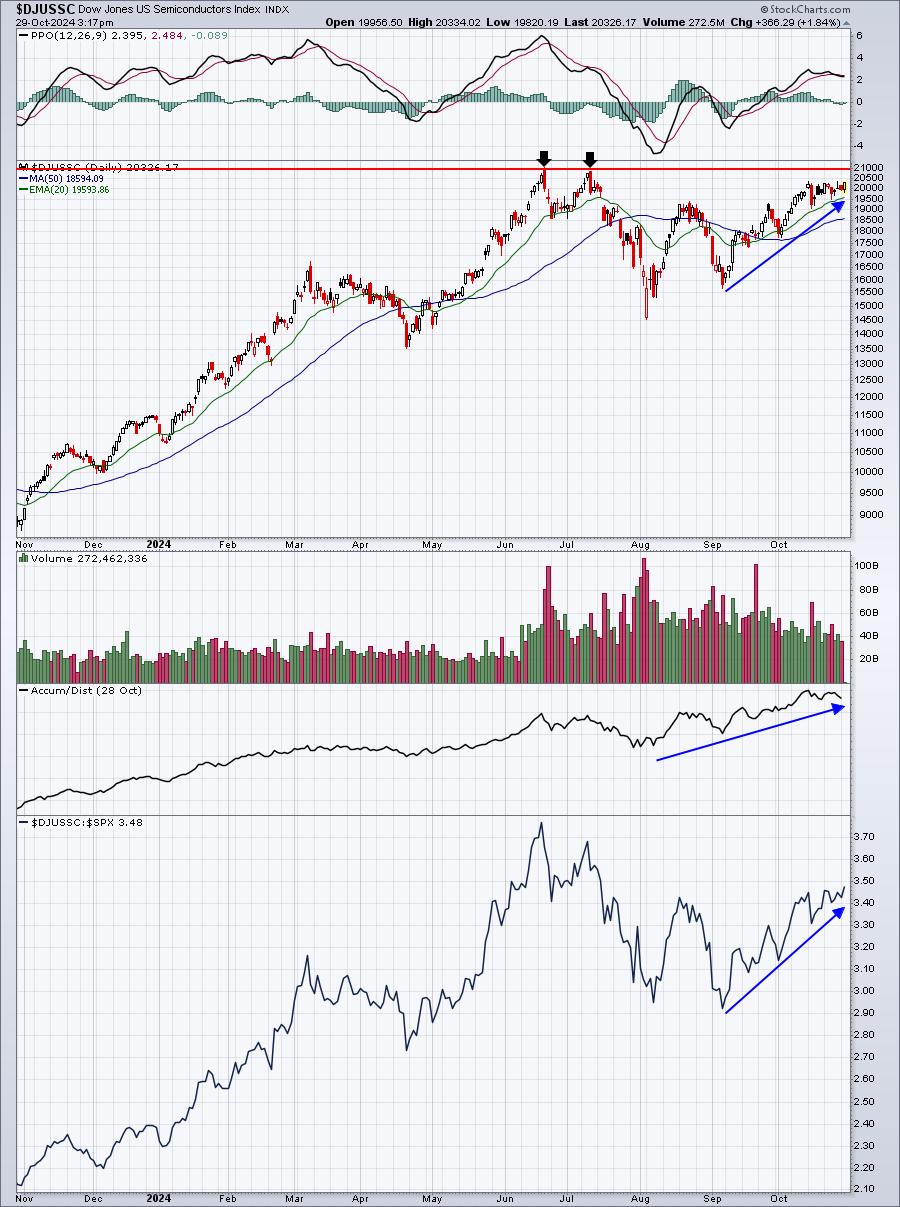
- Advanced Micro Devices (AMD, +3.71%) is a semiconductor ($DJUSSC, +1.79%) that will also report today
- The 10-year treasury yield ($TNX) was up 6 basis points earlier, but has since backed off to the flat line
- Etherium ($ETHUSD, +6.25%) and bitcoin ($BTCUSD, +5.25%) are leading cryptocurrencies higher
- Commodities are mixed today, though crude oil ($WTIC, -0.25%) remains under pressure near $67 per barrel
- Aggressive sectors are performing well today as technology (XLK, +1.40%) leads all sectors; semiconductors and software ($DJUSSW, +1.54%) are boosting technology stocks
- Cadence Design Systems (CDNS, +12.76%) is powering forward after earnings and threatening to clear overhead resistance between 280-285
Market Outlook
Growth (IWF) vs. value (IWD) continues to trend higher, despite the rise in the 10-year treasury yield ($TNX). Over the past few years, I've used the movements in the TNX to help me determine how the bond market views inflation. Bond investors will sell bonds if they believe that inflation is a persistent problem. Why? Because they demand higher returns to help offset the impact of inflation. After all, who wants to own a 4% 10-year treasury when inflation is running high at 6-7%? No one. So treasuries will sell and the yields, which always move inversely to price, will soar.
So there's been this inverse relationship between the TNX and the IWF:IWD ratio. Higher yields have meant higher inflation, and that, in turn, leads stock investors shying away from growth stocks, dropping that IWF:IWD ratio. But if yields are rising because of economic strength or perceived economic strength ahead, growth stocks will benefit during periods of rising yields.
Check out this chart:
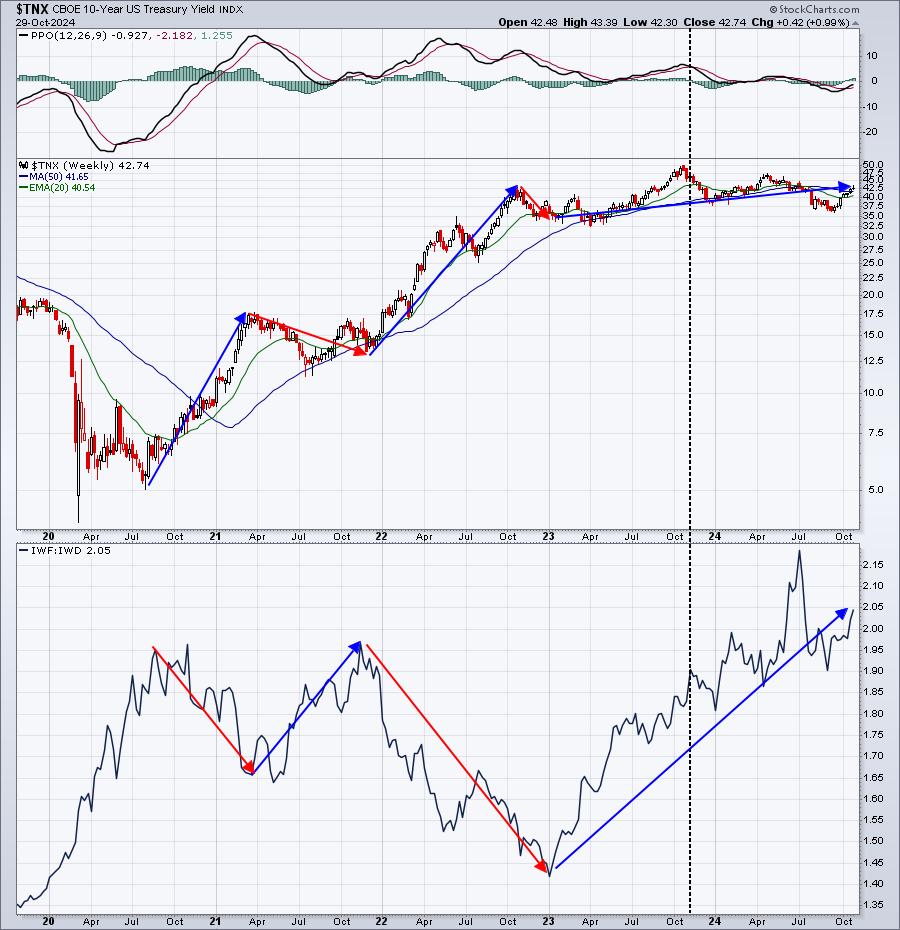
It's fairly obvious to me that the TNX and the IWF:IWD growth value ratio were moving completely opposite one another from 2020 through early-2023. But since inflation has been falling, the relationship between the TNX and IWF:IWD is no longer an inverted one. That's because, in my opinion, Wall Street is no longer investing based upon an inflation threat. Instead, rates are now likely moving higher, because of improving economic conditions ahead. Those improving economic conditions also benefit growth stocks as earnings acceleration improves.
Sector/Industry Focus
Advanced Micro Devices (AMD) reports its quarterly results this afternoon and has a chance to be a catalyst for a semiconductors breakout. As it stands right now, the DJUSSC could close at its highest level since July 2024, when a double top formed:
ChartLists/Strategies
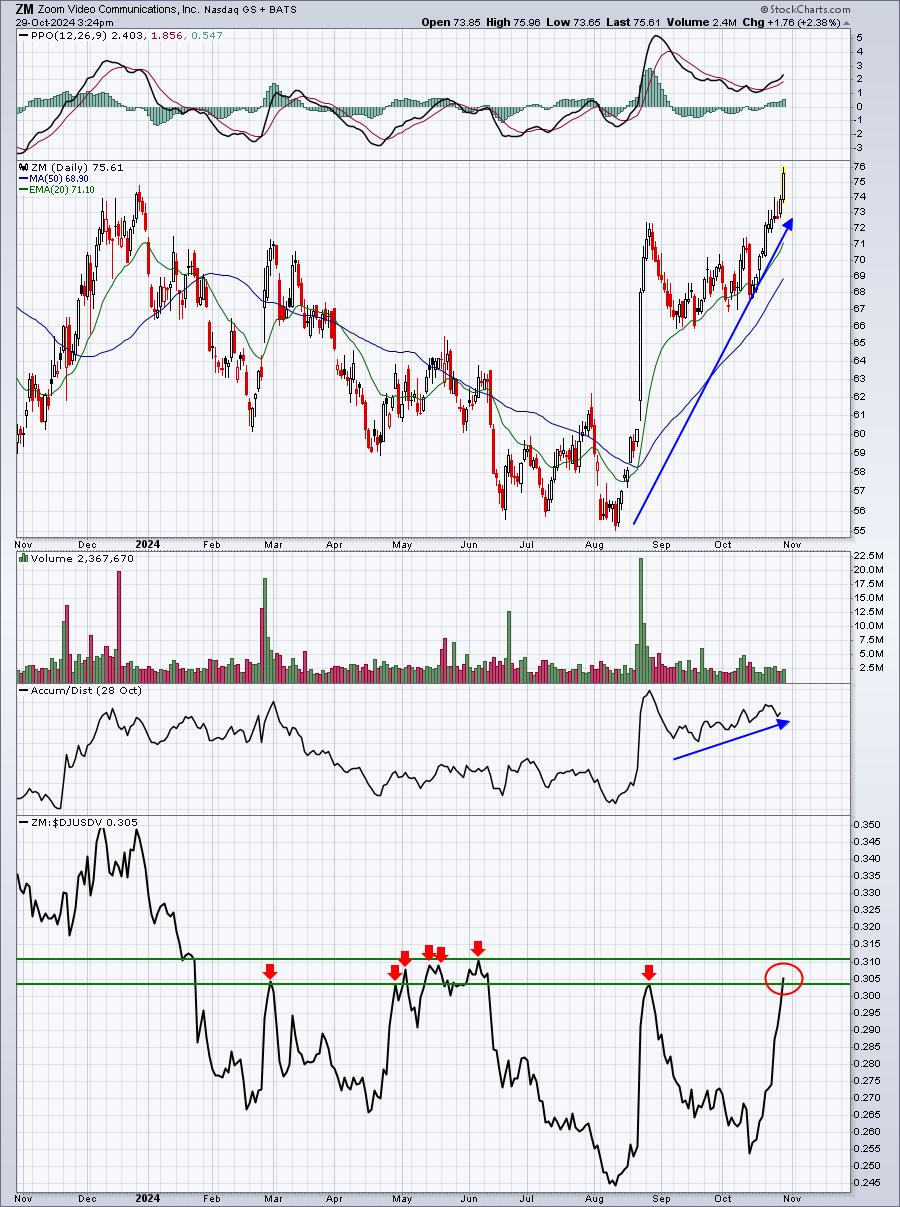
It's been a long, LONG time since Zoom Video Communications (ZM) closed above 75.00. Since March 1, 2023, I counted 16 separate trading days where ZM has traded above 74.00 intraday, without ONCE closing above 75.00. Currently, ZM is trading above 75, so this could mark a very critical breakout for ZM:
Earnings Reports
Here are the key earnings reports for the next two days. I include all companies with market caps of $10 billion or more and also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, October 29 - after market close (AMC):
GOOGL, V, AMD, SYK, CB, AMT, MDLZ, CMG, RSG, OKE, EA, EXR, EIX, FE, FSLR, ESS, SNAP, EQT, IEX, AMH, BXP, RDDT, BMRN, DVA, WPC, UNM, EXE, CZR, QRVO, CHE, ALSN, EXEL, STAG, MOD, MTH, VRNS, APAM, MIR, WERN, CAKE, TXG, ATRC, NGVT
Wednesday, October 30 - before market open (BMO):
LLY, ABBV, CAT, ADP, UBS, TT, GSK, ITW, TEL, KHC, HES, OTIS, GEHC, EXC, VRSK, MLM, VMC, HUM, TW, GRMN, CDW, BIIB, FTV, GPN, SW, ZBH, UMC, AER, UTHR, NI, CLH, ARCC, FLEX, XPO, BG, NBIX, PSN, TECH, WING, DAY, BSAC, ITCI, HESM, AXTA, DRS, BLCO, KEX, OSK, HR, SITE, REYN, CSWI, OMF, BPMC, SLGN, CWEN, OPCH, GTES, AVT, GPI, SHAK, BLKB, MHO, EAT, ALE, TEX, GHC, LIVN, UE, CRTO, ROCK, EXTR, OMCL, ARVN, CLBK, OSW, NVCR, COCO, NAVI, SCL, CHEF, INMD, DAN, DQ, THRM, JKS, AVNS
Economic Reports
August Case-Shiller home price index: +0.4% (actual) vs. +0.3% (estimate)
August FHFA house price index: +0.3% (actual) vs. +0.2% (estimate)
October consumer confidence: 108.7 (actual) vs. 99.1 (estimate)
September JOLTS: 7,443,000 (actual) vs. 7,900,000 (estimate)
Happy trading!
Tom