
EB Daily Market Report - Wednesday, October 30, 2024
Executive Market Summary
- Futures were lower overnight and we gapped down at the opening bell
- We saw improvement in our indices, especially small caps, early in the trading session, but more weakness followed in the afternoon
- Commodities were mostly higher, especially the 2.51% jump in crude oil ($WTIC) to nearly $69 per barrel
- The 10-year treasury yield ($TNX) began the day dropping about 7 basis points, but finished near the unchanged level
- Sectors were bifurcated with 5 higher and 6 lower; Alphabet's (GOOGL, +3.81) earnings gave both internet ($DJUSNS, +1.51%) and communication services (XLC, +0.65%) a lift
- Technology (XLK, -1.50%), yesterday's winner, was easily today's loser; semiconductors ($DJUSSC, -2.06%) were a primary contributor to the weakness
- Q3 GDP was released and it came up a bit short of expectations; meanwhile, the ADP employment report was hotter than expected - all eyes will be on the Friday nonfarm payrolls report
- Garmin Ltd (GRMN, +23.14%) led all S&P 500 stocks after posting excellent quarterly results
Market Outlook
Bitcoin ($BTCUSD) challenged its all-time high near 74000 on Tuesday and, thus far, is being turned away at that key price resistance level:
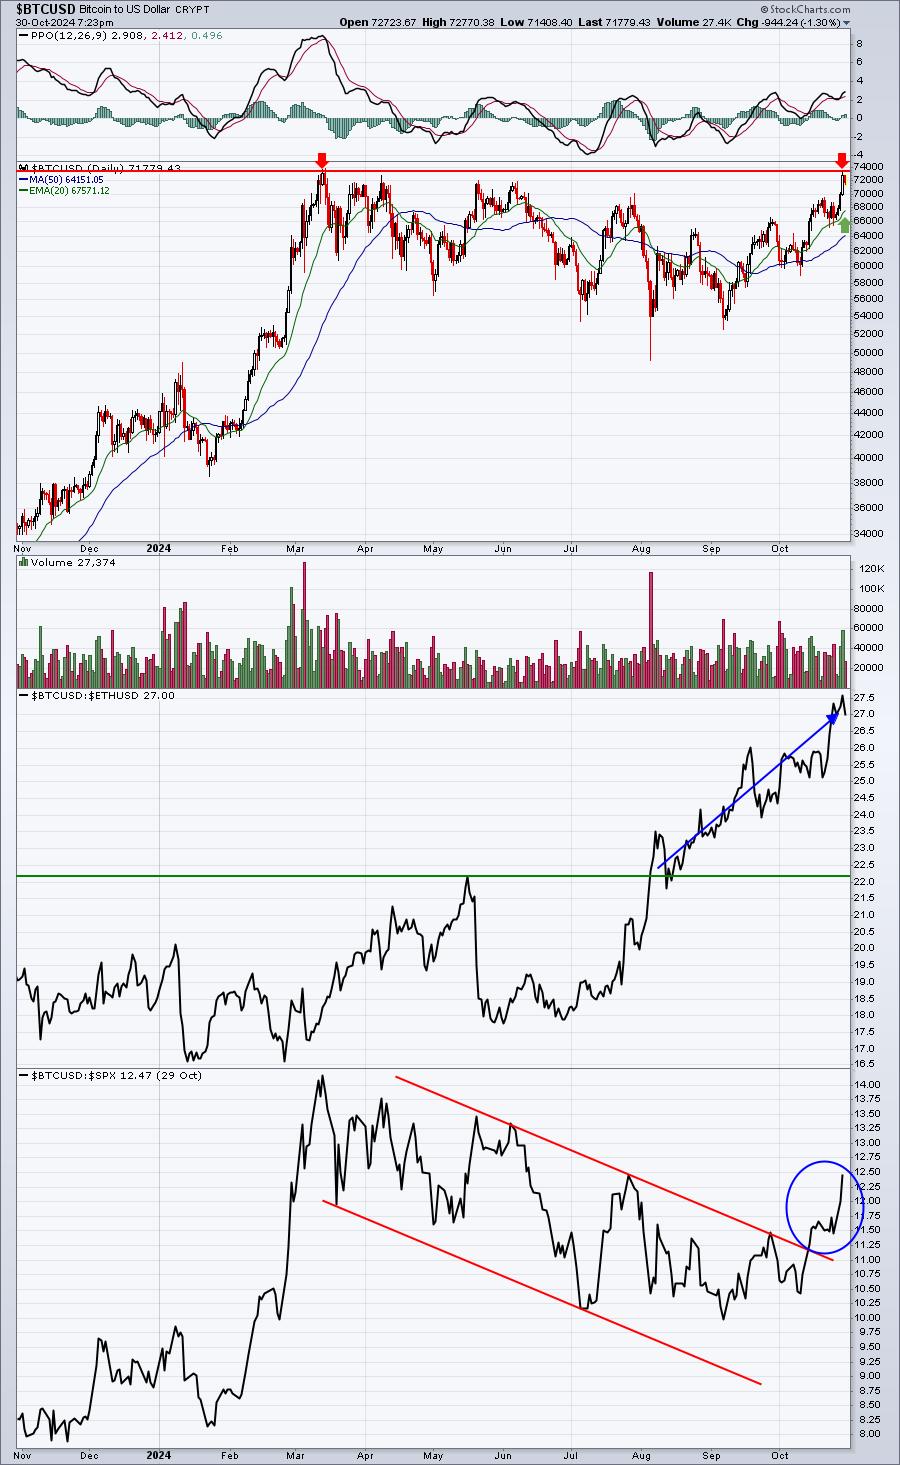
The red arrows mark the key price resistance, while the green arrow highlights the rising 20-day EMA. The two lower panels are interesting too, as bitcoin clearly is outperforming etherium ($ETHUSD). After months of underperforming the S&P 500, bitcoin has finally broken its relative downtrend channel and is now outperforming the S&P 500.
Sector/Industry Focus
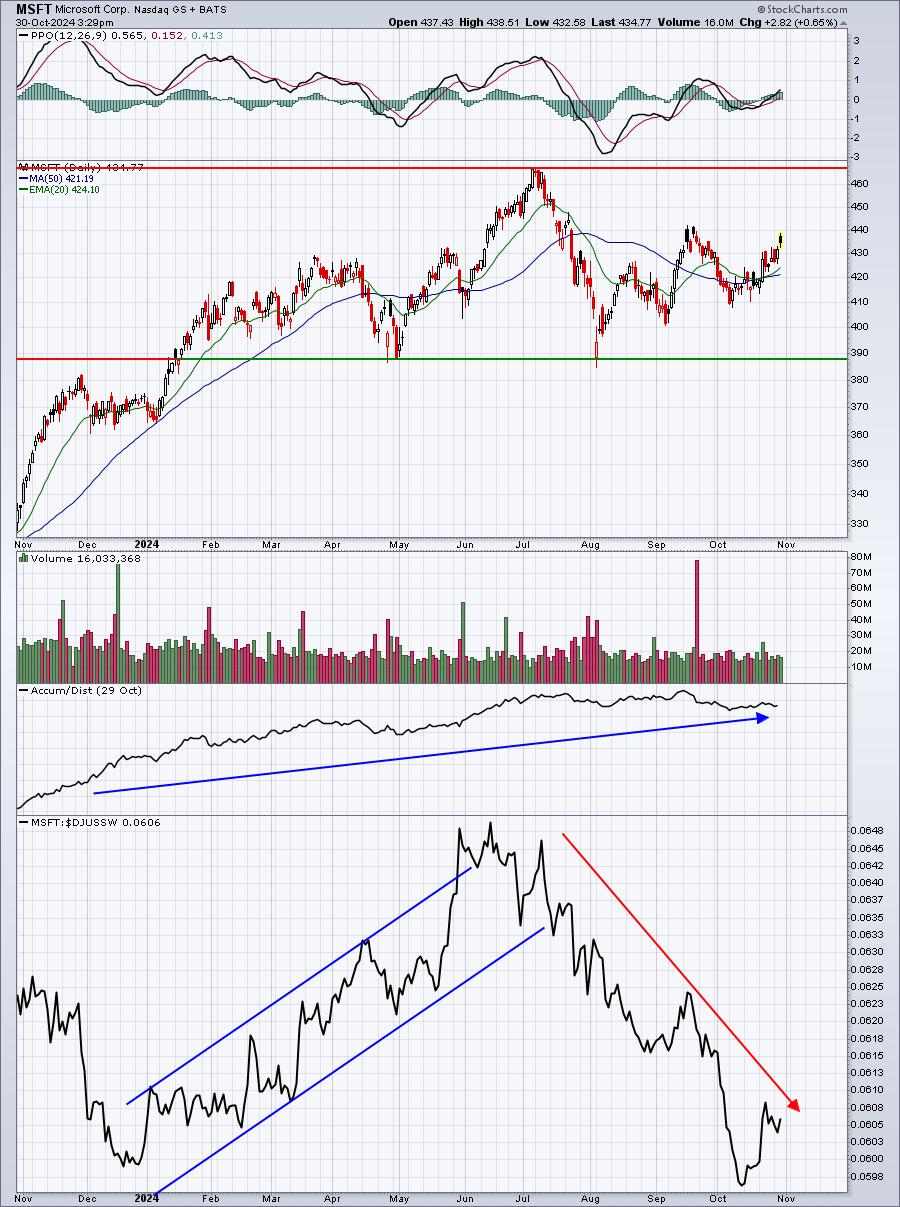
Two huge earnings reports will be released after the bell, one in software (MSFT) and the other in internet (META). META has been a clear relative strength winner, while the same cannot be said about MSFT:
MSFT:
META:
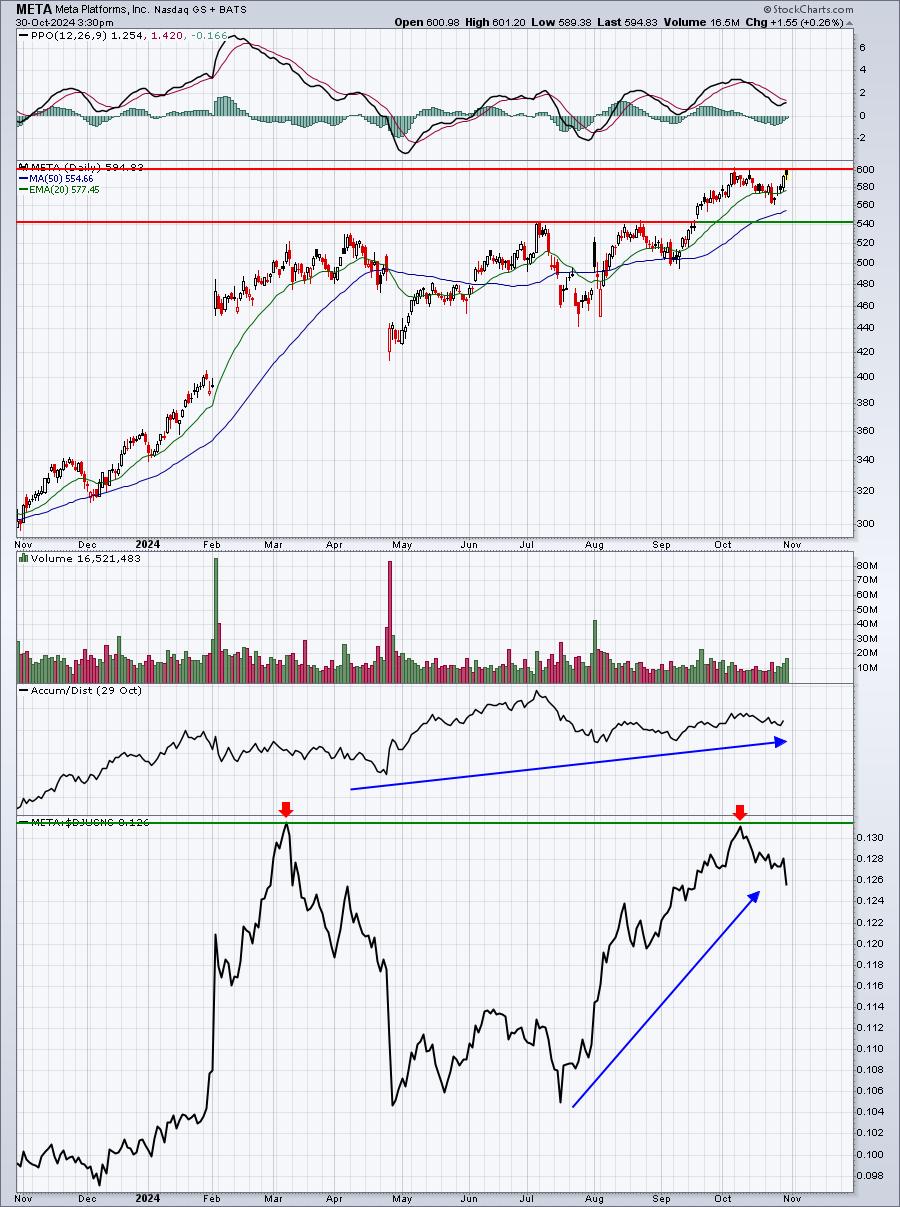
Both stocks remain in uptrends, but their relative strength varies considerably. We'll find out in the next few minutes whether relative strength/weakness leads to higher/lower price. I'd say Wall Street has favored META a bit more than MSFT, but both stocks are in industries that have been underperforming the S&P 500, though internet ($DJUSNS) did get a nice relative boost today from Alphabet's (GOOGL, +3.81%) reaction to its earnings report released on Tuesday afternoon.
ChartLists/Strategies
It was nice to see a couple gaps higher from two of our portfolio stocks, though a third (CMG, -7.85%) didn't give us the trifecta:
GRMN:
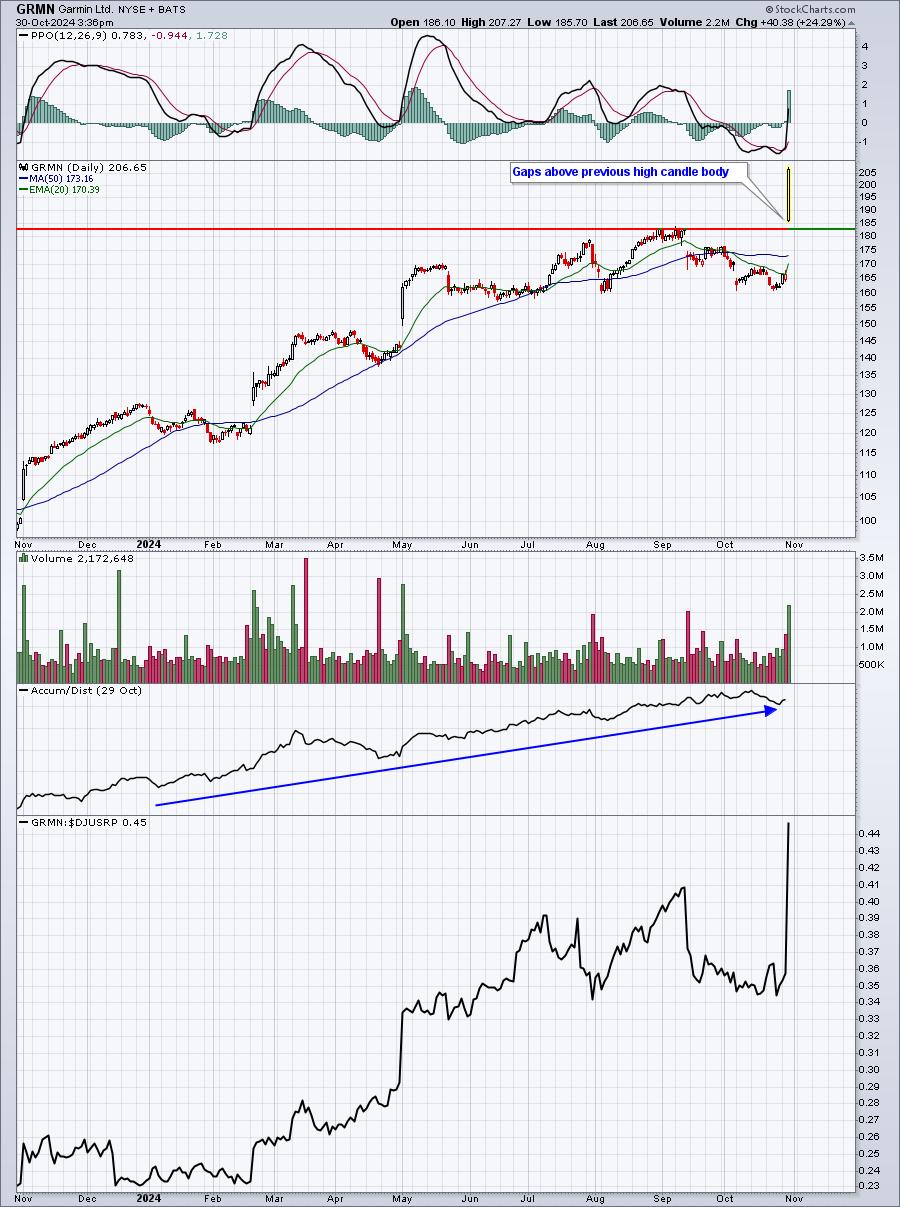
Both the AD line and relative strength remained fairly strong and we now see the quarterly results and GRMN's price reaction. I love stocks that gap up above key candle body resistance after reporting solid results. I believe it's a sign of more strength to come.
EXEL:
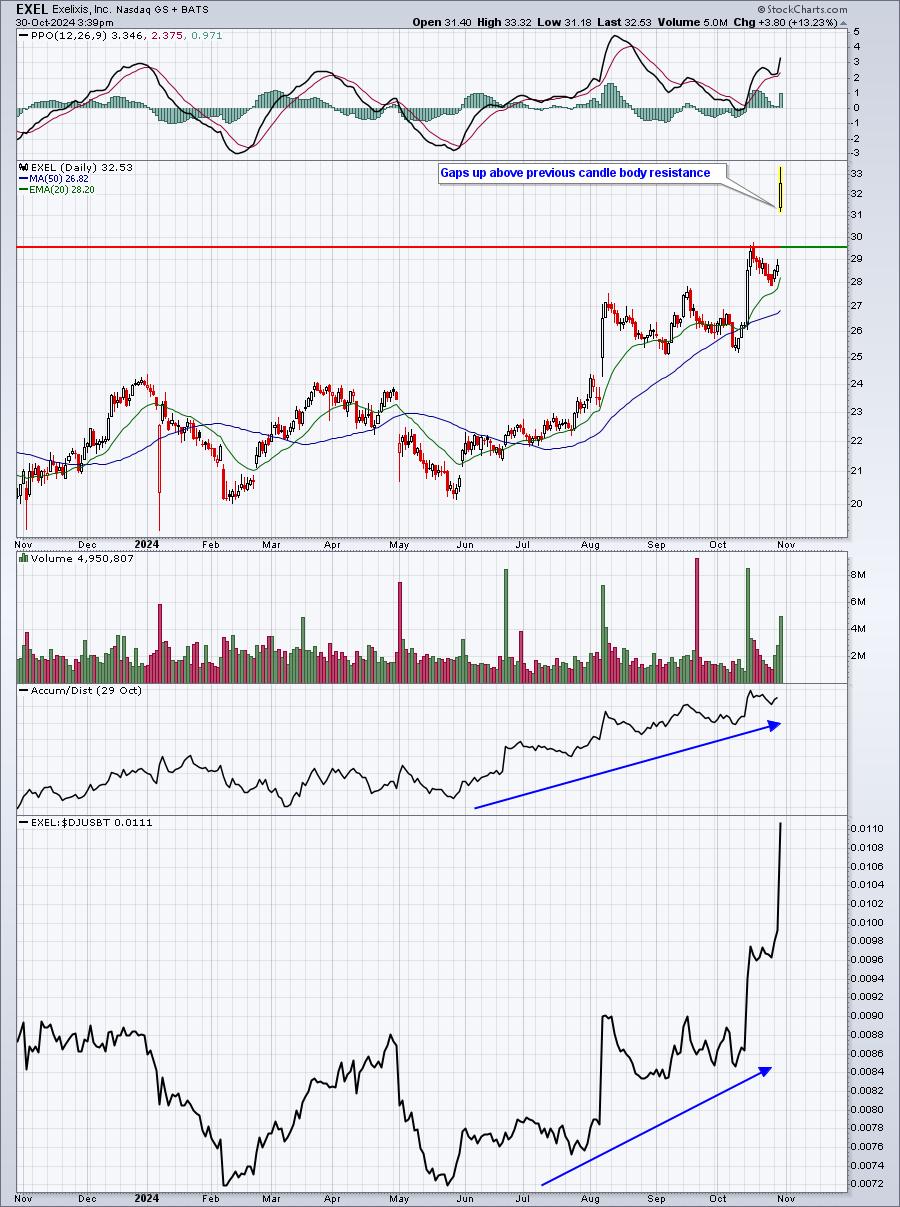
This chart setup looks quite similar, with a strong AD line and improving relative strength.
Earnings Reports
Here are the key earnings reports for the next two days. I include all companies with market caps of $10 billion or more and also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Wednesday, October 30 - after market close (AMC):
MSFT, META, AMGN, BKNG, SBUX, KLAC, EQIX, AFL, DASH, MET, PSA, COIN, ALL, PRU, AEM, MPWR, CVNA, ACGL, MSTR, CTSH, EBAY, EQR, AWK, VTR, HOOD, GDDY, INVH, CLX, LPLA, MAA, RYAN, GEN, EG, CF, UDR, FTAI, CW, CHRW, MGM, SFM, HLI, TWLO, FND, ROKU, COKE, SCI, OHI, PPC, OLED, PCTY, MUSA, PAYC, FRT, BIO, AUR, PCOR, ALTR, AR INFA, PEN, SPXC, AM, WSC, CFLT, SUM, AXS, CGNX, WTS, CWST, KRG, BECN, ETSY, MMSI, THG, MGY, TENB, ACHC, WHD, NXT, COLM, ACA, MATX, IRT, KMPR, AEIS, ALKT, AX, RIG, EPR, BNL, FORM, GRBK, CRK, HTGC, NSA, NVST, HCC, RIOT, BHC, RELY, PSMT, COMP, FCPT, HUBG, HWKN, RSI, IRTC, AIN, TRUP, MCW, GLPG, MYRG, CNMD, CMPR, TTMI, SIMO, CNX, TNK, TDOC, VRE, CODI, BHE, NVEE, STAA, LMND, MAX, DAWN, NMFC, ARI, EIG, ALGT, PGRE, IMAX, JBSS, PLSE, ERII
Thursday, October 31 - before market open (BMO):
MA, MRK, LIN, SHEL, UBER, CMCSA, TTE, ETN, COP, BMY, REGN, SO, ICE, CI, MO, PH, CNQ, ING, GWW, PWR, TAK, KVUE, IQV, LNG, STLA, AME, ALNY, IDXX, XEL, OWL, XYL, EL, WEC, CVE, WTW, ETR, K, LI, STM, RBLX, ASX, CMS, EME, BALL, APTV, IP, KIM, H, SN, INSM, TFX, LECO, MBLY, NCLH, SIRI, HII, GNRC, APG, OTEX, WCC, DINO, CFR, BWA, MIDD, GIL, ARW, NSIT, JHG, LAZ, LNC, IDA, VNT, FSS, DNB, LANC, BDC, ITRI, BGC, OGN, MDGL, AVNT, KTB, ALGM, PBF, WEN, IDCC, VAL, GVA, CNK, NSP, BTU, PATK, CWT, KYMR, TRN, AGIO, LAUR, UTZ, DRVN, SWI, PTON, PHIN, DFIN, CIFR, GEL, UPBD, SABR, UNIT, FDP, TVTX, CRAI, MGPI
Economic Reports
October ADP employment report: 233,000 (actual) vs. 115,000 (estimate)
Q3 GDP (initial estimate): 2.8% (actual) vs. 3.0% (estimate)
Q3 PCE - annual rate: 3.7% (actual) vs. 3.0% (estimate)
September pending home sales: +7.4% (actual) vs. +1.0% (estimate)
Happy trading!
Tom