
EB Daily Market Report - Tuesday, December 10, 2024
Executive Market Summary
- Futures were bifurcated overnight and our major indices opened in similar fashion
- After early morning strength in the S&P 500 and NASDAQ 100, they both reversed into negative territory
- Rotation has shifted back towards the Dow Jones and the small cap IWM, but all major indices are lower at this time
- The Volatility Index ($VIX) is flat today, despite the escalation of selling in the S&P 500 over the past few hours
- Communication services (XLC, +1.46%) is performing well, thanks to a jump in internet stocks ($DJUSNS, +2.38%)
- Consumer stocks are performing well, though staples (XLP, +0.39%) has taken the lead on discretionary (XLY, +0.26%)
- Technology (XLK, -1.87%) is struggling today, with semiconductors ($DJUSSC, -2.91%) under pressure again
- The 10-year treasury yield ($TNX) is up 2 basis points to 4.22%, ahead of the November CPI report, due out tomorrow morning
- Cryptocurrencies continued to slide as dogecoin ($DOGEUSD, -7.04%) and etherium ($ETHUSD, -3.16%) fell back; bitcoin ($BTCUSD, -0.20%) was closer to the flat line, but about 4% beneath 100,000 now
- Commodities were mixed with crude oil ($WTIC, +0.07%) essentially flat just above $68 per barrel
- Oracle (ORCL, -7.30%) reported results that didn't agree with Wall Street and fell beneath its 50-day SMA for the first time since August
Market Outlook
Lots of eyeballs will be on the November CPI report tomorrow morning, looking for any hint that inflation could be reigniting. As a reminder, here's what the Core CPI looks like:
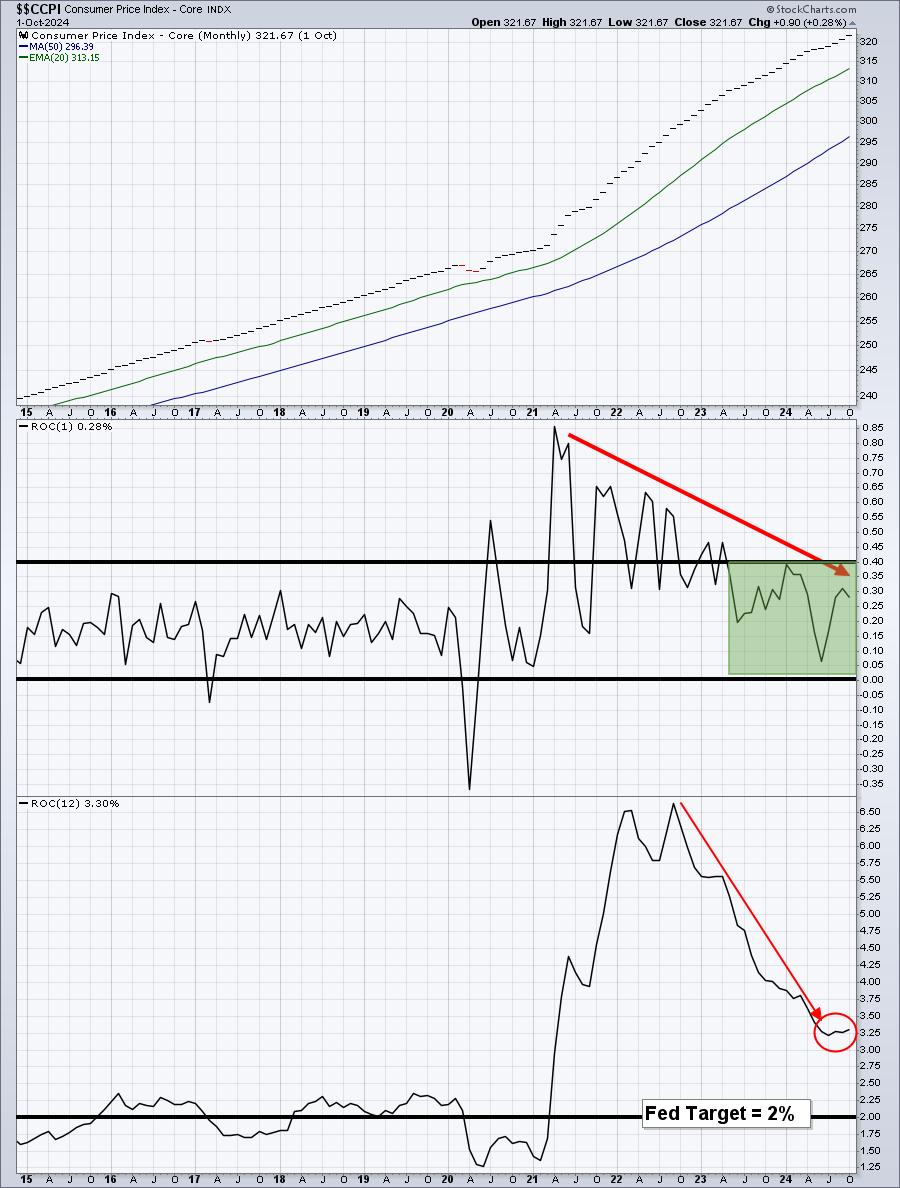
The 1-month rate of change (ROC) has historically been in the +0.0% to +0.4% range. You can see the green-shaded area above that highlights the "normal" readings since Q2 2023. So we're nearing two years' worth of normal 1-month ROC readings. But the red circle is what many bears will point to, saying that the "sustainable path" to the Fed's target rate of 2% is reversing. A big spike in the November Core CPI report could begin to sway others as well. Knowing this can be a difficult week for the stock market (historically), a surprise to the upside on Wednesday morning likely wouldn't be received well. I just don't believe we'll see a spike above the current +0.3% expectation for Core CPI.
We'll find out tomorrow.
Sector/Industry Focus
I mentioned that the internet group ($DJUSNS) was outperforming today and this group has shown a lot of life lately. Keep in mind that the DJUSNS LOVES the month of January. Check out its relative seasonal chart:
Internet
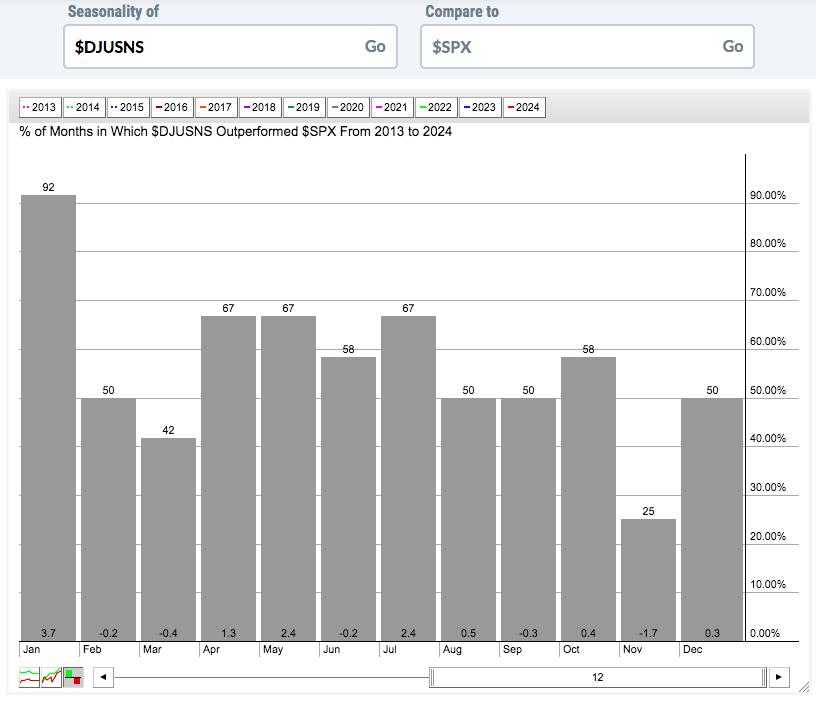
Since the current secular bull market was confirmed in 2013, the DJUSNS has risen in over 90% of Januarys and it clearly shows its most relative strength vs. the S&P 500 in January. This is when we should expect to see big moves in many internet stocks. Netflix (NFLX), for one, tends to FLY in January heading into its Q4 earnings report, which is typically released in January.
ChartLists/Strategies
I think it remains prudent to watch the action for now, from a trading perspective. I realize that many stocks could spike tomorrow if the November Core CPI comes in below expectation, but this is a period of December that generally results in little or no gains. We'll have plenty of opportunities later in December and in 2025, if the CPI data is tame, so I'm personally in no hurry to put on additional trades in aggressive areas.
Earnings Reports
Here are the key earnings reports for the next two days. I include all companies with market caps of $10 billion or more and also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, December 10 - after market close (AMC):
GME, PLAY
Wednesday, December 11 - before market open (BMO):
BZ, PLAB, REVG
Economic Reports
Q3 productivity: +2.2% (actual) vs. +2.2% (estimate)
Q3 unit labor costs - annual rate: +0.8% (actual) vs. +1.9% (estimate)
Happy trading!
Tom