
EB Daily Market Report - Thursday, December 18, 2025
Executive Summary
- Futures were higher overnight after a strong earnings report from Micron Technology (MU, +11.85%)
- A benign November CPI report aided futures and we opened with a very strong start
- The rally fizzled throughout much of the day and our major indices are mostly close to where they opened
- Consumer discretionary (XLY, +1.84%) and technology (XLK, +1.82%) led 8 of 11 sectors higher
- Energy (XLE, -1.32%) gave back much of Wednesday's gains despite crude oil ($WTIC, +0.20%) clinging to a small gain
- Cryptocurrencies are down across the board with solana ($SOLUSD, -4.32%) hit hard
- Bitcoin ($BTCUSD, -1.18%) is testing important support near the 85,000 level
- The 10-year treasury yield ($TNX) dipped 3 basis points to 4.11% after the tame inflation data
- MU led a strong semiconductor group ($DJUSSC, +2.46%)
- Meanwhile, Starbucks (SBUX, +5.42%) is among today's S&P 500 leaders, potentially closing at its highest level since mid-August
Market Outlook
Economic news out on Thursday morning provided the bulls a ton of hope, but if I'm being honest, the reaction today is not really that bullish at all. Yes, our major indices gapped up and are currently higher. But there's been zero follow through after the morning gap.
At 8:30am ET on Thursday, initial jobless claims came in just below expectations and reversing last week's surprising increase. That should help to allay fears of a rapidly-worsening jobs picture. Furthermore, the November CPI report came out and was flat, well below the expected +0.3% rise. That left the annual Core CPI rate at 2.7%, instead of the forecasted 3.1%. That was great news on the inflation front.
We could not have received better news. The jobs and economic picture improved, as did the inflation picture. Either of these developments should have resulted in massive improvement in growth stocks (IWF), especially relative to value stocks (IWD). First, let me be clear. The IWF has definitely outperformed the IWD. But there remains a TON of work to do to improve this relative ratio to support another meaningful rally in the S&P 500. This chart tells me this reaction did very little to help sustain an S&P 500 rally:
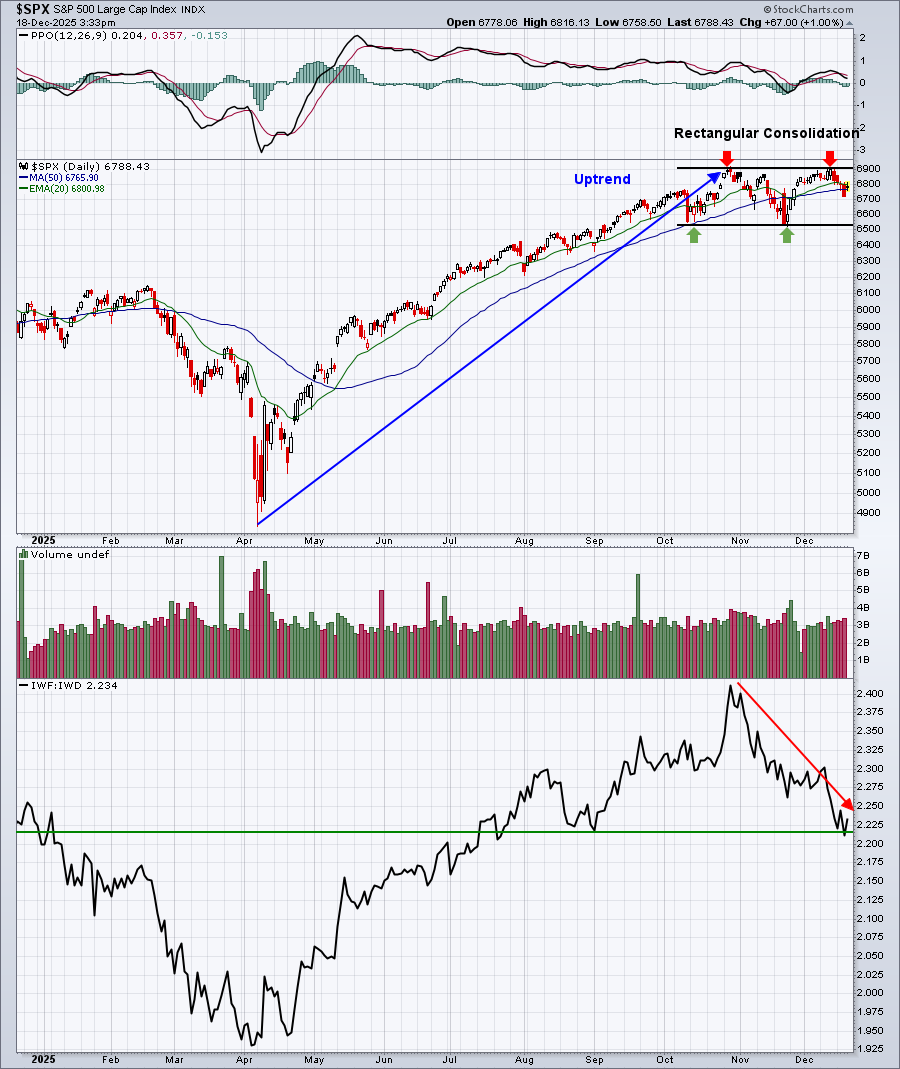
The good news is that we saw a bounce in the IWF:IWD ratio. But given all the positive fundamental news, it certainly doesn't look like it was enough to me. But I'll keep following the relative performance of various areas of the market in the days and weeks ahead and will let you know if I see any changes in my current cautious market stance.
Sectors/Industries
Another troubling response today was from banks ($DJUSBK), which typically move solidly higher when it appears that new fresh fundamental data supports a future rate cut. The lack of any inflation whatsoever at the consumer level would normally result in buying of bank stocks. So why is the DJUSBK down and the regional bank ETF (KRE) up just fractionally?
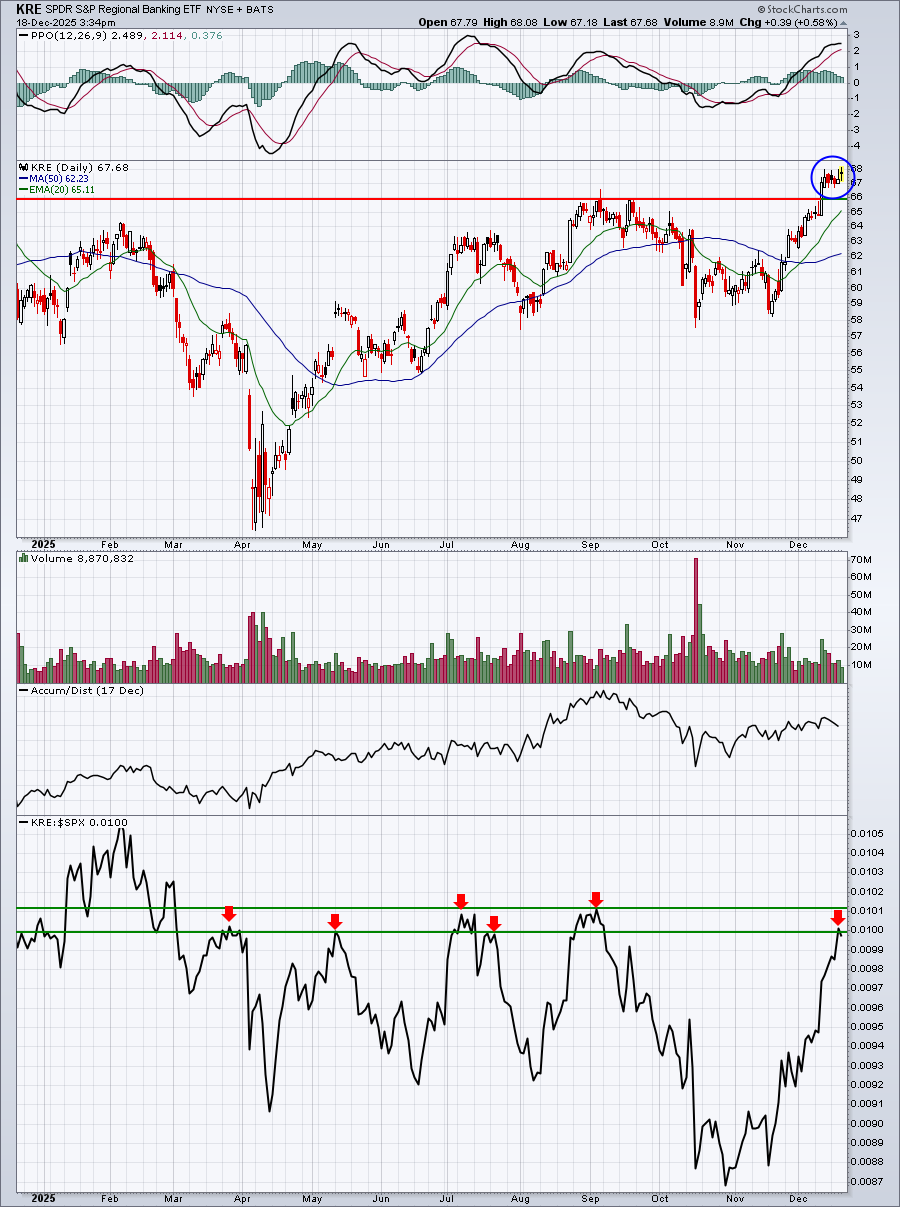
The KRE is in breakout territory, but I'd really like to see a relative breakout in the bottom panel. And I especially would've liked to have seen the KRE outperform the S&P 500 on a dovish inflation report day.
But it is what it is.
ChartLists and Trading Strategies
I tend to avoid shorting during secular bull markets and I do still believe that we're in a secular bull market. However, if I did short, I'd look for short positions where I could keep a very tight stop and a false breakout occurs with a negative divergence. One such stock, to give you an example, would be Ralph Lauren (RL):
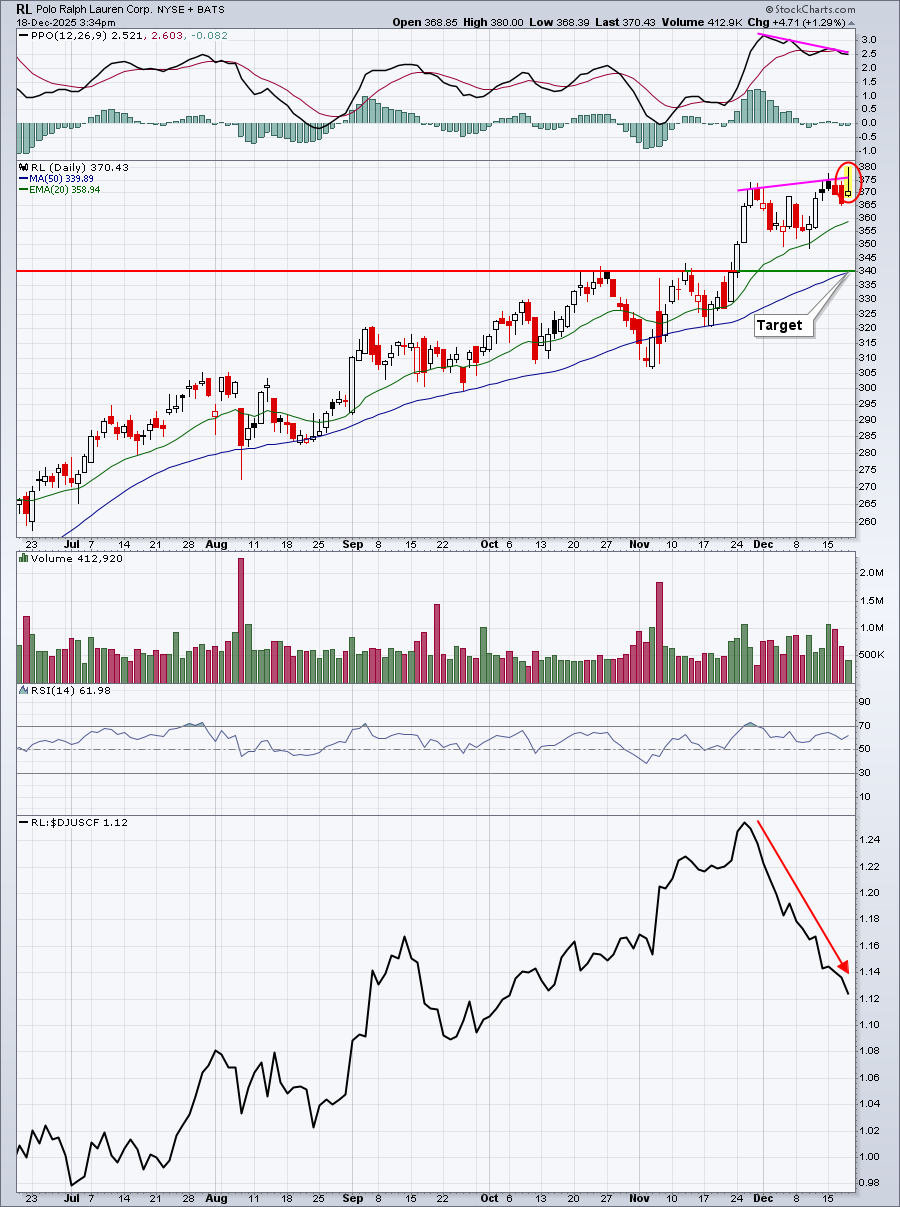
RL's relative strength is rapidly fading and you can place a very tight intraday stop above 380. The negative divergence tells me that there's an increasing chance of a 50-day SMA test, as opposed to just a 20-day EMA test. That increases the potential reward vs. what would be a very tight stop above Thursday's intraday high.
Upcoming Earnings
We are now waiting until Q4 earnings season kicks off in mid-January before publishing our Upcoming Earnings ChartLists and Upcoming Earnings Relative Strength ChartList.
Economic Reports
Initial jobless claims: 224,000 (actual) vs. 225,000 (estimate)
November CPI: +0.0% (actual) vs. +0.3% (estimate)
November Core CPI: +0.0% (actual) vs. +0.3% (estimate)
December Philadelphia Fed manufacturing survey: -10.2 (actual) vs. 3.6 (estimate)
Happy trading!
Tom