
EB Daily Market Report - Brief Update - September 24, 2026
Interest rates continue to press higher as the 10-year treasury yield ($TNX) finished today at 5.16%. The TNX closed out August at 4.76%, so we've tacked on another 40 basis points this month thus far. I've wondered how U.S. equities would handle a surge in the TNX through 5.00%. I'd say better than expected to this point. The S&P 500 bounced off its rising 20-day EMA, currently at 7674, and is trying to close above 7700, barely more than 1% off its all-time intraday and closing highs. That's fairly remarkable, in my opinion.
Small caps (IWM) have struggled with the rising rates, however, as this asset class now resides more than 7% off its all-time high. So not all U.S. stocks have escaped. The IWM is trying to carve out a potential short-term bottom, holding onto key support from early June:
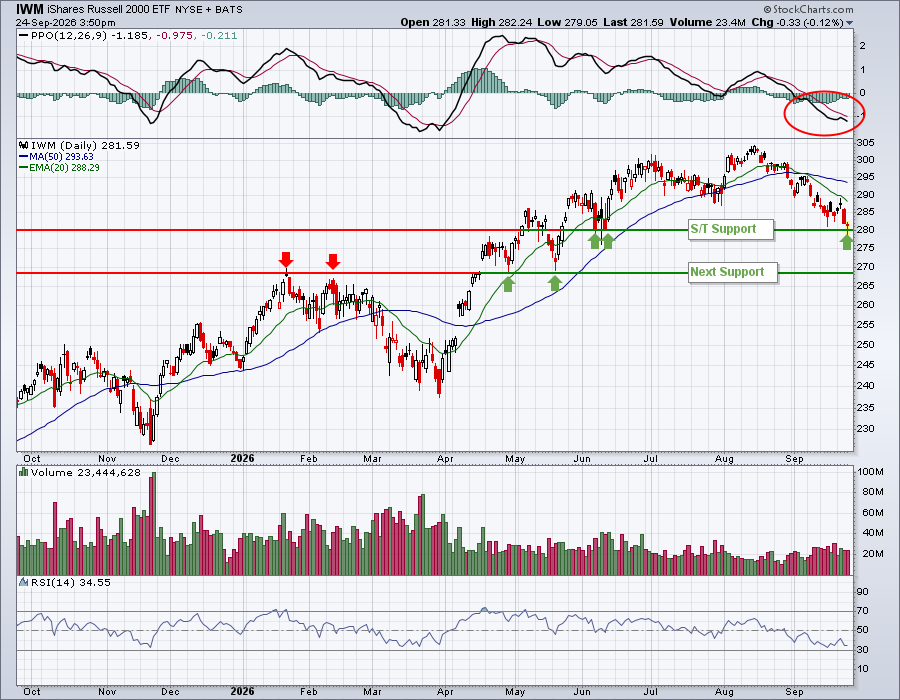
The daily PPO is very weak, so any bounce, if one occurs, is likely to be short-lived. Perhaps we could see a bounce from here back to test the now-declining 20-day EMA. Money is rotating towards large-cap stocks, while smaller companies are mostly distributed.
8 of 11 sectors are down on the session. Communication services (XLC, +1.19%) is bucking the trend. One component industry, internet ($DJUSNS) is leading this sector and threatening a breakout:
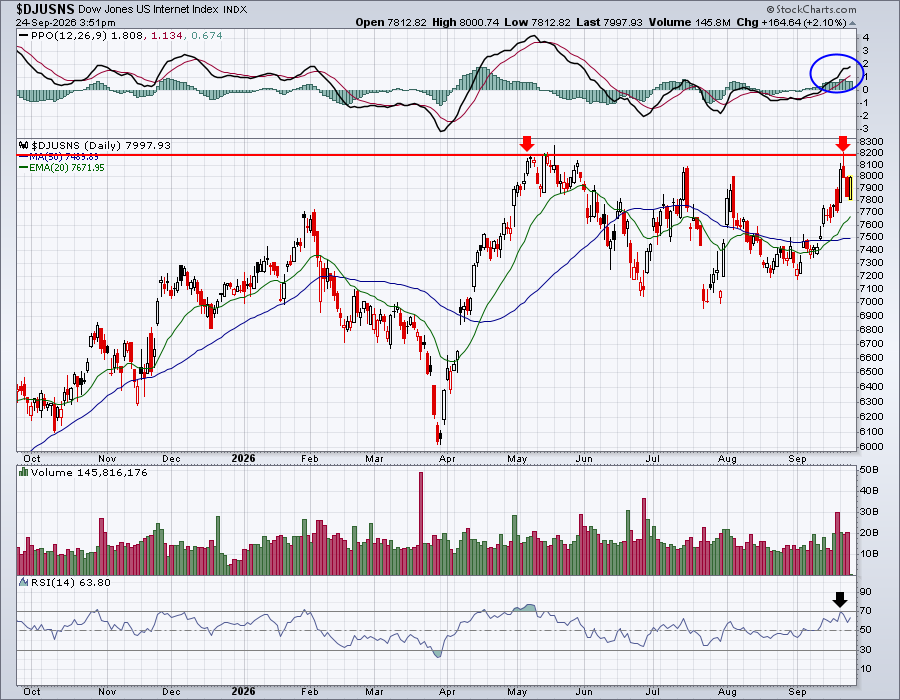
The daily PPO on internet stocks is rapidly accelerating, a very bullish development. If it were any other month besides September, I'd be pounding the table on this group. It tends to lead secular bull markets, so rotation could certainly favor this group in Q4.
The poor absolute performance in defensive sectors, especially consumer staples (XLP), utilities (XLU), and real estate (XLRE) suggest to me that this market is going HIGHER in time. Wall Street is NOT moving into more cautious areas, so neither should we.
Patience will pay off for the bulls, in my opinion.
Happy trading!
Tom