
EB Daily Market Report - Wednesday, October 14, 2026
Special Note
I will be traveling out of town on Friday morning and won't be back until late Sunday. So there'll be a few changes this week. First, the Weekly Market Recap video will be recorded on Thursday after the close, rather than the usual Friday after the close. Second, I am going to try to get all of our ChartLists updated on Thursday (to be available to all members by Friday morning). That means our cutoff for inclusion into our ChartLists will be today.
Executive Summary
- Futures were mixed overnight, but quickly turned negative after the September Core CPI was reported higher than anticipated, +0.3% vs. +0.2%
- Small caps (IWM, -2.22%) have been hit particularly hard, as we would have expected given the higher inflation number
- Interestingly, the 10-year treasury yield ($TNX) immediately surged higher by 11 basis points to 5.33% on the news, but has since moved into negative territory, falling 3 basis points to 5.19%
- Earnings have mostly exceeded expectations these first couple days, but most companies are selling off after earnings
- Large cap growth (IWF, -2.44%) has performed very weak, especially relative to large cap value (IWD, -0.39%)
- Technology (XLK, -2.99%) and communication services (XLC, -1.42%) are leading sectors to the downside
- 2 sectors are advancing - health care (XLV, +2.40%) and consumer staples (XLP, +1.86%)
- Semiconductors ($DJUSSC, -3.84%) are adding to their recent selloff - more on this group below
- Cryptocurrencies are extending the selloff in "risk on" assets, as bitcoin ($BTCUSD, -1.82%) drops back to 81,600
- Gold ($GOLD, -1.47%), and especially silver ($SILVER, -6.27%), are extremely weak, despite higher-than-expected inflation data
- Crude oil ($WTIC, +0.90%) has edged up to $95 per barrel
- Dell Technologies (DELL, -11.63%), one of 2026's growth "darlings", is trading beneath its 50-day SMA on rising volume
Market Outlook
It's hard to imagine the Fed giving up its rate-hiking campaign after the September Core CPI today rose 0.3%, topping the 0.2% expected rise. The odds of an October rate hike immediately jumped from roughly a 20% chance of a quarter-point hike to a coin toss, or 50%. It'll be very interesting to see how the odds fluctuate prior to the next Fed meeting on October 27th and 28th, given the fact that there'll be no further jobs or inflation reports. The PCE Index, a favored inflation indicator by the Fed, isn't out until just after the Fed meeting.
The Volatility Index ($VIX, +12.97%) is experiencing its largest one-day rise since June 5th. Resistance on the VIX has been at 18 over the past 2 1/2 months. Closing above this level would indicate a very nervous market in the near-term, which can lead to rapidly-increasing losses. While I do not view any of the weakness to be problematic for long-term investors, short-term traders should absolutely be more cautious currently.
Sectors/Industries
Semiconductors ($DJUSSC) are the heaviest-weighted industry in the S&P 500, and 2nd place isn't particularly close. So when semis struggle, it takes a toll on our benchmark index. While the S&P 500 has handled semiconductor weakness pretty well over the past week, that's not the case today, with the S&P 500 down roughly 1.40%:
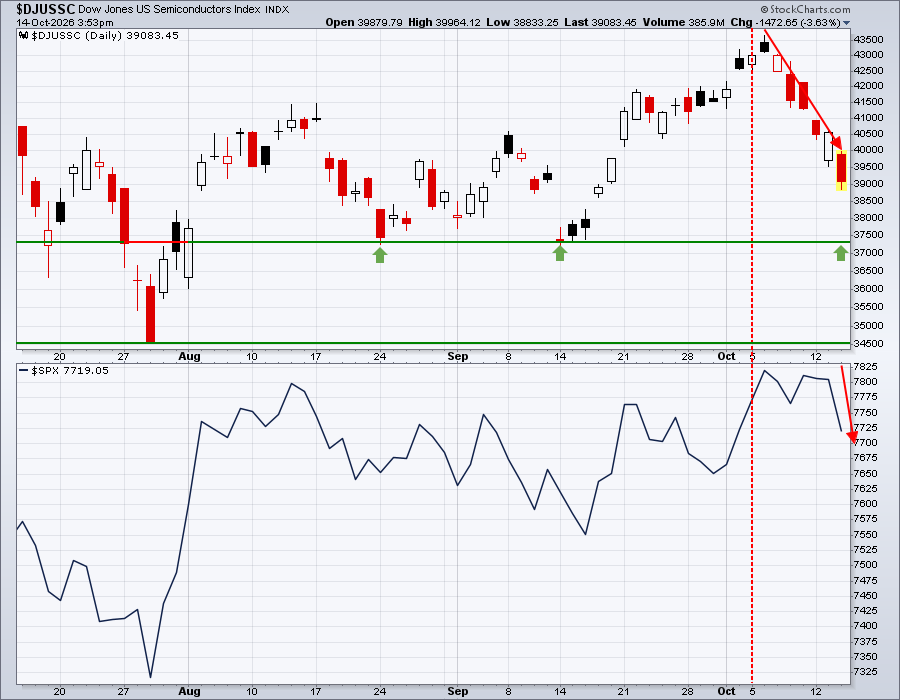
I've annotated the next couple levels of key price support on the DJUSSC, IF we do see continuing short-term weakness and rising volatility.
ChartLists and Trading Strategies
We focus on a lot of growth stocks in both our Portfolios and our ChartLists. When we see growth stocks trounced, like they've been over the past several trading sessions, it definitely makes sense to keep stops tight, or to avoid these stocks altogether. Personally, I don't need to catch the ultimate bottom. That would be great, but a lot of money can be lost trying to tell the stock market when the short-term bottom is in.
The inflation data today was not good. It doesn't change my longer-term view on inflation as even inflation hedges like gold (GLD, -1.46%) and real estate (XLRE, -0.79%), are not performing well today. Money is NOT rotating in a fashion that would suggest that inflation is a long-term problem. Still, we cannot ignore the short-term impact of potentially-higher treasury yields.
Upcoming Earnings
Upcoming Earnings and Upcoming Earnings Relative Strength ChartLists are produced for EB.com members to track upcoming earnings reports and provide them to you via ChartLists throughout earnings season. We started including those on our website THIS WEEK, so please feel free to check them out.
Economic Reports
September CPI: +0.6% (actual) vs. +0.6% (estimate)
September Core CPI: +0.3% (actual) vs. +0.2% (estimate)
Fed beige book released
Happy trading!
Tom