
EB Daily Market Report - Brief Update - Tuesday, October 27, 2026
Historically-speaking, today's close marks the end of the worst week of the year, dating back to 1950 on the S&P 500. This isn't my opinion or a trend over the past few years. This is an absolute fact based on the S&P 500's performance over 76 years. The October 21st close through the October 27th close is worse than any other similar 6-day or 7-day period in the calendar year, based solely on annualized returns.
....and there's more good news. The next week to 10 days is among the best periods of the entire year. The S&P 500 has produced annualized returns of +67.29% from the October 27th close through the November 5th close. The NASDAQ's annualized return for this period is +80.25% (since 1971) and includes November 6th. The small cap Russell 2000 also includes November 6th and has posted even better results, producing annualized returns of +90.29% since 1988.
Keep in mind that I never look at seasonal tendencies as guarantees. I don't consider seasonality to be a primary indicator, either. But we are in a secular bull market and we've been consolidating in rather bullish fashion, so moving higher from here would not be a surprise to me at all.
Today, the NASDAQ is up over 1% and leading our major indices higher. Technology (XLK, +1.64%) is the only sector gaining more than 1% today and leadership from this sector is almost always good news for the bulls. Renewable energy ($DWCREE, +5.06%) is having an excellent session. There is a positive divergence on this group's daily chart, so I'd be looking for more short-term strength, perhaps to test its 50-day SMA, which is still another 8% or so higher than current price.
Consumer discretionary (XLY, +0.94%) is strong today and continues to heat up, more good news for those in the bullish camp. Recreational services ($DJUSRQ, +5.81%) are jumping, as Royal Caribbean (RCL, +7.61%) beat both revenue and EPS estimates. The key to the discretionary group, however, is that both Amazon.com (AMZN, +1.67%) and Tesla (TSLA, +3.71%) are rising. Their collective weighting in the XLY, well above 40%, overshadows the fact that only 5 of 21 industry groups in the discretionary sector are higher. The chart on TSLA looks solid and I see it moving higher to test overhead price resistance near 450:
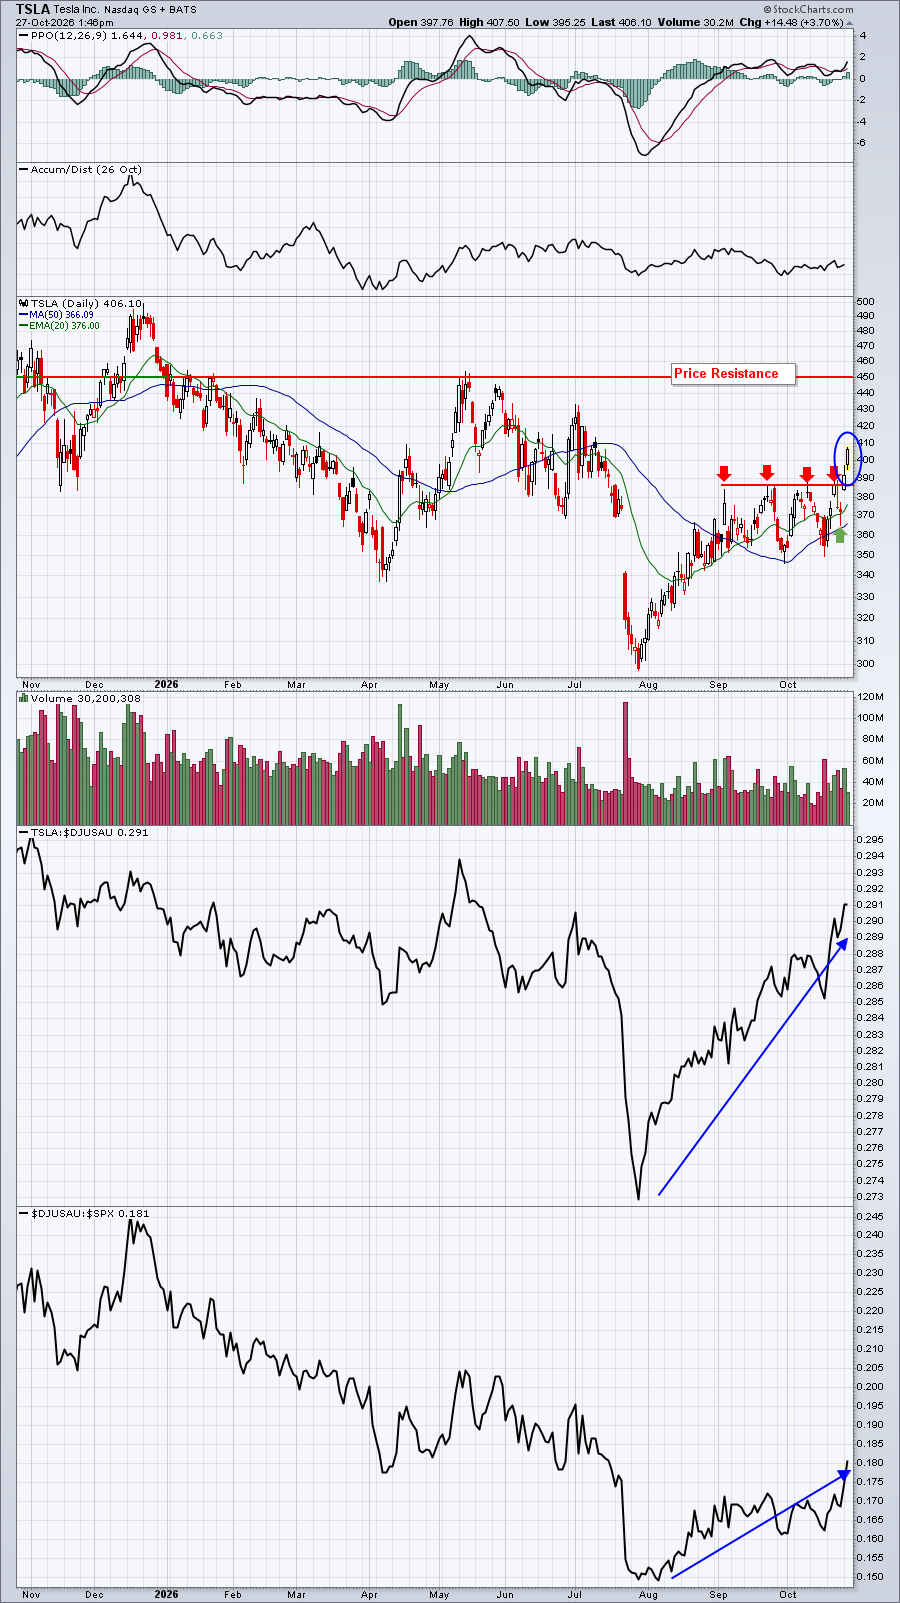
I'd keep an eye on the now-rising 20-day EMA for support during this advance. TSLA has been improving its relative strength vs. autos ($DJUSAU) over the past few months and now the entire group is strengthening vs. the benchmark S&P 500. This bodes well for TSLA.
The 10-year treasury yield ($TNX) is flat today and remains well below its recent high. As I've said recently, I believe the TNX topped. It'll have to prove me wrong.
Meanwhile, the Volatility Index ($VIX) is down roughly 15% from its high on Friday morning, when we saw our major indices hitting their October 2026 low. A continuing drop in the VIX would add to the Q4 bullishness.
Crude oil prices ($WTIC, -1.94%) have pulled back to just below $100 per barrel.
That's it for today. After the close today, and beginning at 5:00pm ET, we'll be hosting a FREE LiveStream event, "Q3 Earnings", where I'll discuss a few seasonality topics related to earnings, along with the look of earnings season thus far, pointing out companies that have already reported solid results and several that appear to be setting up for great results ahead. Room instructions will be mailed out separately. I hope you're able to join me!
Happy trading!
Tom