
EB Weekly Market Report - Monday, January 13, 2025
ChartLists Updated
There were no ChartLists updated over the weekend as earnings season is just about to start. Q4 earnings will kick off with JP Morgan (JPM) and many financial stocks' earnings later this week and then the number of earnings reports will accelerate over the next 3-4 weeks. I expect that earnings will once again be strong, but I'm sure most market participants will be interested in forward guidance as well, given the backdrop of higher interest rates (10-year treasury yield, or $TNX) and the uncertainty over inflation.
Weekly Market Recap
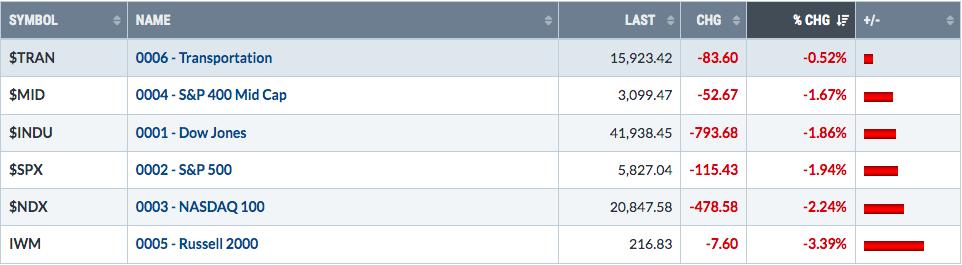
Major Indices
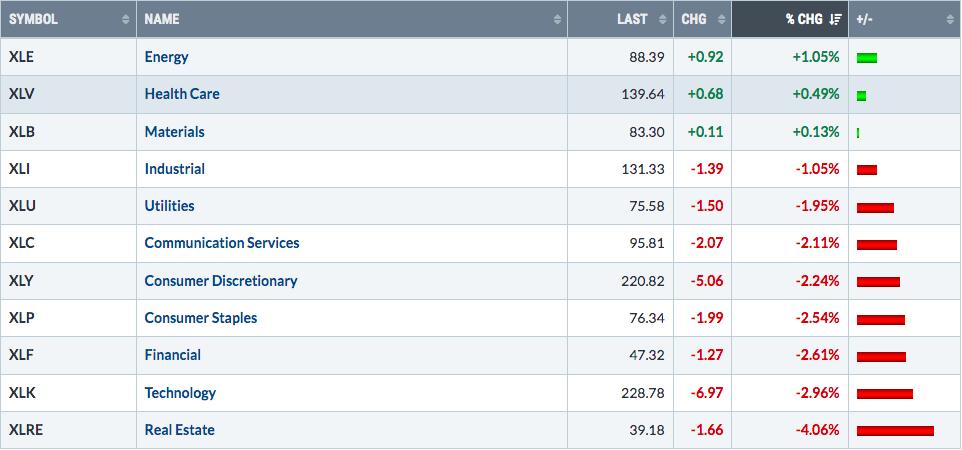
Sectors
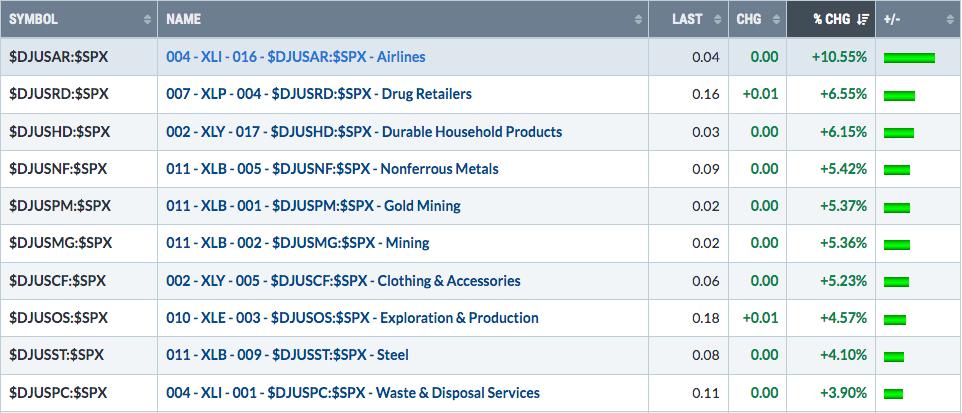
Top 10 Industries Last Week
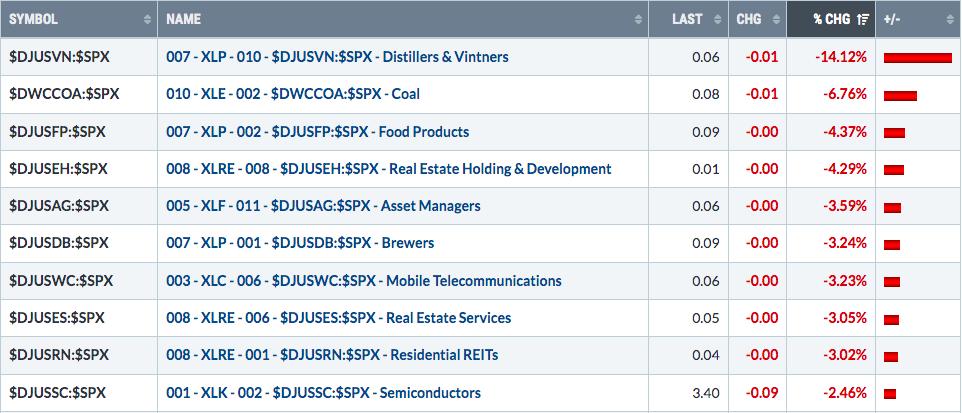
Bottom 10 Industries Last Week
Top 10 Stocks - S&P 500/NASDAQ 100
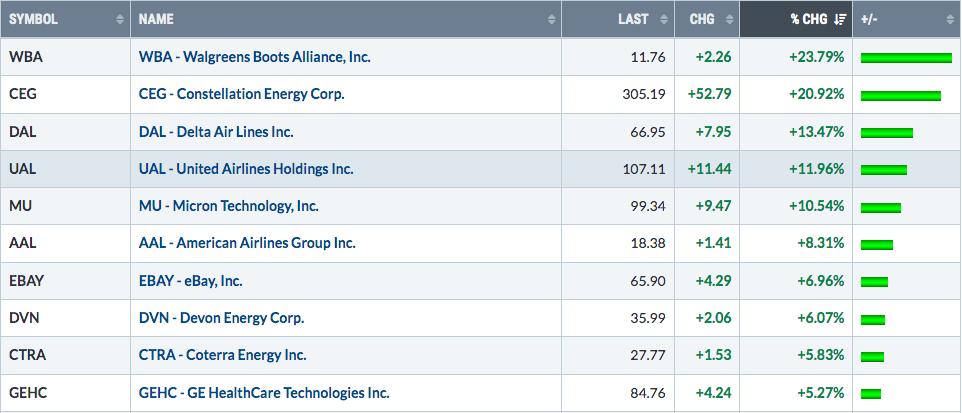
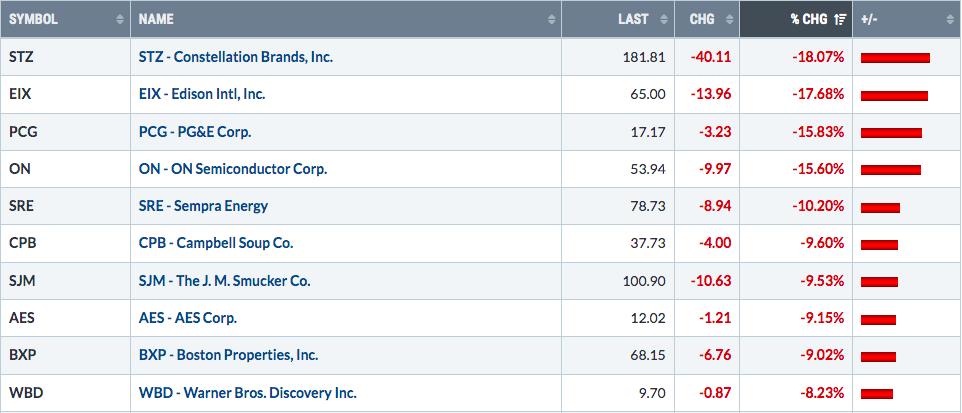
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
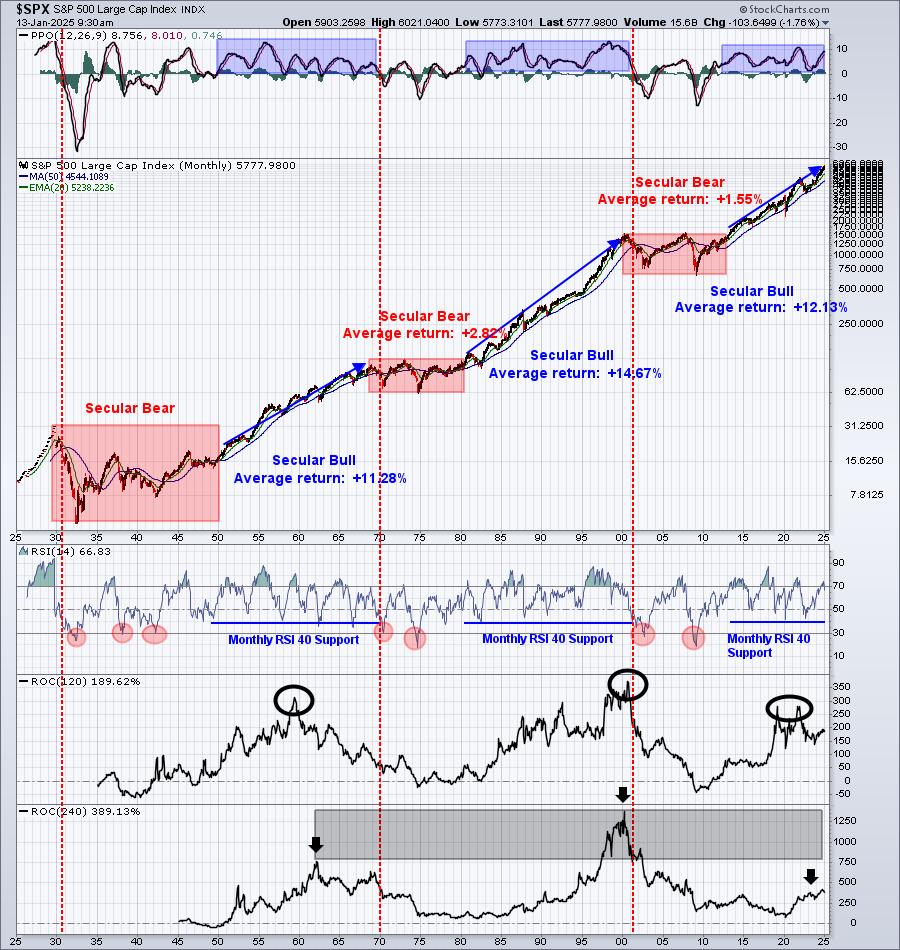
During periods of uncertainty, like the one we're in currently, I find the above chart very comforting and reassuring that being long is the right side of the trade. We go through many periods of market turmoil and hesitation, but a secular bull market tends to remedy those stresses over time. I expect the current period of uncertainty to be no different - ending with a positive and bullish resolution.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
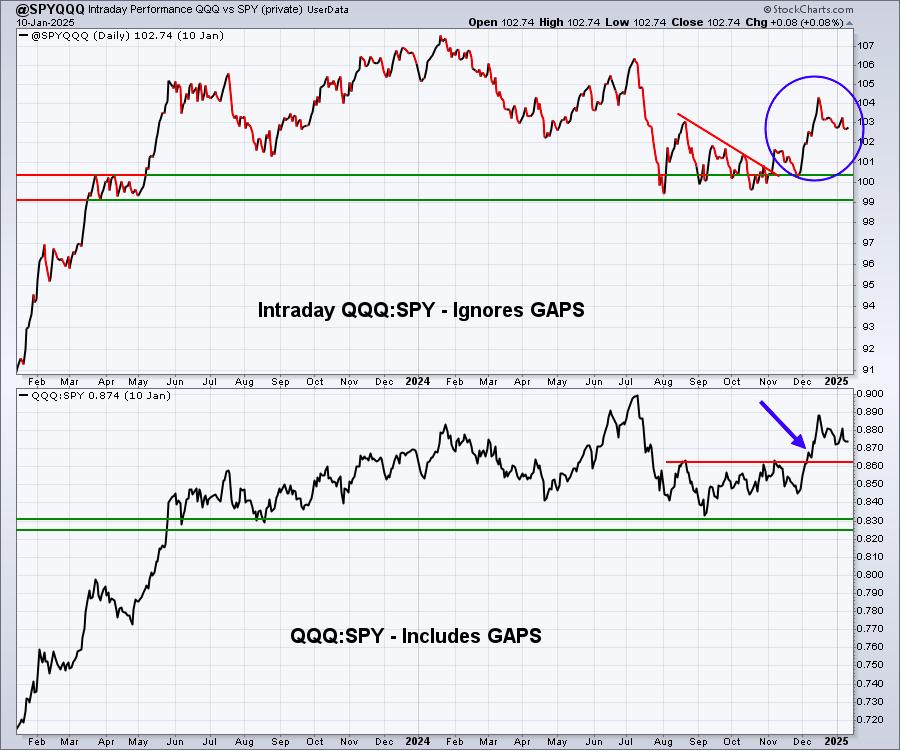
Any time the stock market grows restless and the media begins ranting about something negative, I rely on many of my "beneath the surface" signals. Sustainability ratios are among those types of signals. The QQQ:SPY ratio has weakened since mid-December, but in no way would I look at the above chart and think "breakdown". In fact, I believe we're still trending higher since the early-September low.
IWM:QQQ
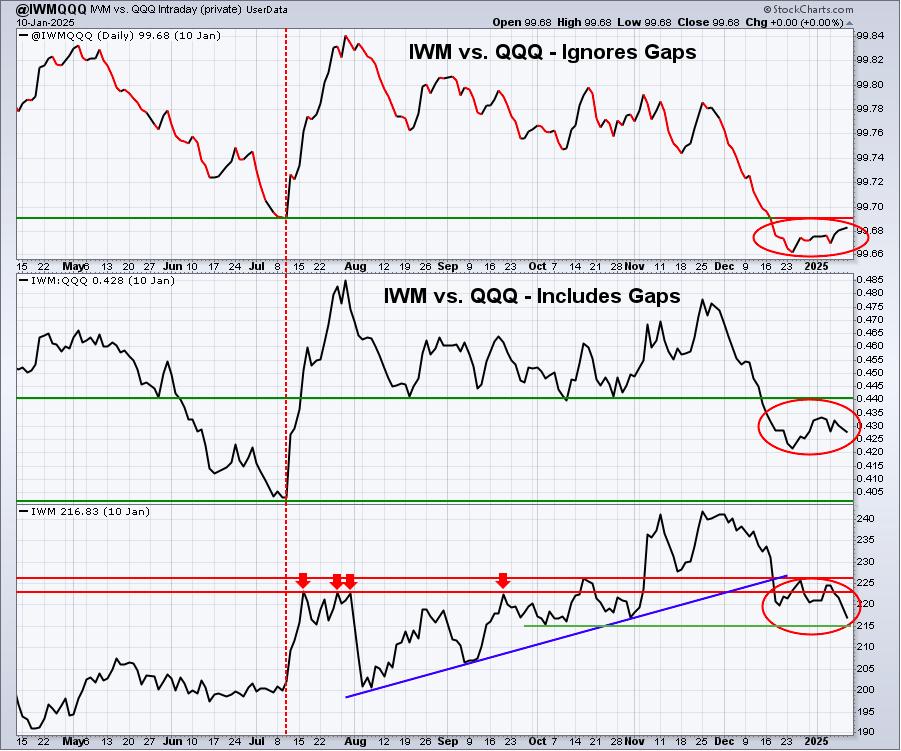
Because I've been so bullish small caps the past year or so, this is a chart that I review frequently. I can't sugar coat it, the IWM has been outperforming badly of late and much of its underperformance, in my opinion, is tied to the higher treasury yields. The 10-year treasury yield ($TNX) was 4.15% during the first week of December. It's 4.79% now, just 6 weeks later. Since that bottom in the TNX, the small cap IWM has fallen 9.24% vs. the SPY and QQQ drops of just over 4%.
I don't believe this underperformance continues, because I'm of the opinion that the inflation talk right now is nothing but a lot of noise. However, I cannot deny the recent weakness in the IWM, both absolute and relative. The IWM is at a key level on its price chart. Failure to hold onto price support in the 214-215 area would be problematic and could lead to much more selling in the IWM. Currently, I'm trading the IWM like it's bottomed with this morning's double bottom near 214. Personally, I've taken a much more aggressive position in this space, substituting the TNA for the IWM. This is VERY AGGRESSIVE and is simply not suggested for many of our members. You have to take on a lot of risk to rotate into the triple-leveraged ETF (TNA). The high Volatility Index ($VIX) and the possibility of a further breakdown in the IWM could set up the TNA for a BIG drop, but this is where I waited to pull the trigger. If we close at the lows of the day, I'll exit all leverage. If I'm right, this could be a MAJOR bottom in the IWM, one in which the TNA could be quite rewarding. I really want to emphasize the much higher risk that I'm taking, however.
It's also VERY important to note that we have two key inflation reports that will be released the next two days. On Tuesday morning, we'll get the December Core PPI (expected reading: +0.3%) and on Wednesday morning, we'll get the December Core CPI (expected reading: +0.2%). If these reports come in hotter than expected, I'd expect to see the TNX gap higher and U.S. equities gap lower. Again, I'm just keeping this real. Risk is VERY HIGH right now in the stock market, so any aggressive trades carry even more risk. Be sure you're ok with that. Obviously, the potential for high returns is excellent too. I have no way of knowing the actual news that'll be released tomorrow or Wednesday. Buckle up!
XLY:XLP
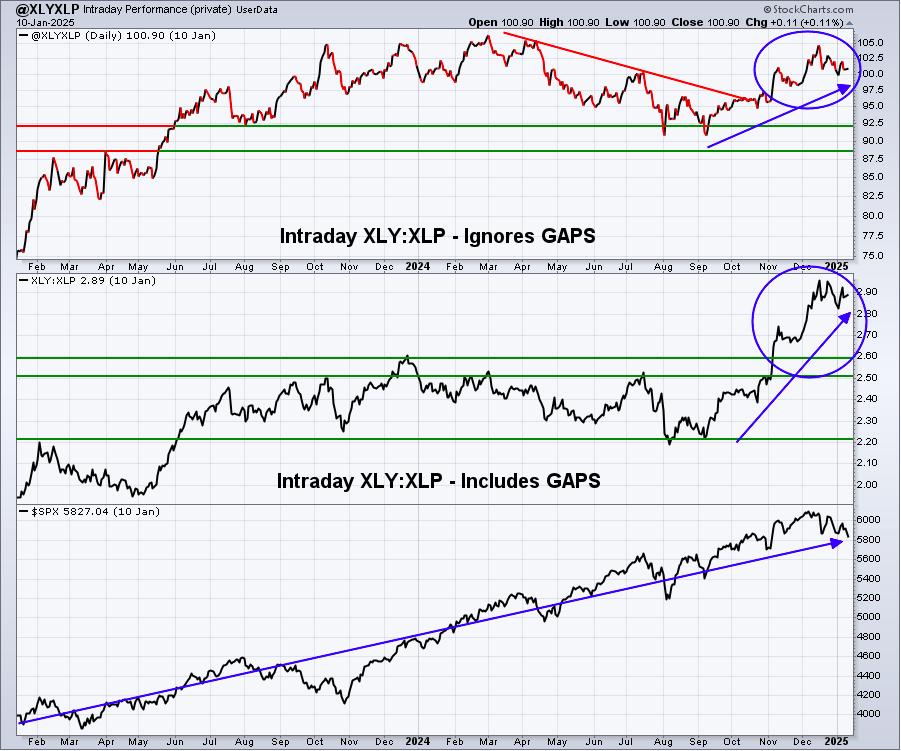
This is my favorite intermarket relationship and what I'd consider to be one of most important secondary indicators. This is a "beneath the surface" indicator that is screaming to be long the stock market, that this round of selling will be short-term and that long-term investors should stay the course.
Sentiment
5-day SMA ($CPCE)
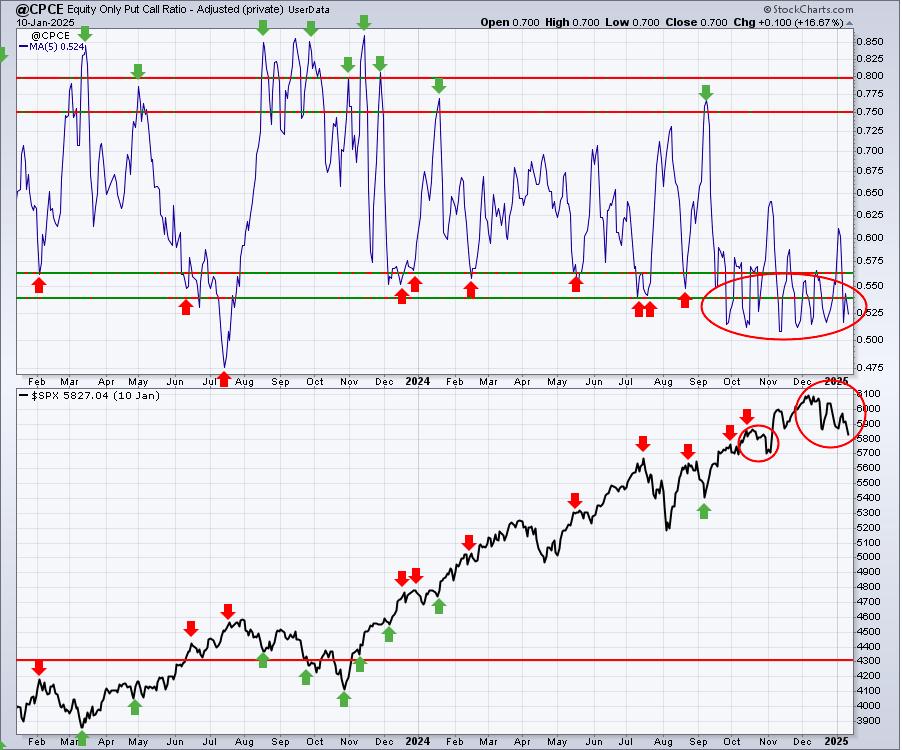
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Readings on the 5-day SMA of the CPCE below .56 or so tell us that options traders are growing quite positive and complacent and these are marked with red arrows in the top panel. Red arrows in the bottom panel tell us where the S&P 500 was at the time of such complacency. While we don't look at this short-term sentiment indicator and expect it to mark major long-term market tops, you can see many short-term tops do coincide with these bullish readings. We have another short-term topping signal right now, but remember, we've already topped and seen some selling. While more is certainly possible, I always watch key price support levels as the combination of price/volume is my primary indicator.
253-day SMA ($CPCE)
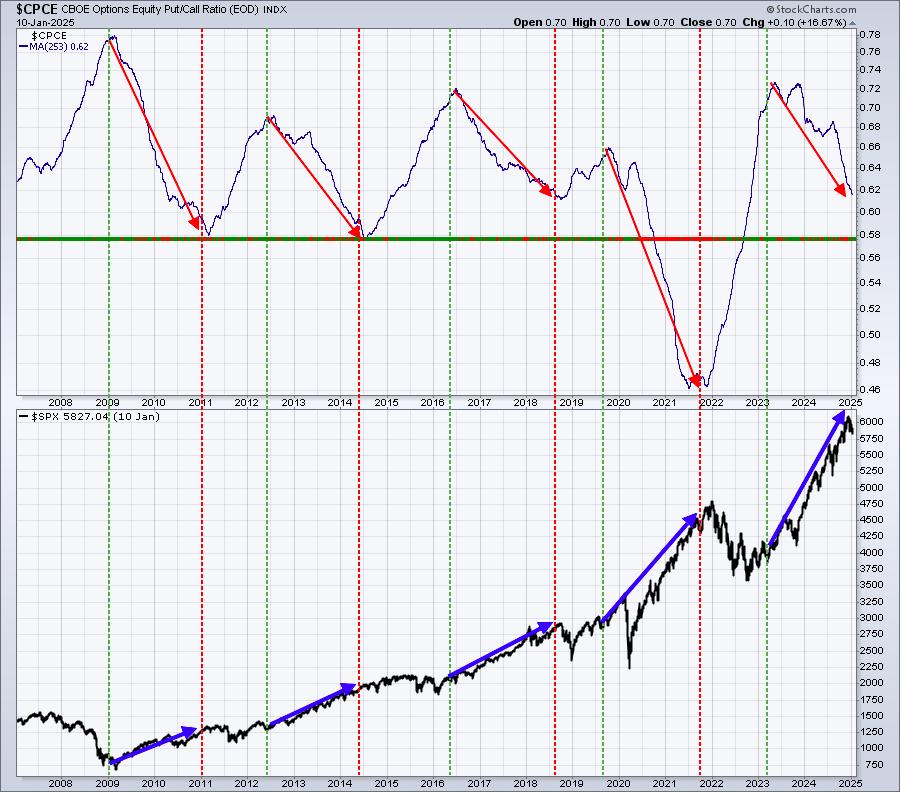
This is the long-term sentiment signal from the CPCE. It's telling me that the current free fall in bearish sentiment is pointing to higher U.S. equity prices, just as it's done in prior years.
Growth vs. Value
Let's just take a quick glance at the benchmark S&P 500 and several key growth vs. value ratios that are useful to follow, keeping in mind that money will rotate from growth to value, sometimes violently, just before and during market selloffs:
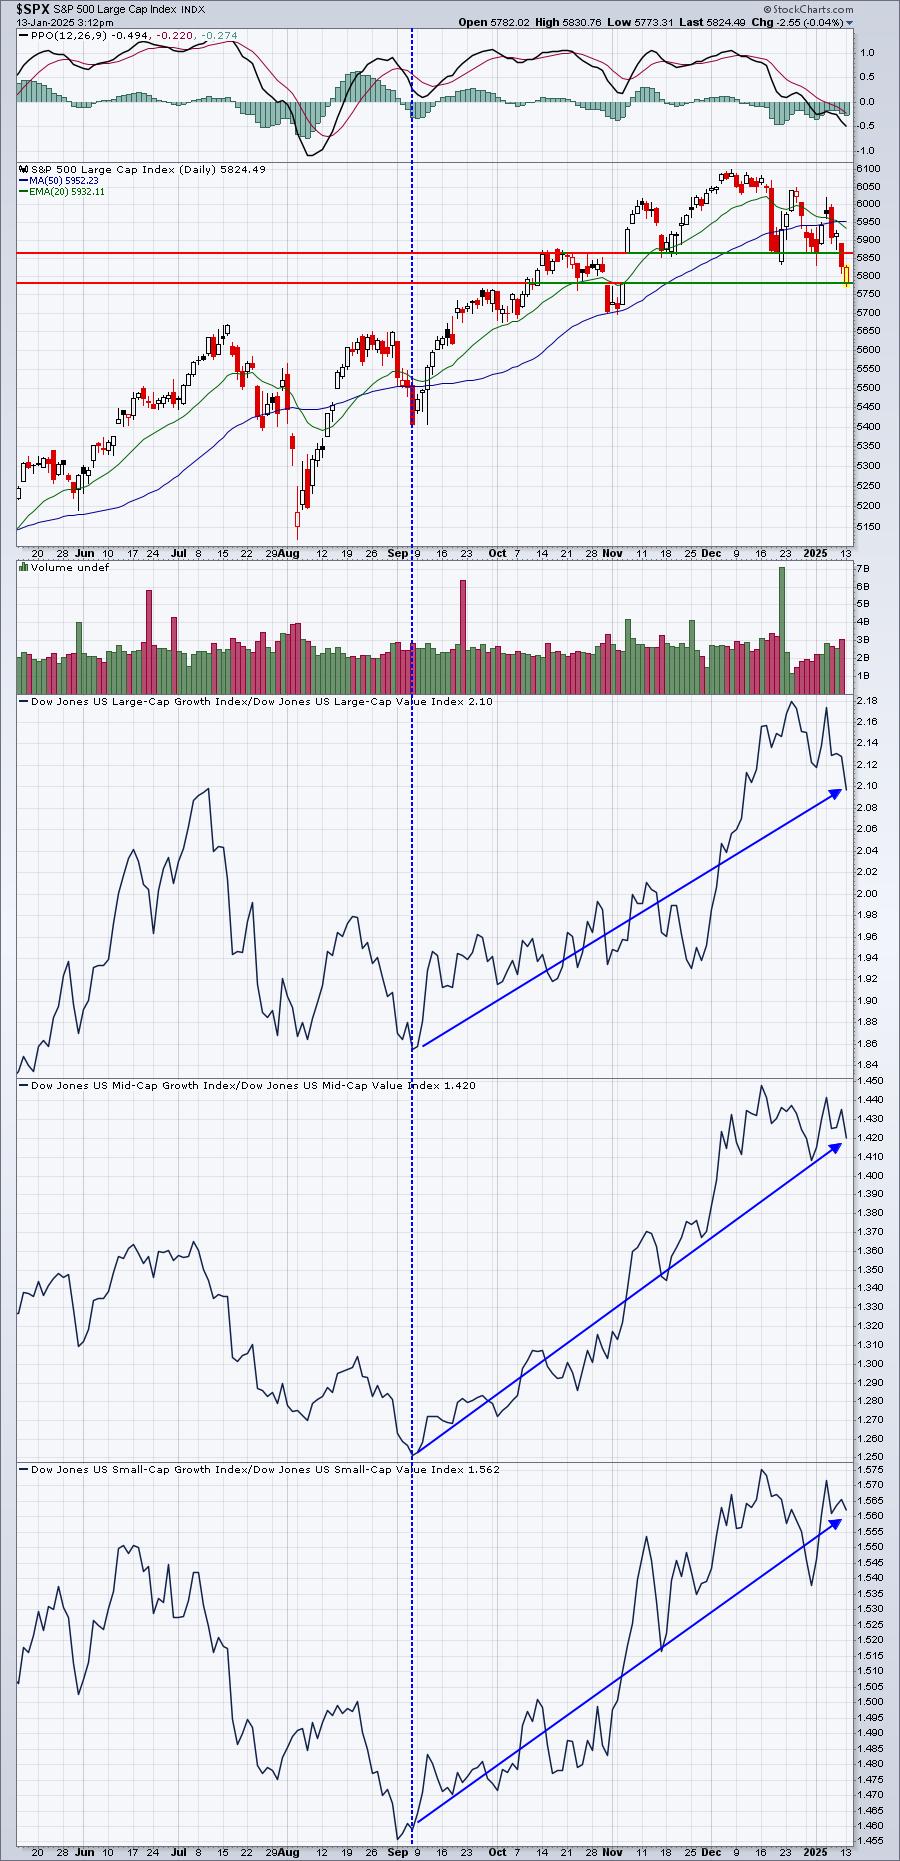
This ratio has turned lower in 2025, but the 4-month uptrend seems quite intact to me. Given all the talk about inflation and higher interest rates, you'd think these ratios would be tumbling. It's one reason why I just don't see the near-term weakness morphing into a correction or cyclical bear market.....and definitely not a secular bear market.
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records and many pay nice dividends that mostly grow every year. Only in very specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. Below is a quick recap of how I viewed their long-term technical conditions last week:
- JPM - trending higher
- BA - recently tested 50-week SMA from underneath, now needs to clear 183
- FFIV - remains in strong rally since June 2024
- MA - approaching 20-week EMA test within solid uptrend
- GS - trending above rising 20-week EMA
- FDX - consolidating; needs a break above 310
- AAPL - as solid as ever; 235-238 should be excellent support
- CHRW - currently testing rising 20-week EMA
- JBHT - remains in lengthy consolidation period
- STX - drop below 50-week SMA on heavier volume a concern, next key support level is 80
- HSY - downtrend in play, but monthly RSI of 37 suggests great entry price for long-term
- DIS - pulling back recently, but clear overhead resistance is at 122-123
- MSCI - just above strong support at rising 20-week EMA
- SBUX - nice recent reversal off 50-week SMA
- KRE - tested 20-week EMA during December, poised for current advance
- ED - rough Q4 leading it back to 80-85 price support range
- AJG - weekly negative divergence, loss of 20-week EMA likely to send down to test rising 50-week SMA
- NSC - railroads and transports weak, December low of 230 is current support
- RHI - has pulled back to test both 20-week EMA and 50-week SMA
- ADM - has fallen back to test key price support at 50; monthly RSI at 34 - patience will be key here
- BG - also testing key price support in the 75-80 range
- CVS - huge December drop has stock at a critical 44-45 support level
- IPG - 3-year consolidation has stock in middle of its 15-month 26-32 price range
- HRL - still living beneath its falling 20-week EMA, need to change this trend; monthly RSI at 41
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to provide an explanation of what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long-term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. The stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
Q4 earnings will kick off with the large banks this Wednesday, January 15th. The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: None
- Tuesday: None
- Wednesday: JPM ($684 billion), WFC ($238 billion), BLK ($153 billion), C ($139 billion)
- Thursday: UNH ($483 billion), BAC ($354 billion), MS ($206 billion), PNC ($77 billion)
- Friday: TFC ($58 billion), SLB ($55 billion), FAST ($42 billion)
Key Economic Reports
- Monday: None
- Tuesday: December PPI
- Wednesday: December CPI, January empire state manufacturing index, beige book
- Thursday: Initial jobless claims, December retail sales, January Philadelphia Fed manufacturing index, November business inventories, January housing market index
- Friday: December housing starts & building permits, December industrial production & capacity utilization
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the 3 key indices that I follow most closely:
S&P 500 (since 1950)
- Jan 13: -21.57%
- Jan 14: +60.98%
- Jan 15: +25.13%
- Jan 16: +24.33%
- Jan 17: +15.48%
- Jan 18: +10.39%
- Jan 19: -7.22%
- Jan 20: -67.02%
- Jan 21: -0.70%
- Jan 22: -10.42%
- Jan 23: +38.65%
- Jan 24: -14.31%
- Jan 25: +10.34%
- Jan 26: +29.56%
NASDAQ (since 1971)
- Jan 13: +3.40%
- Jan 14: +88.77%
- Jan 15: +17.69%
- Jan 16: +69.24%
- Jan 17: +43.48%
- Jan 18: +35.23%
- Jan 19: +46.70%
- Jan 20: -69.20%
- Jan 21: -21.36%
- Jan 22: -38.15%
- Jan 23: +94.39%
- Jan 24: -22.10%
- Jan 25: -5.40%
- Jan 26: +45.80%
Russell 2000 (since 1987)
- Jan 13: +18.56%
- Jan 14: +60.16%
- Jan 15: -30.84%
- Jan 16: +70.35%
- Jan 17: +12.29%
- Jan 18: -14.79%
- Jan 19: +10.17%
- Jan 20: -103.10%
- Jan 21: -39.60%
- Jan 22: +6.13%
- Jan 23: +101.18%
- Jan 24: -1.41%
- Jan 25: +4.75%
- Jan 26: +74.67%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Clearly, the higher interest rate and higher inflation theme is playing out in the stock market short-term. The latest piece of evidence to support this was the Friday jobs report, which came in hotter than expected. We've seen treasury yields moving up and U.S. equities moving down as a result. So what should we look for this week?
- Inflation Data. The December Core PPI will be released Tuesday morning and the December Core CPI will be released Wednesday morning. Higher-than-expected monthly numbers would likely continue the spike in the TNX and overall stock market decline. The opposite, however, could change the narrative completely, with a very strong rebound. This is the key story this week, even above Q4 earnings season kicking in.
- Earnings. Earnings always have the tendency to come in above expectations and I fully believe that'll be the earnings story over the next 3-4 weeks as well. But forward guidance could derail the stock market, especially if companies chatter more about inflation and higher interest rates. The banks will be an interesting group to watch with regard to these two areas.
- Volatility ($VIX). The VIX soared above 22 earlier today, but has quieted back down to 19.42 with 30 minutes left in today's trading session. A couple benign inflation reports the next two days could see the VIX either explode back to the upside, perhaps to 25 or higher, while good news could see the VIX plummet back beneath a key level around 16-17.
- Gaps. Over the past few days, we've seen gap downs, but in many cases, we've also seen intraday strength off of these gap downs, with today being another example. That normally precedes better stock market action, but time will tell here.
Feedback
If you'd like to share your thoughts on our Weekly Market Report, positive or negative, you can reach us at "[email protected]".
Happy trading!
Tom