
EB Weekly Market Report - Monday, June 2, 2025
ChartLists/Spreadsheets Updated
The following ChartLists/Spreadsheets were updated over the weekend:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)**
- Bullish Trifecta (BTCL)
- Short Squeeze (SSCL)
- Leading Stocks (LSCL) - *****NEW*****
- Manipulation Spreadsheet
- Upcoming Earnings & Upcoming Earnings Relative Strength
** I made a recent change on the RGCL. If you look at the list of companies on it, you'll see that stocks like MTZ show an asterisk before and after its ticker symbol. These companies all raised guidance for both revenues and EPS in the upcoming quarter, as well as raised guidance for both revenues and EPS in the coming year. Many companies are included on the RGCL for simply raising revenue guidance or EPS in an upcoming quarter OR year. To raise guidance for both revenues and EPS in both the upcoming quarter and upcoming year shows more confidence in their business strategy, in my opinion. I'm not endorsing these stocks as "better" or anything like that. I just feel it's important to begin differentiating those companies that significantly raise guidance like that.
The ChartLists should be available to download into your StockCharts Extra or Pro account, if you have a StockCharts membership. Otherwise, we can send you an Excel file with the stocks included in these ChartLists in order to download them into other platforms.
The Manipulation Spreadsheet has been updated for our 3 primary index ETFs - SPY, QQQ, and IWM and our 12 individual stocks - AAPL, MSFT, NVDA, META, GOOGL, AMZN, TSLA, NFLX, AMD, JPM, PLTR, and CLS. I review this Excel file weekly. It is not meant to be updated and studied daily.
If you have any questions, please reach out to us at "[email protected]".
Weekly Market Recap
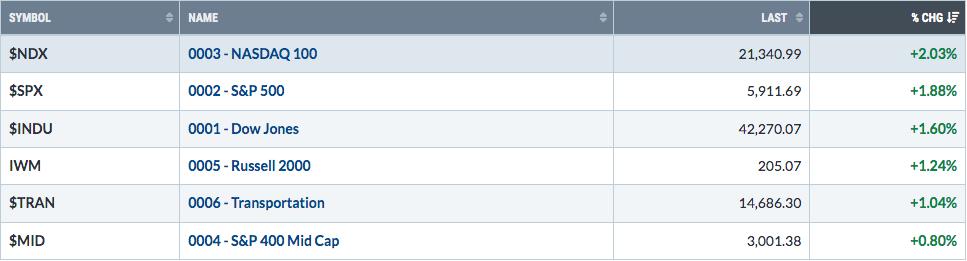
Major Indices
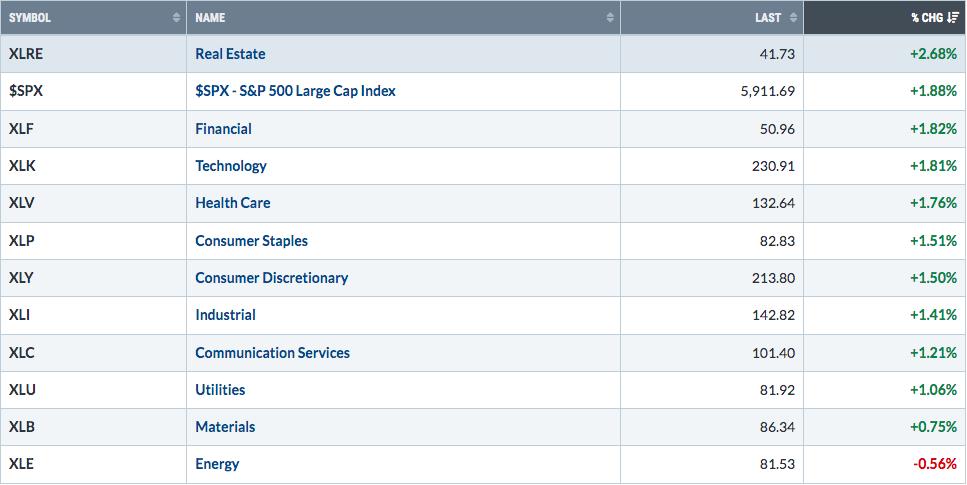
Sectors
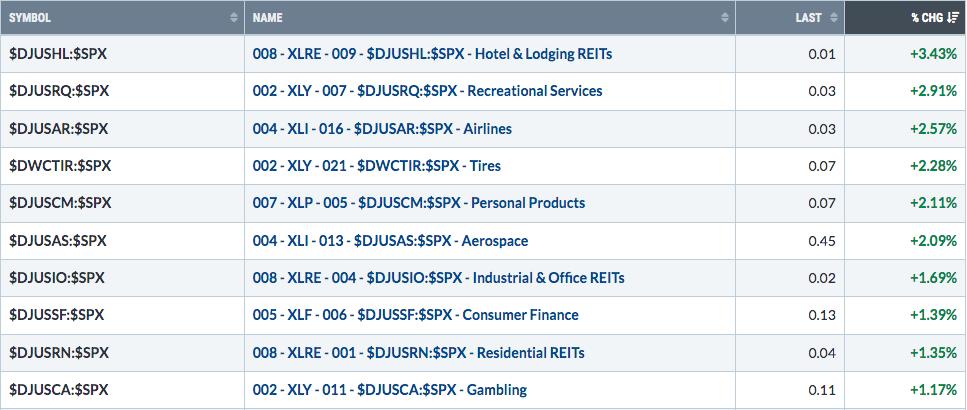
Top 10 Industries Last Week
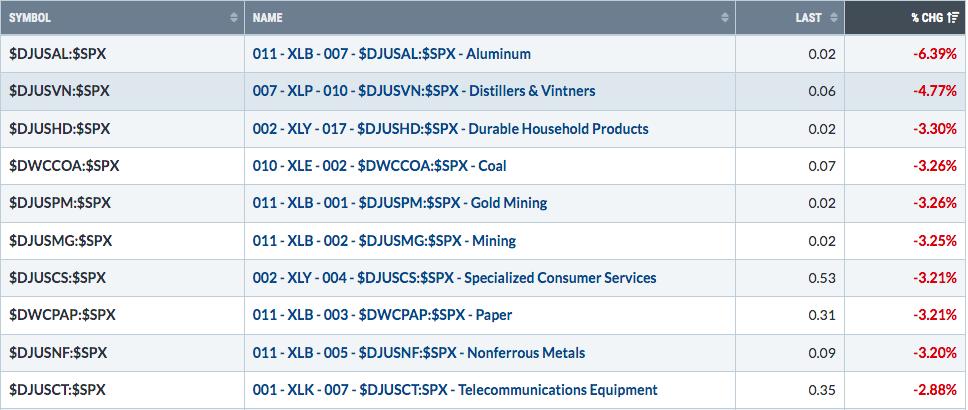
Bottom 10 Industries Last Week
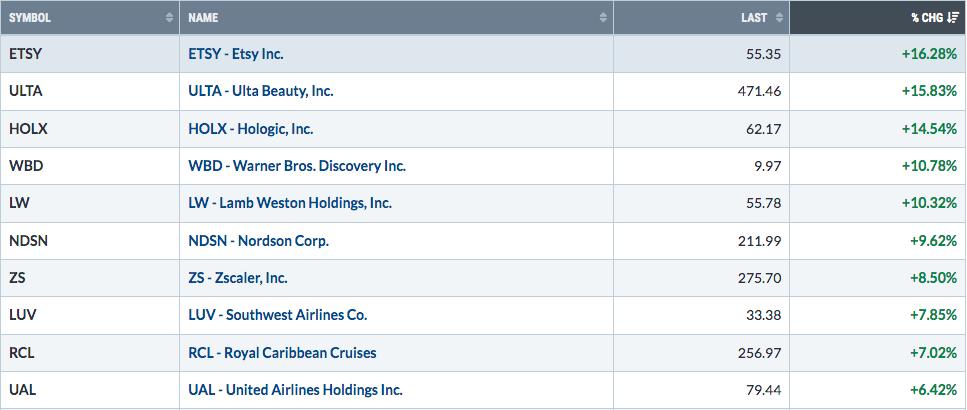
Top 10 Stocks - S&P 500/NASDAQ 100
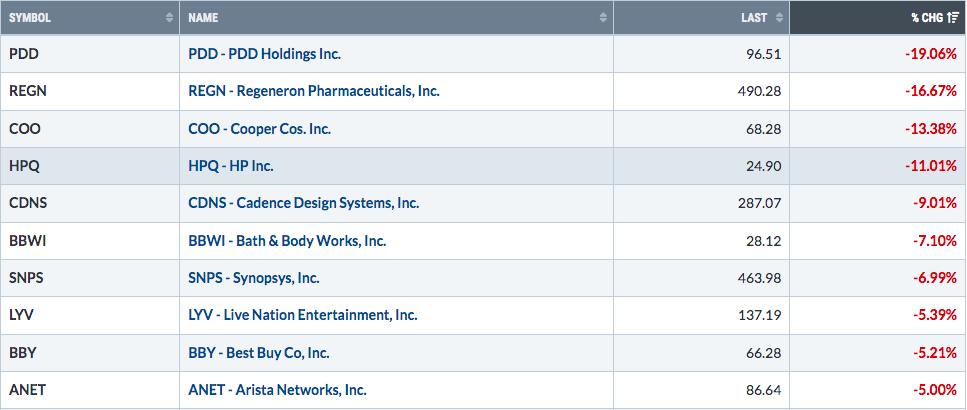
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
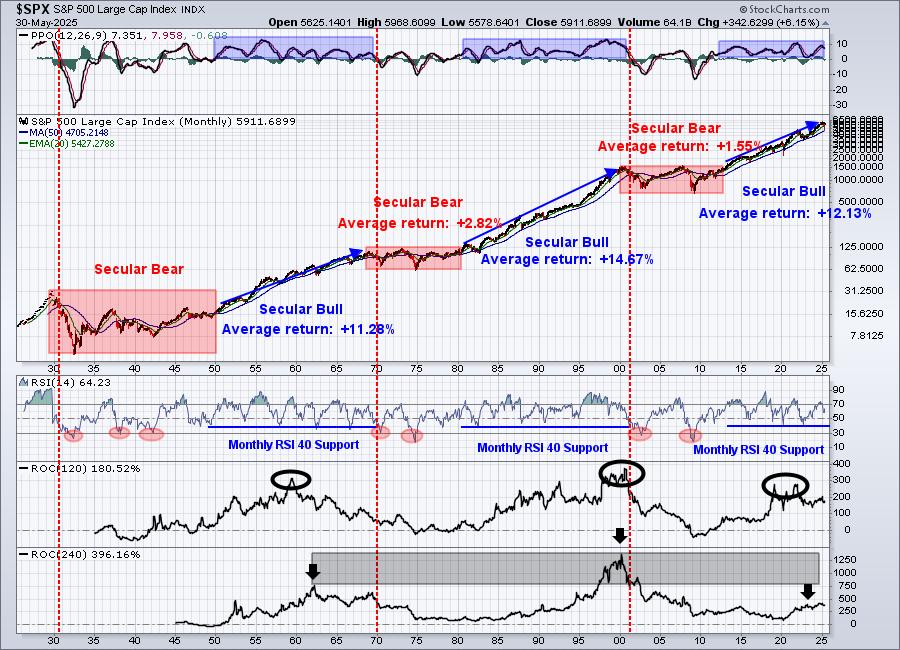
Ignore the news. The long-term secular bull market remains perfectly intact and most of my signals point to further strength ahead. In other words, the rally off the April 7th low appears to be fully supported by my sustainability ratios and other longer-term signals.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
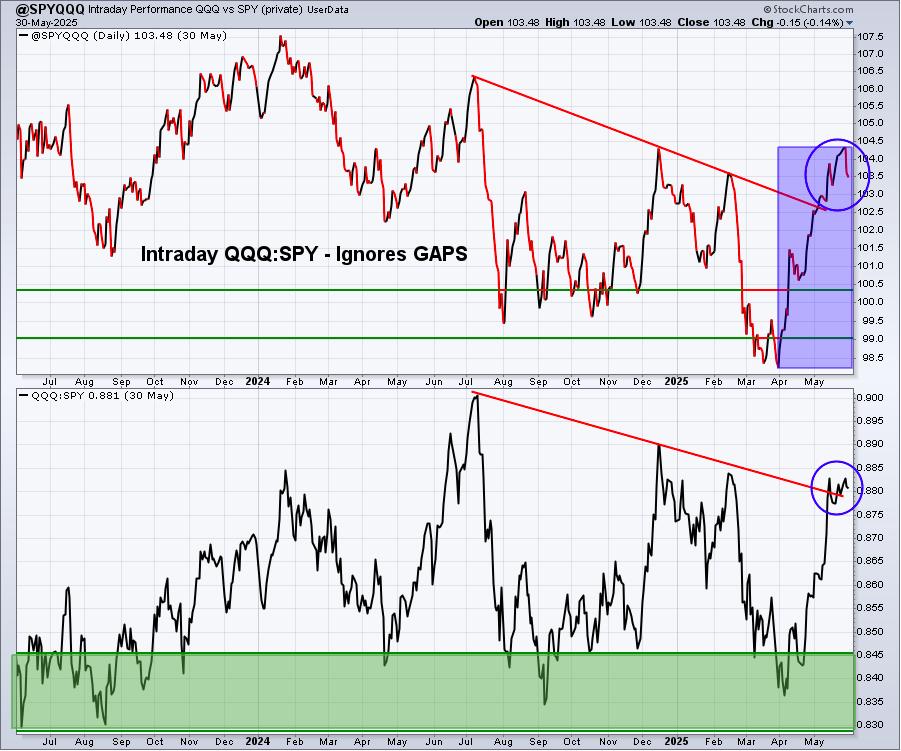
Like the intraday XLY:XLP ratio below, this intraday ratio suggests that money is rotating back a bit towards the more value-oriented S&P 500. I don't know if this is anything substantive at this point, but I'm definitely not ignoring it.
IWM:QQQ
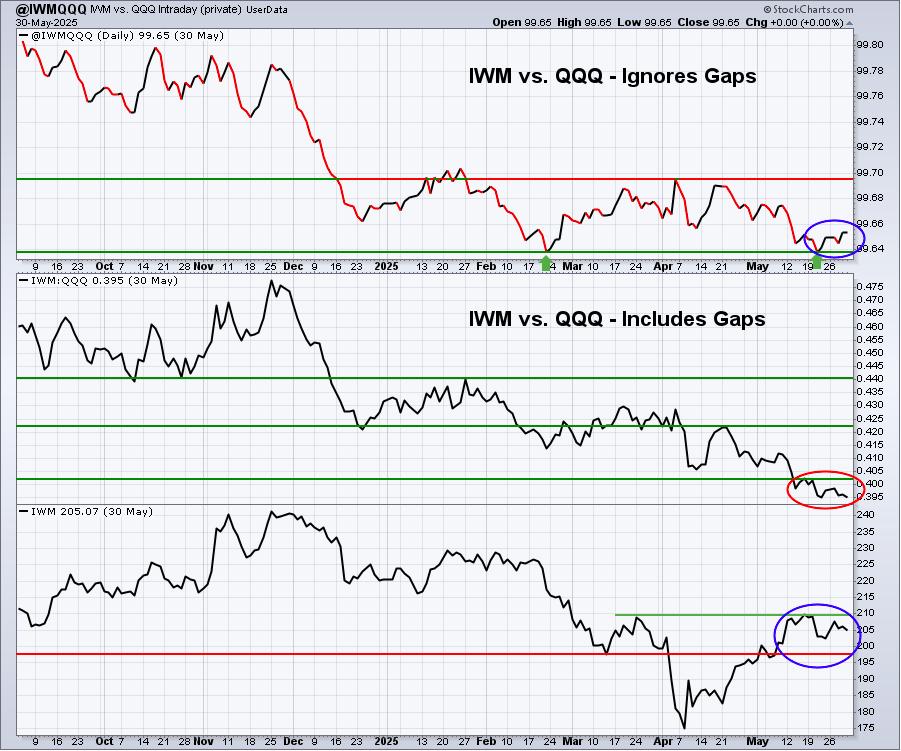
There's still the potential head & shoulders bottom on the IWM that's worth keeping an eye on, but the top two panels are not really flashing any "GET IN SMALL CAPS NOW" signal. I do love the AD line soaring on the IWM daily chart, but I think before we see a period of significant outperformance by small caps, we should see the top panel, especially, surging higher.
XLY:XLP
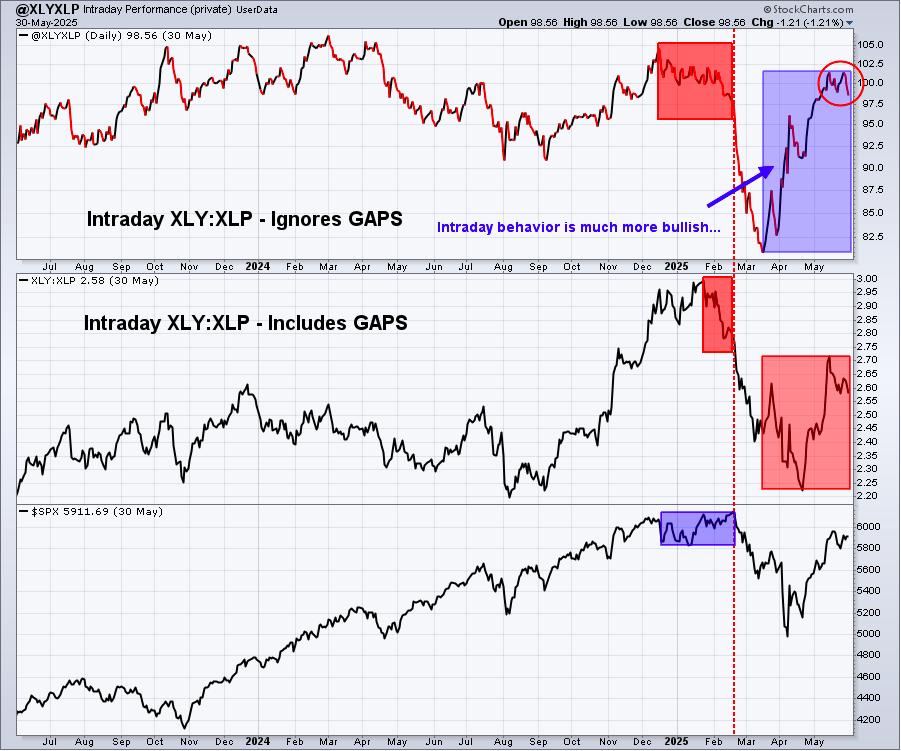
This signal has been incredibly bullish, calling for a market reversal as a positive divergence began to emerge in March. The intraday XLY:XLP ratio started to move higher 3 weeks or so BEFORE the S&P 500 bottomed. It was a signal that Wall Street was rotating to more aggressive areas in March, ahead of an April reversal. The red circle is showing at least a period of profit taking in the more aggressive consumer discretionary sector. I wouldn't sell the stock market farm, because of this development, but it's at least worth noting. If other short-term signals begin to align with this one, a more significant intermediate-term top could be in play. It's a little early to make that call.
Sentiment
5-day SMA ($CPCE)
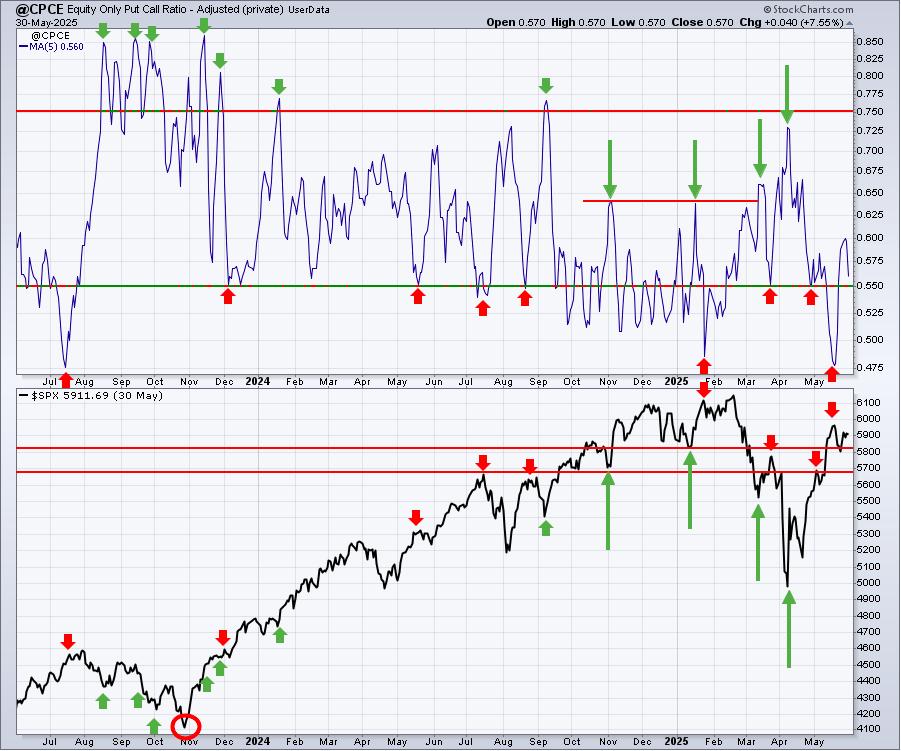
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
When this 5-day CPCE reading hit 0.48, it suggested the increasing likelihood of at least a short-term market top. That's what we saw. The top from mid May still hasn't been cleared.
253-day SMA ($CPCE)
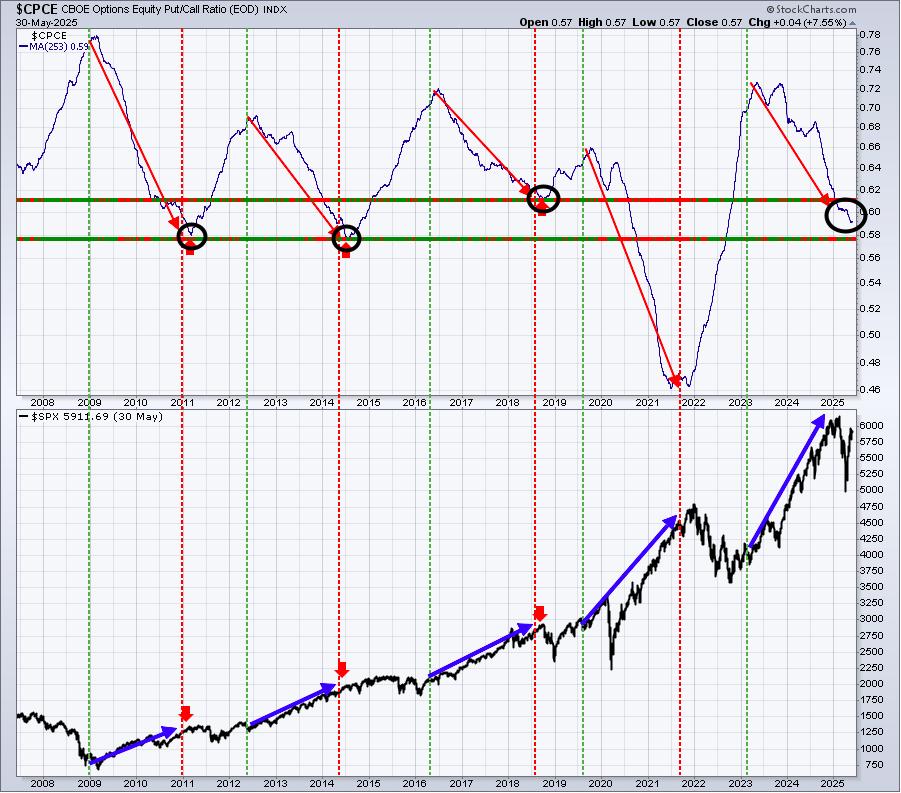
H
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. Below is a quick recap of how these stocks look now:
- JPM - working its way back to all-time high
- BA - there's a decent chance BA has bottomed long-term; AD line is moving up with price now
- FFIV - very bullish action above its 20-month SMA
- MA - very steady and bullish long-term performer
- GS - trending higher above 20-month EMA
- FDX - double top established near 300-310, key uptrend line support approaching near 180
- AAPL - monthly RSI at 50, which has been an excellent time to buy AAPL over the past two decades
- CHRW - remains in multi-decade uptrend
- JBHT - 110-120 area was excellent support/resistance range in 2018-2020; we recently approached it again
- STX - broke out of A-B-C-D-E ascending triangle, with long-term measurement to roughly 175-180
- HSY - still trending down with excellent price support near 140
- DIS - held 80 support once again in April, now looking for key breakout above 125
- MSCI - long-term consolidation since 2021 high is bullish, but need breakout above 650 level
- SBUX - in lower end of 4-5 year trading range, excellent entry here from a long-term perspective
- KRE - has bounced nicely from April washout low
- ED - has been a solid income-producer and investment since the financial crisis low in 2009
- AJG - few stocks have been steadier to the upside over the past decade
- NSC - long-term cup with handle pattern? Breakout above 280 would confirm and measure to 380
- RHI - rough trading in 2025, massive support at 30, should it get that far
- ADM - continues to trade above long-term price support in low 40s
- BG - multiple price support tests near 70 in 2025
- CVS - excellent support at 45 or just below, just failed on bounce at 50-month SMA at 72
- IPG - monthly RSI now at 37 and also testing 4-year price support near 22.50
- HRL - long-term price support at 25 and stock now showing positive divergence on monthly chart - bullish
- DE - one of the better 2025 momentum stocks on this list
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
Very few companies will report quarterly results until mid-April. The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: None
- Tuesday: CRWD ($114 billion)
- Wednesday: None
- Thursday: AVGO ($1.14 trillion), LULU ($38 billion), DOCU ($17 billion
- Friday: None
Key Economic Reports
- Monday: May PMI manufacturing, May ISM manufacturing, April construction spending
- Tuesday: April factory orders, April JOLTS
- Wednesday: May ADP employment report, May PMI composite, May ISM services, Beige book
- Thursday: Initial jobless claims, Q1 productivity & costs
- Friday: May nonfarm payrolls, unemployment rate, & average hourly earnings
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely:
S&P 500 (since 1950)
- Jun 2: +36.90%
- Jun 3: +4.15%
- Jun 4: -1.04%
- Jun 5: +47.89%
- Jun 6: +55.43%
- Jun 7: +3.37%
- Jun 8: -18.56%
- Jun 9: -63.85%
- Jun 10: +10.30%
- Jun 11: -16.37%
- Jun 12: +10.42%
- Jun 13: +11.80%
- Jun 14: -12.52%
- Jun 15: +18.27%
NASDAQ (since 1971)
- Jun 2: +131.50%
- Jun 3: -66.10%
- Jun 4: +80.54%
- Jun 5: +107.72%
- Jun 6: -13.07%
- Jun 7: +17.61%
- Jun 8: -18.14%
- Jun 9: -49.37%
- Jun 10: -4.79%
- Jun 11: -65.22%
- Jun 12: +6.56%
- Jun 13: +0.38%
- Jun 14: -22.67%
- Jun 15: +45.66%
Russell 2000 (since 1987)
- Jun 2: +179.79%
- Jun 3: -46.59%
- Jun 4: +39.89%
- Jun 5: +88.81%
- Jun 6: -4.47%
- Jun 7: +32.75%
- Jun 8: +1.50%
- Jun 9: -63.05%
- Jun 10: -52.33%
- Jun 11: -160.32%
- Jun 12: -18.32%
- Jun 13: -29.90%
- Jun 14: -40.88%
- Jun 15: +84.42%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
We finished May with huge gains as U.S. stocks continued to rebound from the February-April cyclical bear market. Uncertainties remain as we move into June, which could lead to more volatility. Keep in mind that Q2 performs much better from April 1 to May 15, as opposed to the second half of the quarter from May 16 to June 30. Once the current bullish historical period ends on June 6th (Friday), the majority of June can be quite challenging. I'll first watch technical action, but I'm always aware of historical tendencies, especially if technical conditions begin to change.
Here are a few things I'm watching this week:
- 20-Day EMAs. An uptrend remains an uptrend until it isn't. In order for ANY significant weakness to take place in the stock market, price action on our major indices needs to violate rising 20-day EMA support. We have yet to see that.
- History. The May 26th-June 6th period has been one of the most bullish periods of the year - dating back to 1950. The annualized return on the S&P 500 has been +34.37% during this 11-day period since 1950. This doesn't guarantee higher prices ahead, but it does provide historical tailwinds. We have gained ground in this period so far in 2025, but does it continue throughout this week?
- Leadership. As I look at industry group leadership, nearly every group outperforming the S&P 500 since the April 7th bottom has been in one of our five aggressive sectors - XLK, XLY, XLC, XLI, and XLF. So long as this continues, our major indices are quite likely to trend higher. Trading leading stocks in leading industry groups is the key to performing well, in my opinion.
- Inflation. Last week, we had Q1 GDP show a steady annual rate of PCE. In the personal spending and personal income report last week, the April PCE showed a year-over-year price index change of 2.1%, which continues a steady decline in that index. The year-over-year price index change in prior months was 2.3% (March), 2.6% (February), and 2.5% (January). Both Core CPI and Core PPI for April came in below expectations. It sure seems to me that inflation is trending lower. But, if the Fed continues to remain neutral on rates, it provides an opportunity for economic weakness to accelerate. That's the risk to the current Fed policy and to stock market participants.
- Jobs. The May nonfarm payrolls report will be released on Friday, two days after we'll get a glimpse of the ADP employment report, due out on Wednesday morning. Both of these reports can be of the market-moving variety as Wall Street and the Fed determine the likelihood of further recessionary vs. inflationary pressures caused by the labor market. Given all the uncertainty currently in both areas, this week's jobs reports could be more significant, leading to higher volatility.
Happy trading!
Tom