
EB Weekly Market Report - Monday, July 18, 2025
ChartLists/Spreadsheets Updated
The following ChartLists/Spreadsheets were updated over the weekend:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Short Squeeze (SSCL)
- Leading Stocks (LSCL)
- Upcoming Earnings and Upcoming Earnings Relative Strength
- Manipulation Spreadsheet
Weekly Market Recap
Major Indices
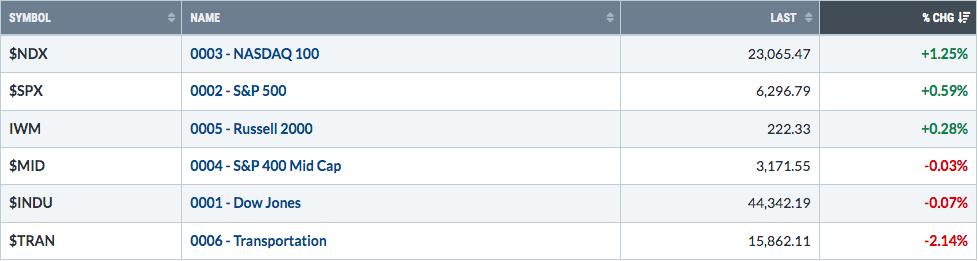
Sectors
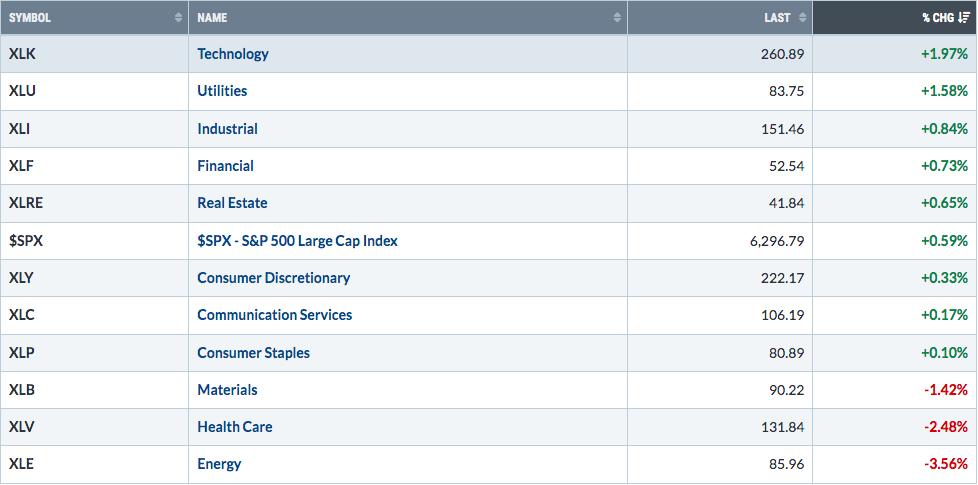
Top 10 Industries Last Week
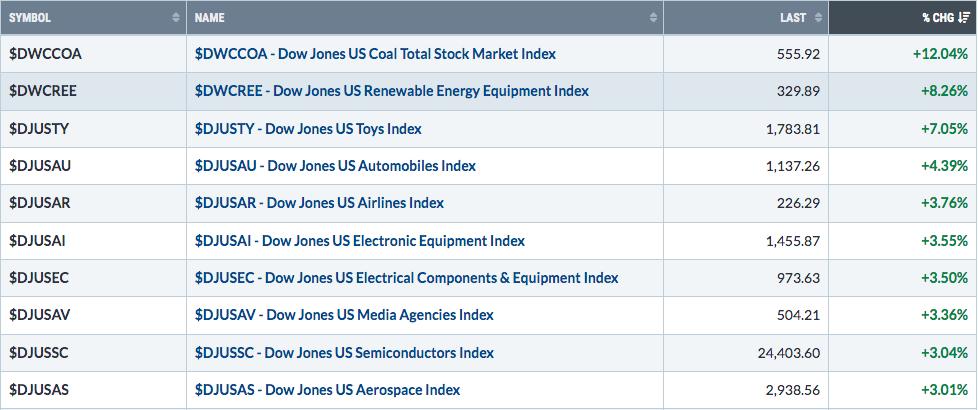
Bottom 10 Industries Last Week
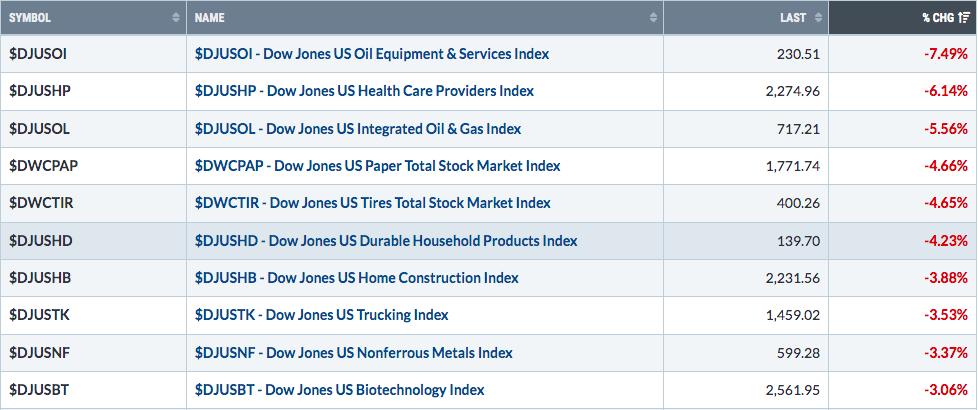
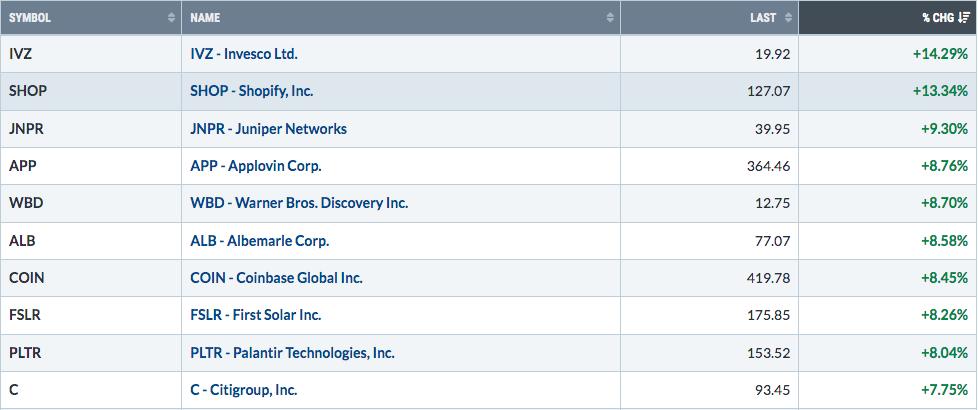
Top 10 Stocks - S&P 500/NASDAQ 100
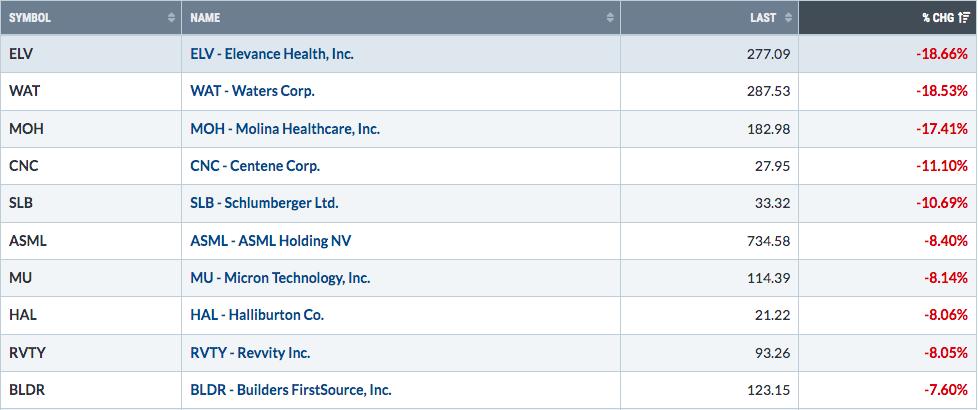
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
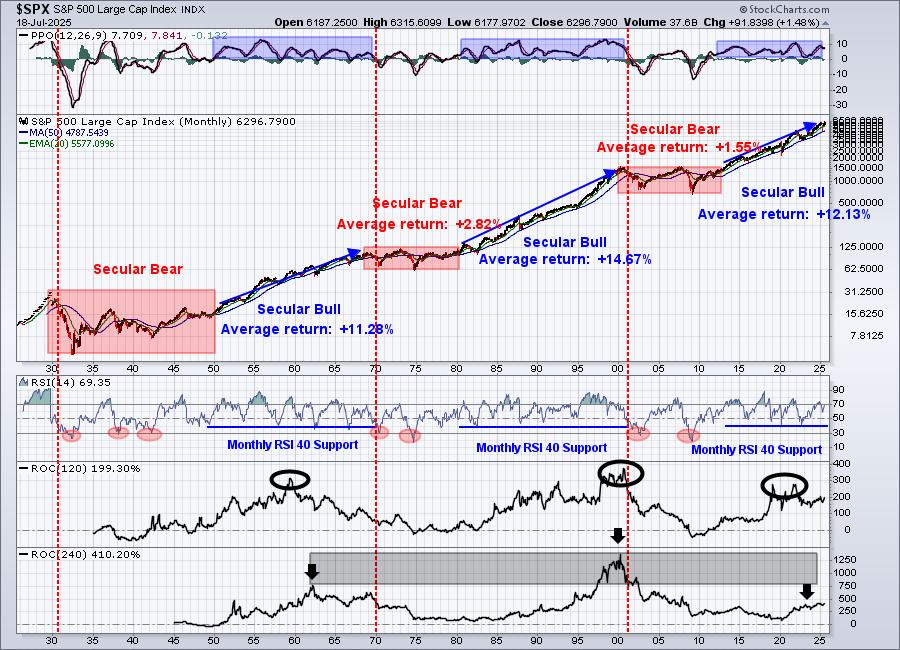
The biggest challenge of 2025 is behind us, in my opinion. Navigating the 2025 cyclical bear market was the hard part, which we did very well. My only question as we move through this quarter's earnings reports and the summer season is whether we get a period of selling/consolidation after earnings season. Keep in mind that the 2nd half of Q3 (August 15th through September 30th) is historically the weakest half quarter. Outside of Q4, we should ALWAYS lower our expectation bar during the 2nd half of calendar quarters. Currently, we're in the first half of Q3 and that typically means to let your profits run.
Sustainability Ratios
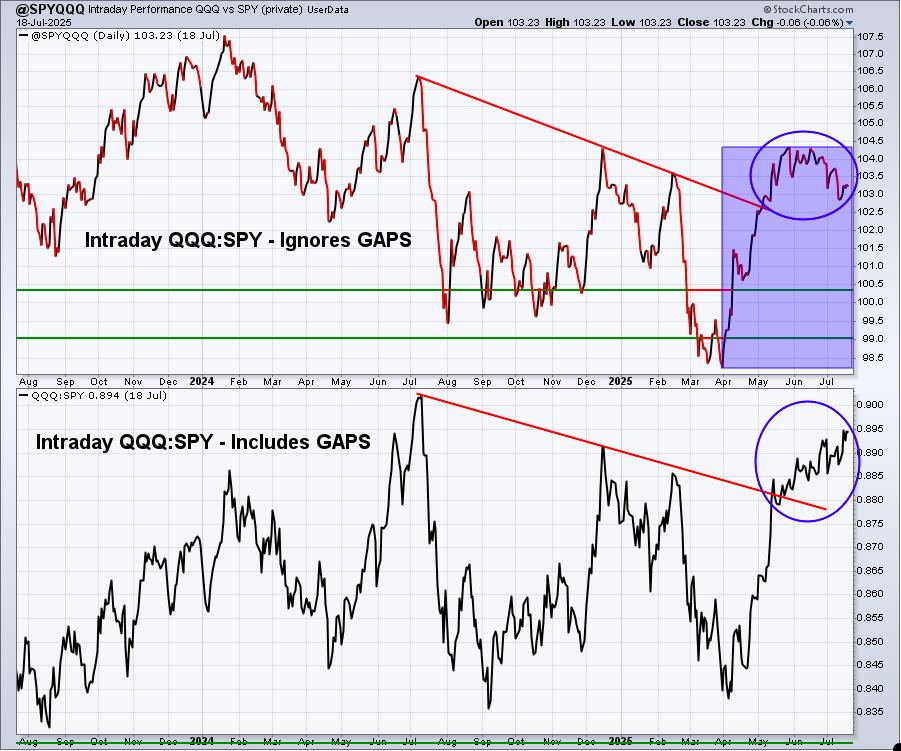
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
I said the following last week and nothing has really changed in my mind:
"The upper panel that shows recent intraday deterioration in the QQQ:SPY ratio is a small red flag, but a red flag nonetheless. I'm generally not going to grow too bearish as long as the S&P 500 remains in a solid uptrend AND the XLY:XLP ratio (below) is trending higher and supporting the S&P 500 advance. It's ok to see a bit of rotation from the riskier NASDAQ 100 to the less risky S&P 500, so long as we're not seeing a lot of other warning signs simultaneously. I think we're perfectly fine for now."
IWM:QQQ
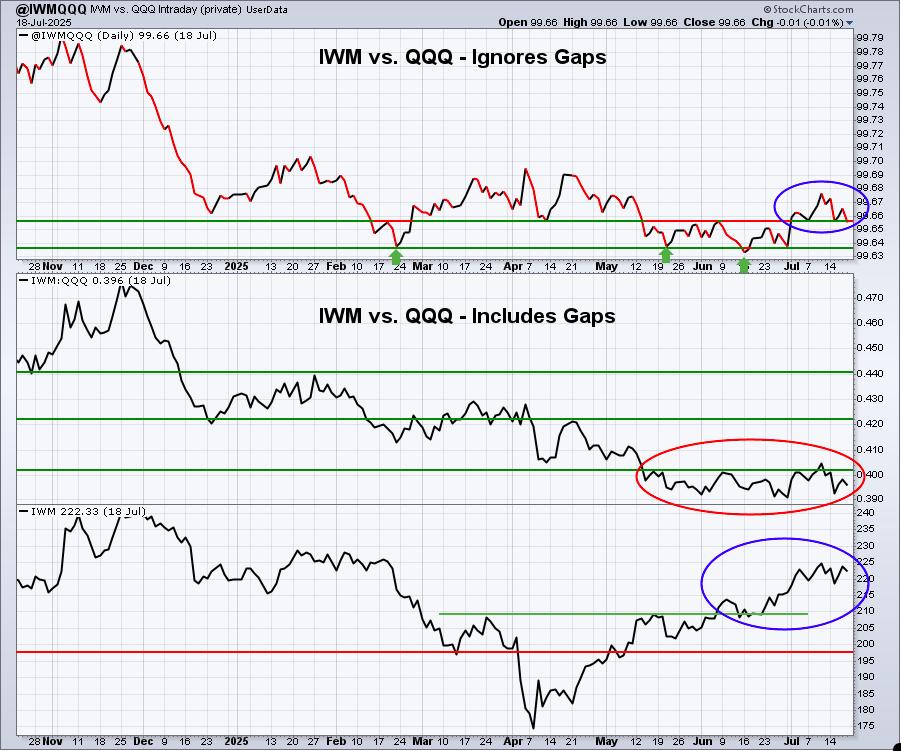
Some have looked at last week's inflation data and grown more adamant that inflation is back on the rise. I look at the data and simply don't see it. I also watch growth stocks completely outperform value stocks and I walk away from that feeling that Wall Street doesn't see an inflation problem either. Despite my feeling that inflation isn't a problem and that we'll see rate cuts somewhere down the road, small caps backed off on a relative basis last week and that's a short-term concern. Small caps are one area that should benefit from rate cuts, so if their relative performance continues to disappoint, it's likely because Wall Street is growing increasingly concerned with Fed Chief Powell and his refusal to address the more pressing need - our economy.
XLY:XLP
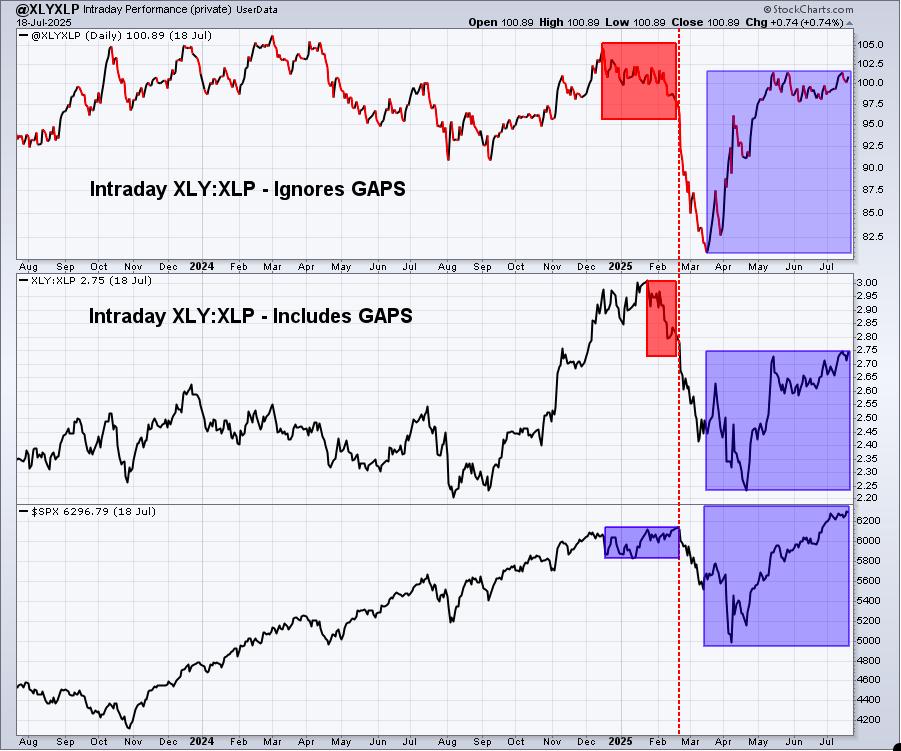
When I see what I'm seeing here, I'm just not going to be bearish PERIOD. I am of the opinion that this chart is one of the most critical in calling the overall market and the continuing advance in both the benchmark S&P 500 and our XLY:XLP ratio is screaming to me that we're going to head higher in the 2nd half of the year.
Sentiment
5-day SMA ($CPCE)
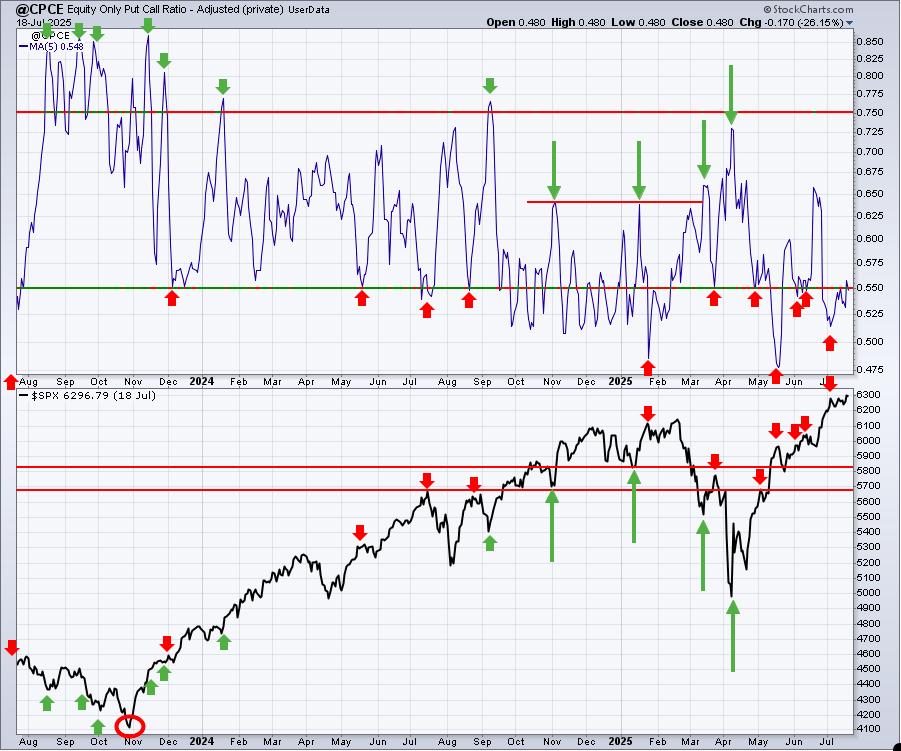
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Keep in mind that the above 5-day SMA reading of the CPCE is our "speed boat" sentiment indicator that changes quite frequently. Like the QQQ:SPY minor red flag above, the current 5-day CPCE reading at .55 remains a slight warning sign, but not a signal that we'll see deep selling. Many times, these overly complacent readings accompany a brief period of consolidation/selling. I would still not be expecting any type of major selloff at this time, based upon this signal and the others above.
253-day SMA ($CPCE)
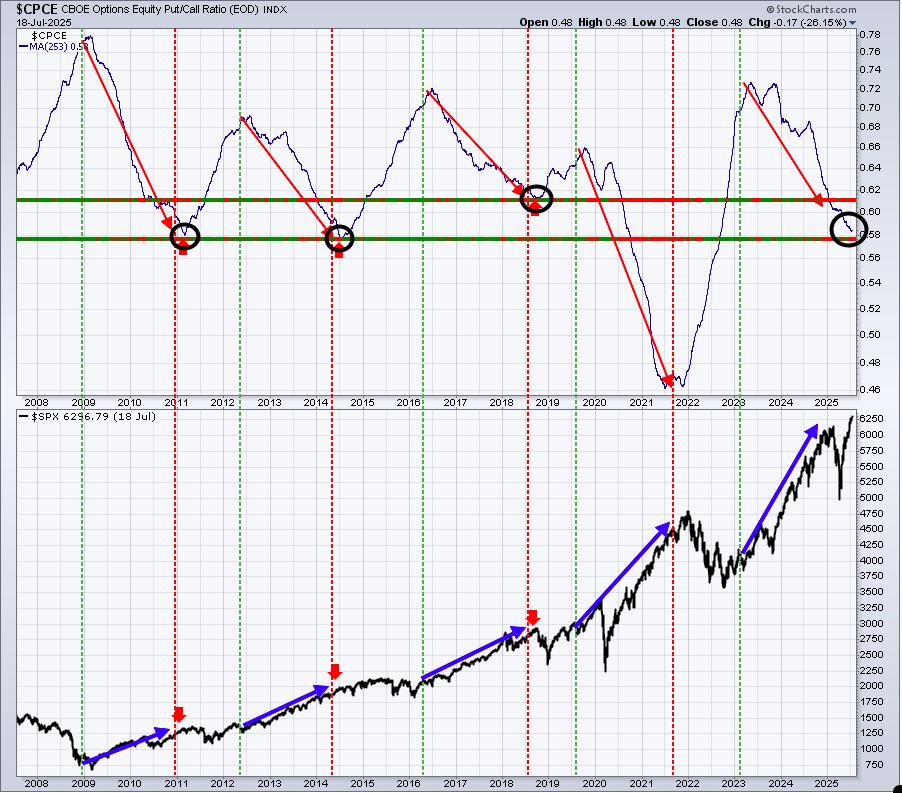
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our speedboat indicator. This one usually provides us a very solid long-term signal as the overall market environment moves from one of pessimism to complacency and vice versa. Look at the above chart. When the 253-day SMA is moving lower like it is now, it accompanies our most bullish S&P 500 moves. When the short-term 5-day SMA signal turns bearish, like it has now, it's a good idea to remind ourselves that the longer-term picture still remains quite bullish based on this longer-term sentiment indicator.
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. Below is a quick recap of how these stocks look as of this past weekend:
- JPM - long-term overbought, but continuing to push higher into all-time high territory
- BA - substantial improvement continues, I could see this rally continue to 265-280 area
- FFIV - again challenging all-time high
- MA - very steady and bullish long-term performer
- GS - June turned out to be a HUGE month as GS broke back out to all-time highs
- FDX - recently failed again beneath falling 20-week EMA
- AAPL - monthly RSI bouncing off 50 as I discussed last time; seems to be back in uptrend mode
- CHRW - 85-90 is solid longer-term support and it's held that level in 2025
- JBHT - would like to see 120-125 support hold and it has, now must negotiate overhead 20-week EMA
- STX - long-term breakout in May has sent stock soaring
- HSY - strength today has it against key resistance from 175-180
- DIS - threatening major multi-year resistance level near 125; a close above would be very bullish
- MSCI - 3 1/2 year consolidation still in play; 654 is the ultimate resistance and breakout level
- SBUX - remains squarely in the middle of a wide consolidation range between roughly 70 and 115
- KRE - looking for a long-term breakout above 70, trending higher for now
- ED - successfully tested its rising 20-month EMA in both June and July
- AJG - approaching a rare 20-month EMA test, which has provided great support since 2010
- NSC - is this the breakout of a multi-year cup with handle pattern? if so, measurement is 360
- RHI - still no sign of bottom, but management recently raised its dividend, showing great confidence
- ADM - nice reversal off 43 price support, but now trying to clear its declining 20-week EMA
- BG - remains in a wide 65-75 support zone, another trying to clear its declining 20-week EMA
- CVS - looks like failed attempt to clear 50-month SMA, rolling over; major support at 43
- IPG - 22.50 support continues to hold - at least for now
- HRL - the last 18 months have been spent in a fairly narrow 27-35 range
- DE - still looks very bullish from a long-term perspective (and short-term for that matter)
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
Very few companies will report quarterly results until mid-April. The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: VZ ($173 billion), NXPI ($57 billion)
- Tuesday: KO ($304 billion), TXN ($197 billion), ISRG ($185 billion), LMT ($110 billion)
- Wednesday: GOOGL ($2.23 trillion), TSLA ($1.03 trillion), IBM ($262 billion), GEV ($156 billion)
- Thursday: HON ($153 billion), BX ($126 billion), INTC ($99 billion)
- Friday: HCA ($87 billion), AON ($77 billion)
Key Economic Reports
- Monday: June leading indicators
- Tuesday: June CPI, July empire state manufacturing index
- Wednesday: June existing home sales
- Thursday: Initial jobless claims, July PMI composite, June new home sales
- Friday: June durable goods
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Jul 21: -29.02% (Ex: cumulative gains = -5.97% over 52 trading days. -5.97% x 253/52 = -29.02%)
- Jul 22: -9.64%
- Jul 23: -29.58%
- Jul 24: -4.68%
- Jul 25: +17.53%
- Jul 26: +30.43%
- Jul 27: +9.03%
- Jul 28: -21.72%
- Jul 29: +37.64%
- Jul 30: +61.29%
- Jul 31: +21.91%
- Aug 1: -17.56%
- Aug 2: +10.21%
- Aug 3: +21.48%
NASDAQ (since 1971)
- Jul 21: -57.94%
- Jul 22: -0.01%
- Jul 23: -92.73%
- Jul 24: -49.85%
- Jul 25: +31.82%
- Jul 26: +18.91%
- Jul 27: -16.15%
- Jul 28: -53.85%
- Jul 29: +20.55%
- Jul 30: +30.14%
- Jul 31: +12.80%
- Aug 1: -52.16%
- Aug 2: -2.93%
- Aug 3: +32.33%
Russell 2000 (since 1987)
- Jul 21: -98.75%
- Jul 22: +43.75%
- Jul 23: -74.02%
- Jul 24: -95.36%
- Jul 25: +48.07%
- Jul 26: +56.13%
- Jul 27: -61.56%
- Jul 28: +10.48%
- Jul 29: +100.52%
- Jul 30: +61.86%
- Jul 31: -24.19%
- Aug 1: -81.03%
- Aug 2: -88.18%
- Aug 3: -31.43%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Risk-on trading strategies remain in play. Growth stocks continue to perform well and the cryptocurrencies have been on fire. Etherium ($ETHUSD) and XRP ($XRPUSD) have absolutely soared over the past couple weeks. The former is approaching its all-time high, while the latter is already there. I always feel bullish U.S. equities when cryptos are performing well. My risk-on intermarket ratios remain very bullish over the longer-term as well. I'd keep looking for higher prices ahead, with, of course, normal pullbacks and consolidation along the way.
Here are a few things I'll be watching this week:
- Earnings. Earnings season will be begin to pick up this week, with notable quarterly results coming from Alphabet (GOOGL) and Tesla (TSLA) after the bell on Wednesday. These two will be interesting, because both have started to show a bit of absolute and relative strength in July. However, prior to July, neither was performing well. So will it be the "calm before the storm" type of reports with disappointment ahead? Stay tuned.
- The Fed. Fed Chief Powell will speak on Tuesday at 8:30am ET. I don't normally follow the Fed's appearances throughout the week, but Wall Street is very focused on the timing of potential rate cuts. Therefore, anything Powell says could be market-moving material.
- 10-Year Treasury Yield ($TNX). There was much talk last week about how inflation was picking back up after the June CPI and PPI reports were released. However, "the money" has been speaking since then and the TNX has dropped from its 4.49% peak to 4.35% today. Investors are buying bonds and sending yields lower since those inflation reports. Does this reverse after Powell's comments on Tuesday?
- Seasonality. We're in the midst of the 3rd worst week of the calendar year historically (July 17th close through July 23rd close). Thus far, we've seen little selling. In fact, the S&P 500 is attempting to close above 6300 for the first time in its history today. Historical patterns provide us tendencies, not guarantees.
Happy trading!
Tom