
EB Weekly Market Report - Monday, July 28, 2025
ChartLists/Spreadsheets Updated
The following ChartLists/Spreadsheets were updated over the weekend:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Strong AD (SADCL)
- Bullish Trifecta (BTCL)
- Leading Stocks (LSCL)
- Seasonality - August (SEASCL)
- Upcoming Earnings and Upcoming Earnings Relative Strength
- Manipulation Spreadsheet
Weekly Market Recap
Major Indices
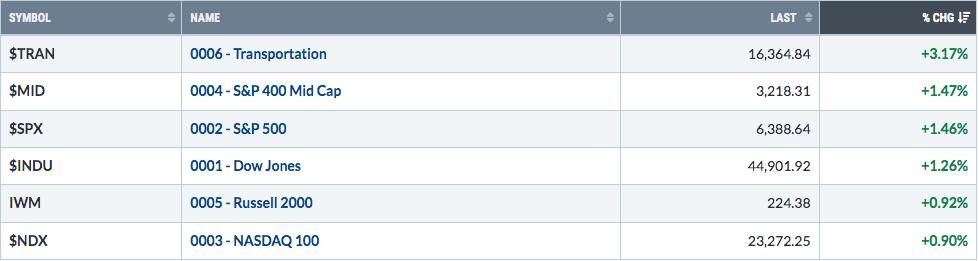
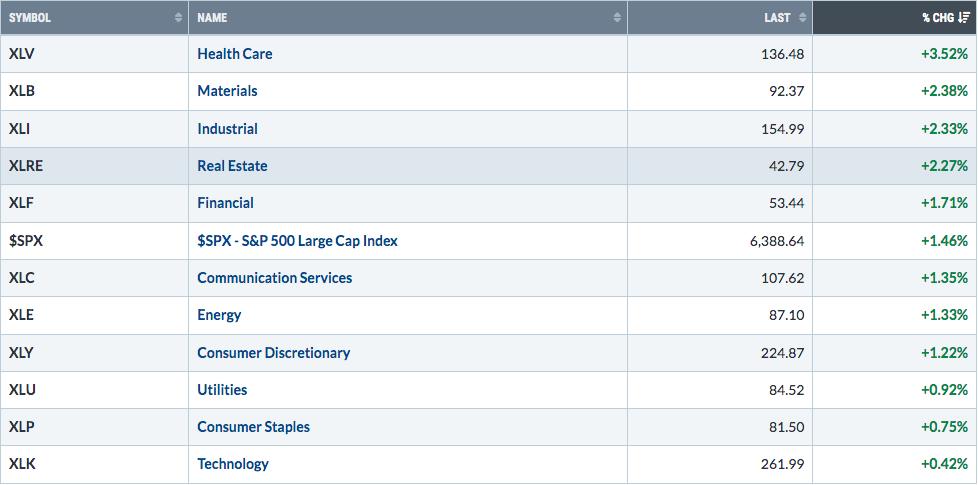
Sectors
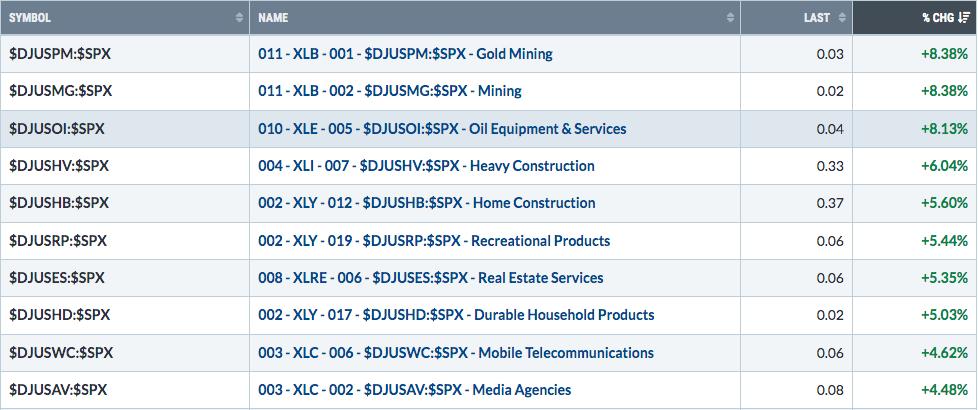
Top 10 Industries Last Week
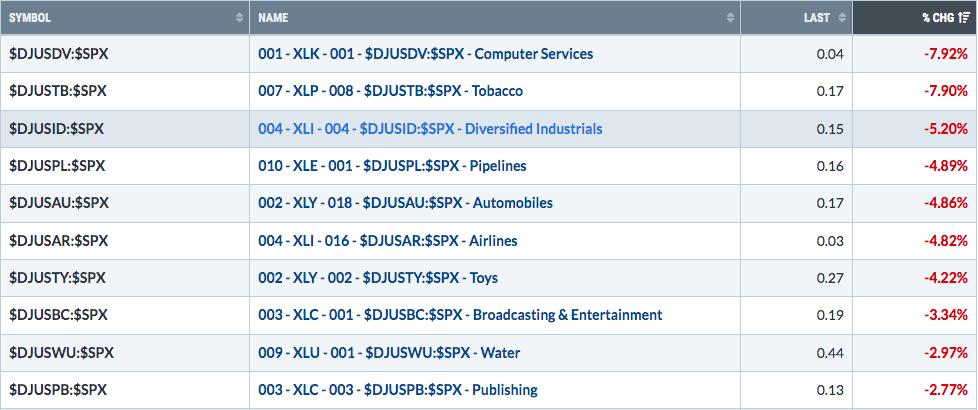
Bottom 10 Industries Last Week
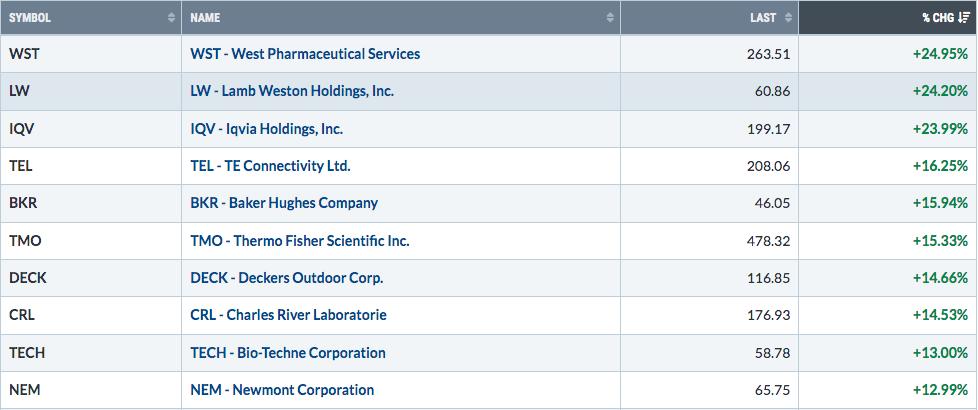
Top 10 Stocks - S&P 500/NASDAQ 100
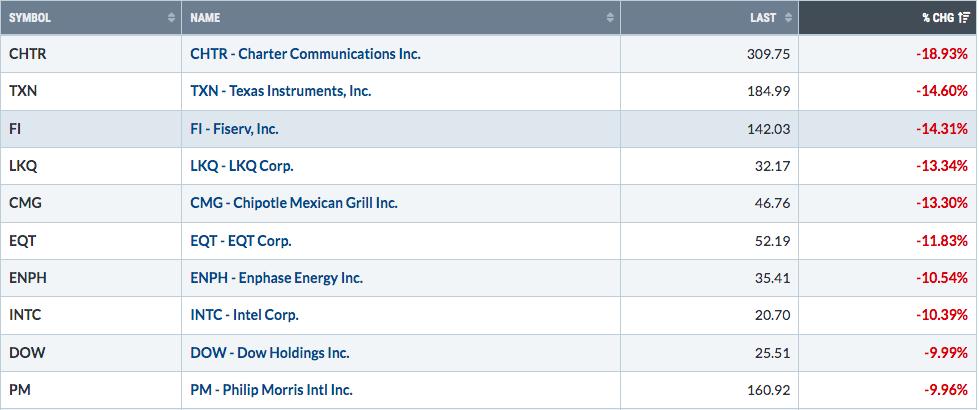
Bottom 10 Stocks - S&P 500/NASDAQ 100
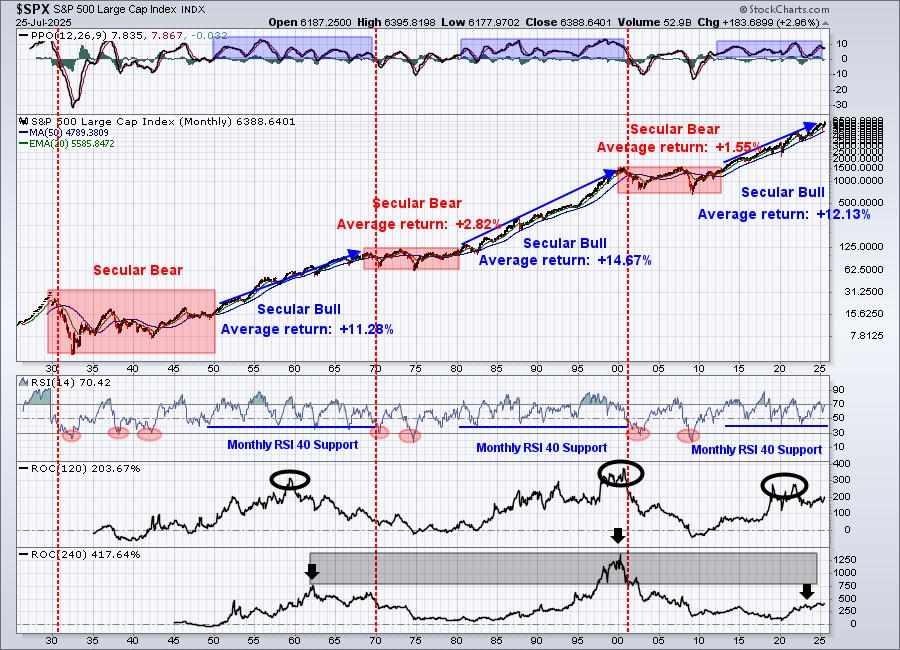
Big Picture
Earnings season has been fairly solid thus far and the market's reaction has been strong. This is typical stock market behavior during July and during the 1st half of Q3. There'll be plenty of new information this week as the next Fed meeting starts tomorrow and concludes on Wednesday. Also, the initial Q2 GDP will be out on Wednesday and 4 of the Mag 7 companies - AAPL, AMZN, MSFT, META - will be reporting their earnings either Wednesday or Thursday, after the closing bell. There is also a tariff deadline of August 1st (Friday) pending.
Oh, and did I mention that the July jobs report will be out on Friday?
While all of this could impact U.S. stocks in the near-term, long-term investors should continue to focus on the Big Picture, which remains very bullish.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
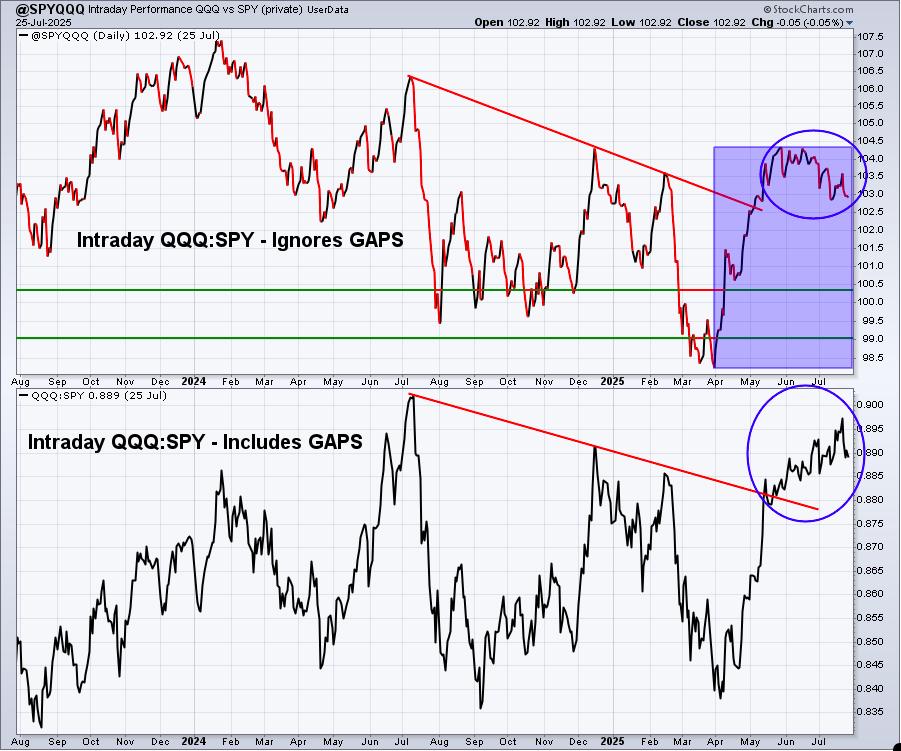
The following was a quote from the EB Weekly Market Report two weeks ago and it's how I continue to view the divergence in performance above:
"The upper panel that shows recent intraday deterioration in the QQQ:SPY ratio is a small red flag, but a red flag nonetheless. I'm generally not going to grow too bearish as long as the S&P 500 remains in a solid uptrend AND the XLY:XLP ratio (below) is trending higher and supporting the S&P 500 advance. It's ok to see a bit of rotation from the riskier NASDAQ 100 to the less risky S&P 500, so long as we're not seeing a lot of other warning signs simultaneously. I think we're perfectly fine for now."
IWM:QQQ
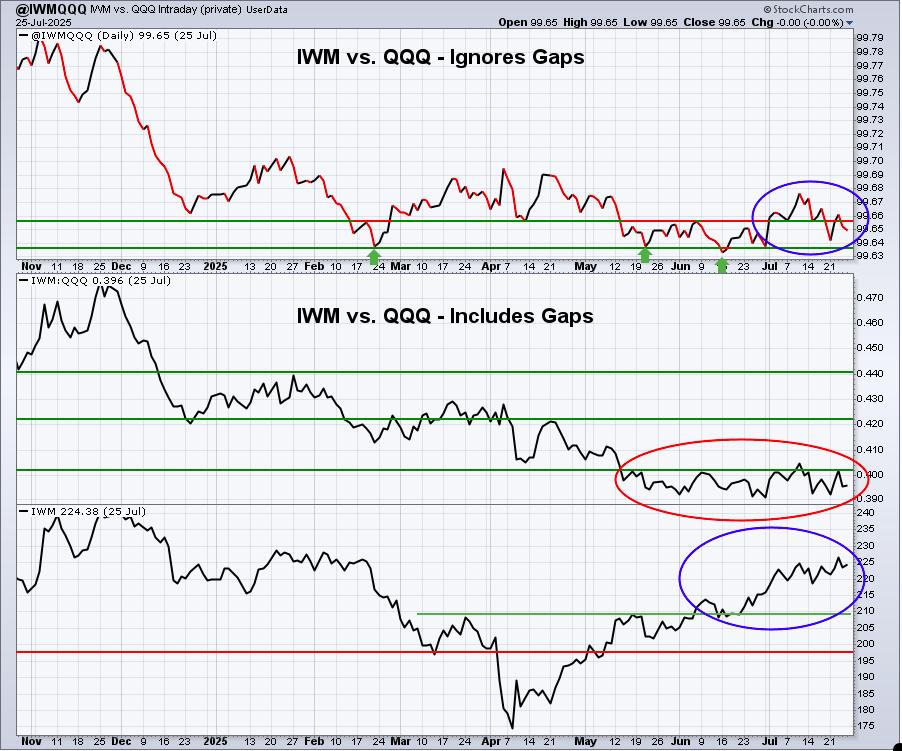
The IWM continues to trend higher, but its relative strength remains muted. Apparently, Wall Street is convinced that the Fed will not lower rates at the current meeting and they might have doubts about cutting rates at the September meeting as well. At least that's how I'd interpret the lack of relative interest in the IWM.
XLY:XLP
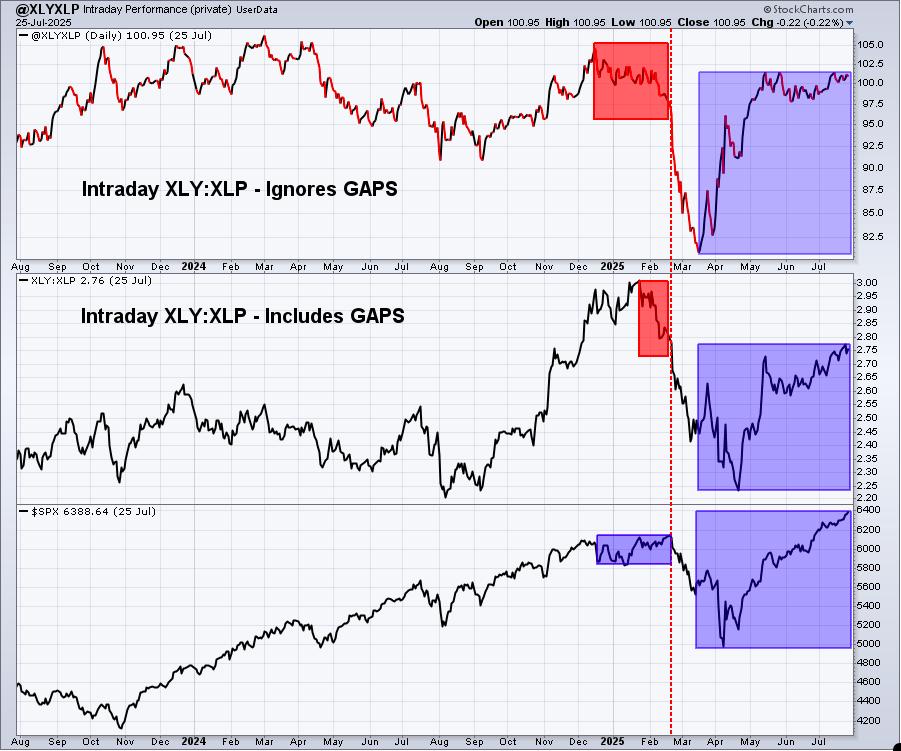
I love this chart. When I see the S&P 500 rallying and both the intraday and closing ratios on the XLY:XLP are rising as well, I simply cannot be bearish.
Sentiment
5-day SMA ($CPCE)
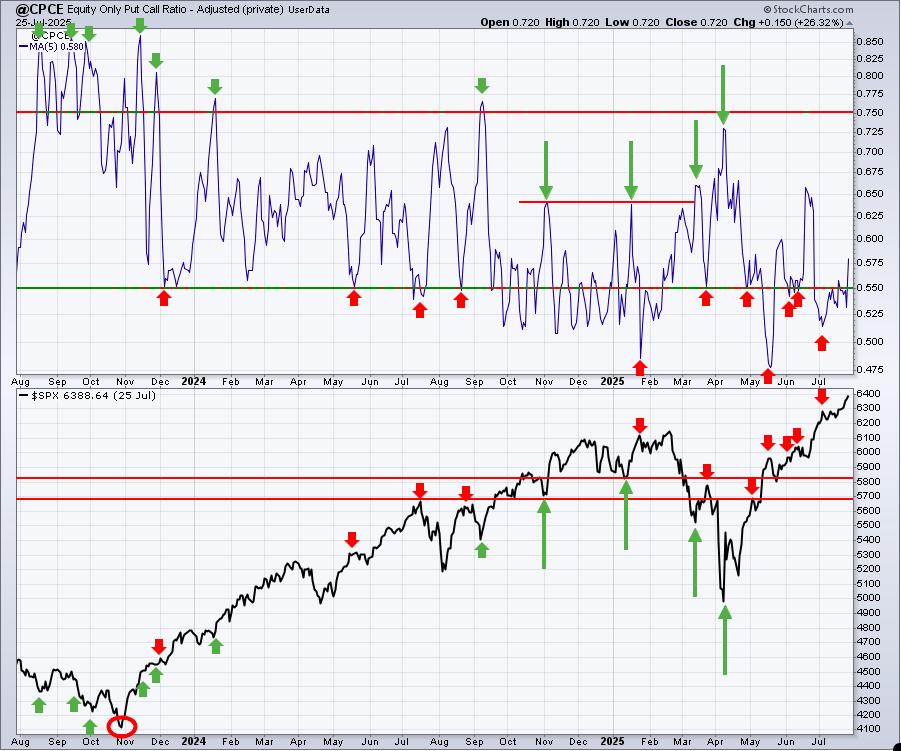
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Keep in mind that the above 5-day SMA reading of the CPCE is our "speed boat" sentiment indicator that changes quite frequently. Friday's CPCE reading moved above 70, pushing this 5-day SMA reading well into neutral territory, a positive development for stocks.
253-day SMA ($CPCE)
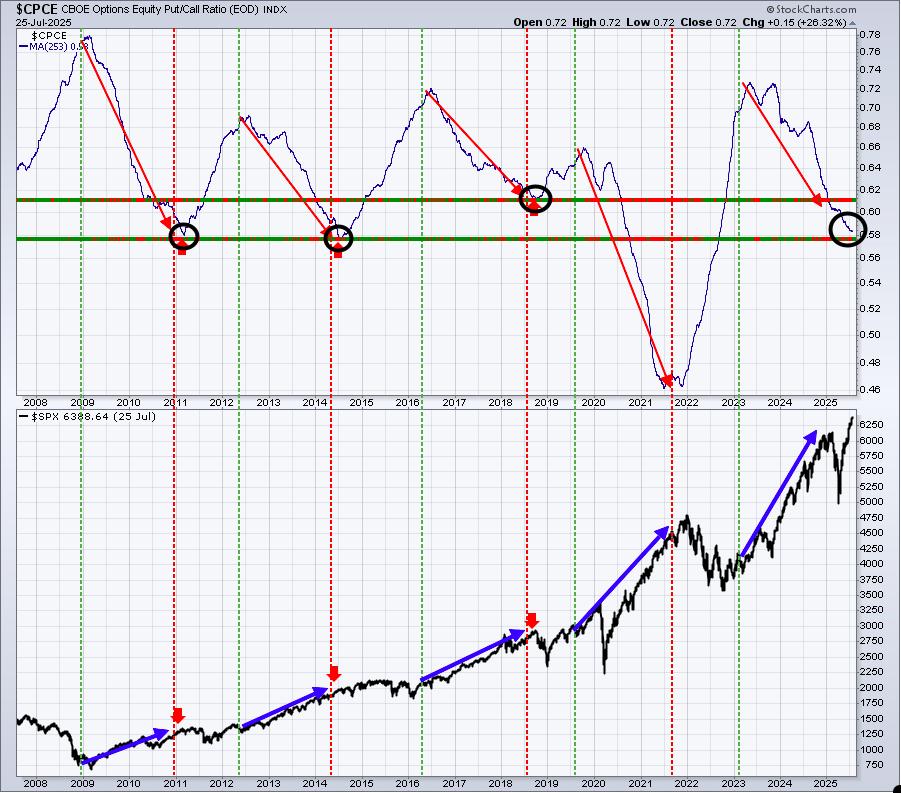
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. This one usually provides us a very solid long-term signal as the overall market environment moves from one of pessimism to complacency and vice versa. Look at the above chart. When the 253-day SMA is moving lower like it is now, it accompanies our most bullish S&P 500 moves. I cannot think about being bearish while this 253-day SMA keeps falling.
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. Below is a quick recap of how these stocks look as of one week ago:
- JPM - long-term overbought, but continuing to push higher into all-time high territory
- BA - substantial improvement continues, I could see this rally continue to 265-280 area
- FFIV - again challenging all-time high
- MA - very steady and bullish long-term performer
- GS - June turned out to be a HUGE month as GS broke back out to all-time highs
- FDX - recently failed again beneath falling 20-week EMA
- AAPL - monthly RSI bouncing off 50 as I discussed last time; seems to be back in uptrend mode
- CHRW - 85-90 is solid longer-term support and it's held that level in 2025
- JBHT - would like to see 120-125 support hold and it has, now must negotiate overhead 20-week EMA
- STX - long-term breakout in May has sent stock soaring
- HSY - strength today has it against key resistance from 175-180
- DIS - threatening major multi-year resistance level near 125; a close above would be very bullish
- MSCI - 3 1/2 year consolidation still in play; 654 is the ultimate resistance and breakout level
- SBUX - remains squarely in the middle of a wide consolidation range between roughly 70 and 115
- KRE - looking for a long-term breakout above 70, trending higher for now
- ED - successfully tested its rising 20-month EMA in both June and July
- AJG - approaching a rare 20-month EMA test, which has provided great support since 2010
- NSC - is this the breakout of a multi-year cup with handle pattern? if so, measurement is 360
- RHI - still no sign of bottom, but management recently raised its dividend, showing great confidence
- ADM - nice reversal off 43 price support, but now trying to clear its declining 20-week EMA
- BG - remains in a wide 65-75 support zone, another trying to clear its declining 20-week EMA
- CVS - looks like failed attempt to clear 50-month SMA, rolling over; major support at 43
- IPG - 22.50 support continues to hold - at least for now
- HRL - the last 18 months have been spent in a fairly narrow 27-35 range
- DE - still looks very bullish from a long-term perspective (and short-term for that matter)
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
Very few companies will report quarterly results until mid-April. The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: WELL ($106 billion), WM ($93 billion), CDNS ($89 billion)
- Tuesday: V ($653 billion), PG ($372 billion), UNH ($253 billion), BKNG ($184 billion)
- Wednesday: MSFT ($3.80 trillion), META ($1.80 trillion), QCOM ($174 billion), ARM ($169 billion)
- Thursday: AAPL ($3.19 trillion), AMZN ($2.47 trillion), MA ($514 billion), KLAC ($120 billion)
- Friday: BRK/B ($1.04 trillion), XOM ($477 billion), CVX ($272 billion)
Key Economic Reports
- Monday: None
- Tuesday: FOMC meeting begins, June wholesale inventories, May Case-Shiller home price index, May FHFA house price index, July consumer confidence, June JOLTS
- Wednesday: July ADP employment report, Q2 GDP (initial estimate), June pending home sales, FOMC announcement
- Thursday: Initial jobless claims, June personal income & personal spending, Q2 employment cost index, July Chicago PMI
- Friday: July nonfarm payrolls, unemployment report & average hourly earnings, July ISM manufacturing index, June construction spending, July consumer sentiment
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Jul 28: -21.72% (Ex: cumulative gains = -5.97% over 52 trading days. -5.97% x 253/52 = -29.02%)
- Jul 29: +37.64%
- Jul 30: +61.29%
- Jul 31: +21.91%
- Aug 1: -17.56%
- Aug 2: +10.21%
- Aug 3: +21.48%
- Aug 4: -63.32%
- Aug 5: -45.81%
- Aug 6: +8.39%
- Aug 7: +58.80%
- Aug 8: -7.13%
- Aug 9: -10.48%
- Aug 10: -34.27%
NASDAQ (since 1971)
- Jul 28: -53.85%
- Jul 29: +20.55%
- Jul 30: +30.14%
- Jul 31: +12.80%
- Aug 1: -52.16%
- Aug 2: -2.93%
- Aug 3: +32.33%
- Aug 4: -86.61%
- Aug 5: -86.71%
- Aug 6: +34.04%
- Aug 7: +67.85%
- Aug 8: -19.33%
- Aug 9: +2.58%
- Aug 10: -55.12%
Russell 2000 (since 1987)
- Jul 28: +10.48%
- Jul 29: +100.52%
- Jul 30: +61.86%
- Jul 31: -24.19%
- Aug 1: -81.03%
- Aug 2: -88.18%
- Aug 3: -31.43%
- Aug 4: -108.90%
- Aug 5: -98.23%
- Aug 6: +1.40%
- Aug 7: +62.31%
- Aug 8: +6.52%
- Aug 9: +12.38%
- Aug 10: -58.63%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Earlier, I mentioned the plethora of data and information that market participants will have to decipher throughout this week. While I expect some back and forth action, depending on the news of that day, I'm fully convinced that the path of least resistance remains higher. Over the past 8 trading sessions, the S&P 500 has closed higher 7 times. The only down session was on July 18th, when the S&P 500 fell just over one-half of a point. At last check, the S&P 500 is just a tad lower today, though it did touch 6400 for the first time in its history earlier. As we keep pushing higher and higher in equity prices, the Volatility Index ($VIX) has accelerated its descent, closing last Friday under 15 for the first time since February 14th, just before the cyclical bear market began.
Here are a few things I'll be watching this week:
- Earnings. Major earnings reports will be released, including the likes of Apple (AAPL), Microsoft (MSFT), Meta Platforms (META), and Amazon.com (AMZN). I expect we'll see mostly stronger-than-expected results, but what will the market reaction be?
- The Fed. The Fed is holding one of its eight meetings of 2025 this week. It is widely expected that rates will remain unchanged once again. However, a couple of Fed officials have begun indicating that they're in favor of a rate cut, so the discussion this week could be lively.
- Economy. Q2 GDP and nonfarm payrolls will be out within two days of one another. Did the negative GDP number for Q1 carry over into Q2? Or did the economy rebound? If so, how strongly did it rebound? Everyone will be searching for economic clues and there'll be plenty of those to analyze.
- Tariffs. The latest tariff deadline is August 1st. There's already talk of US-China trade talks being pushed back further. Will we continue to kick the can down the road for many countries, including China? Will it matter?
Happy trading!
Tom