
EB Weekly Market Report - Monday, January 26, 2026
ChartLists/Spreadsheets
The following ChartLists/Spreadsheets were updated over the weekend:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL)
- Key Manipulation Spreadsheet
The above ChartLists and spreadsheet were updated through last Friday, despite the Winter Storm that just moved through our area. You can view and/or download these ChartLists from our website, and also read about them to gain a better understanding of how they can help in your trading success.
Weekly Market Recap
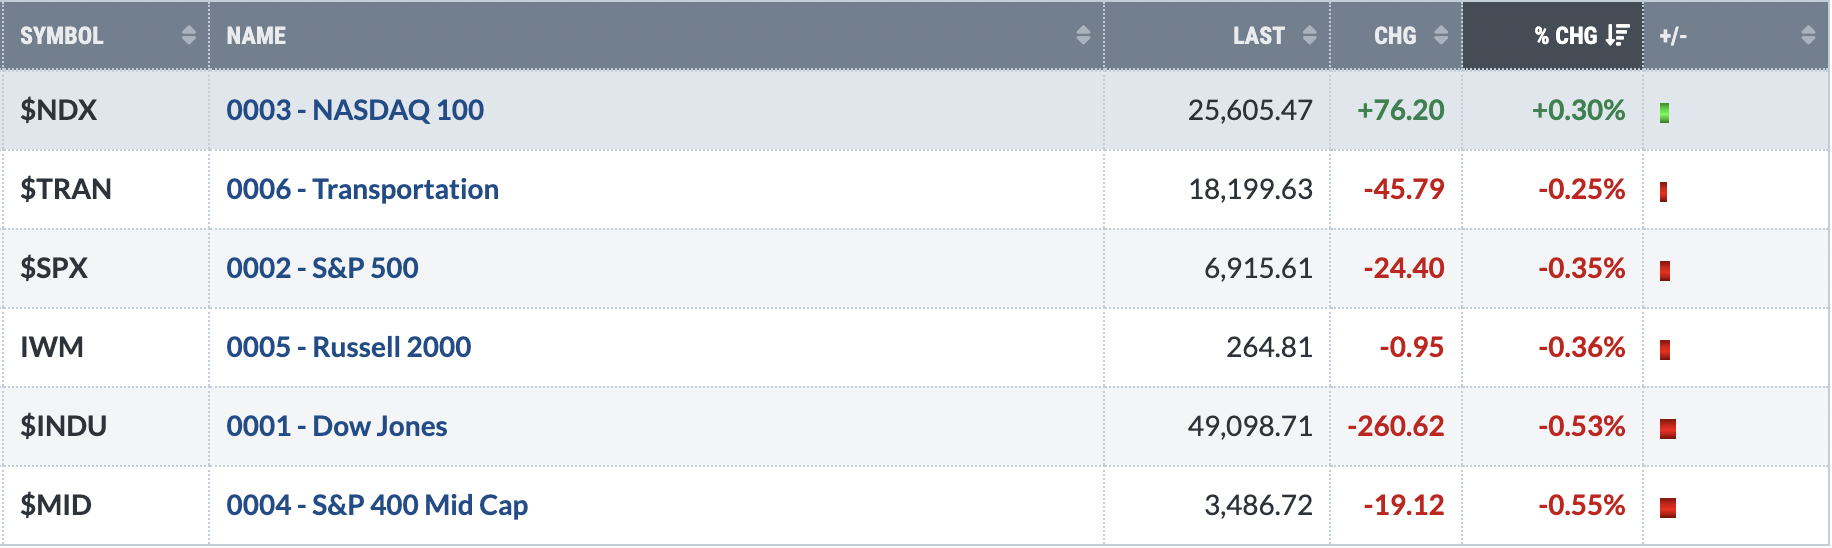
Major Indices
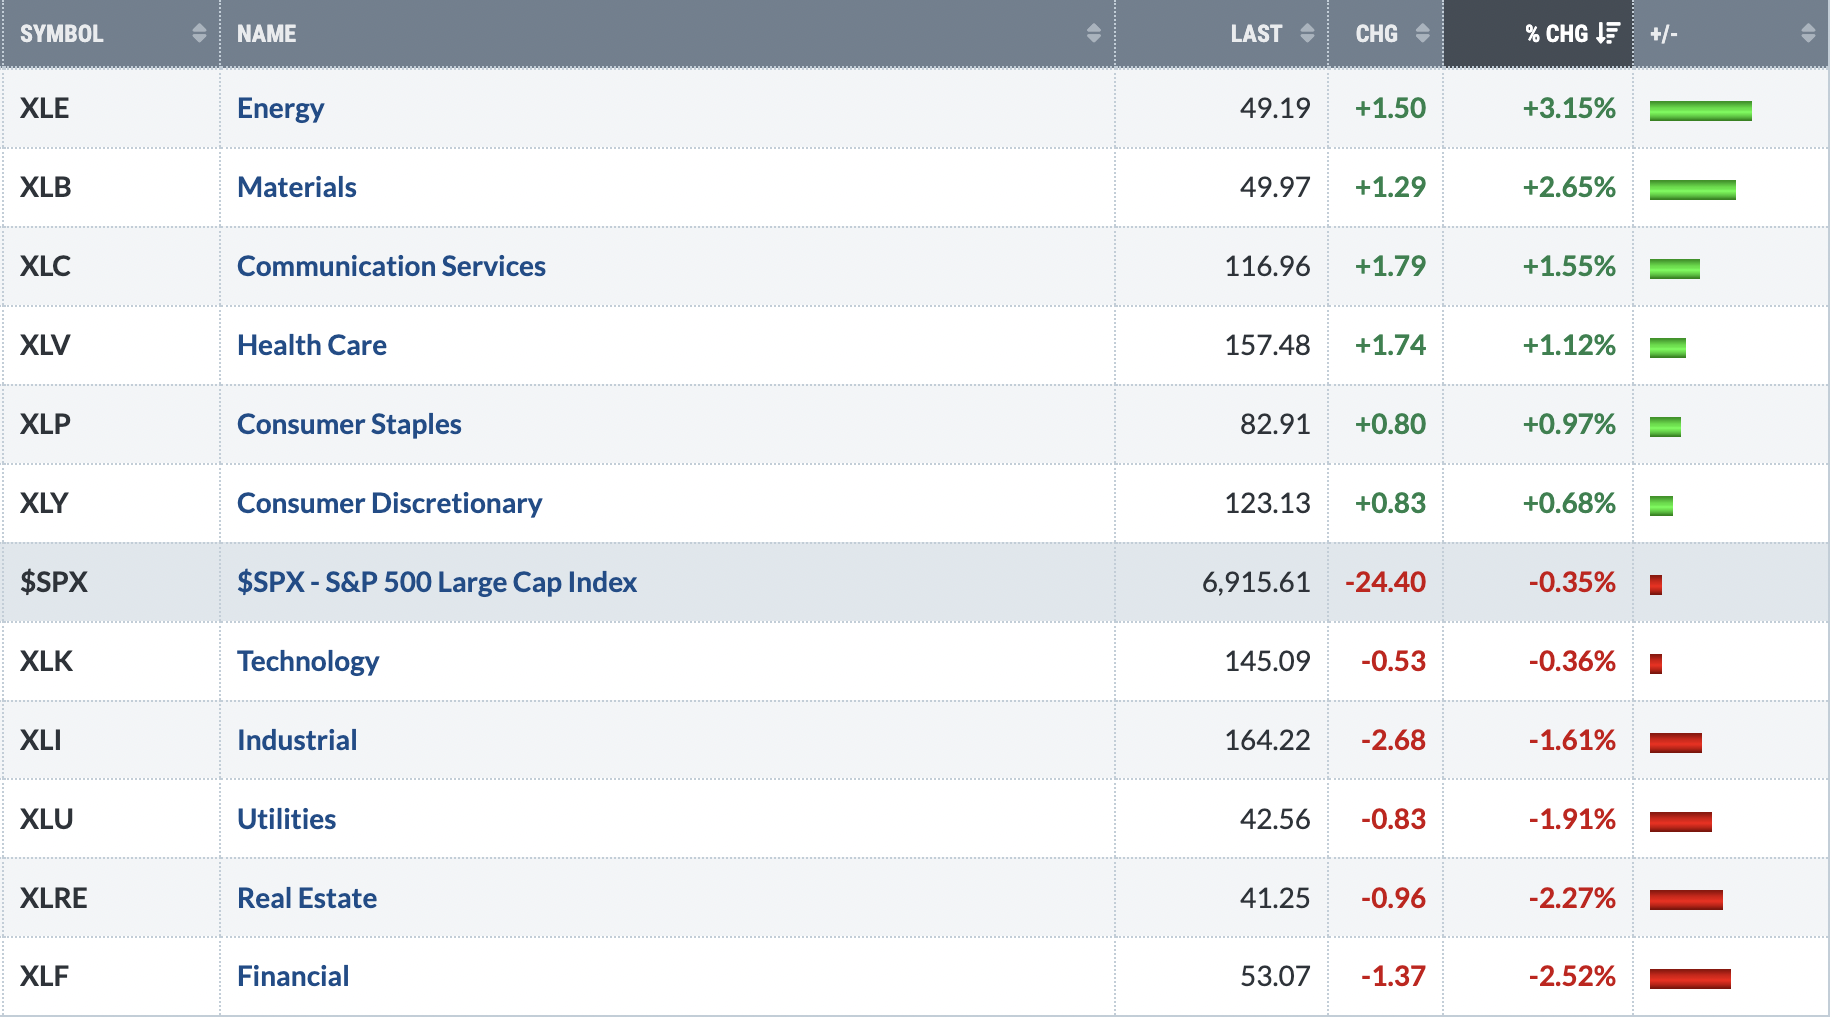
Sectors
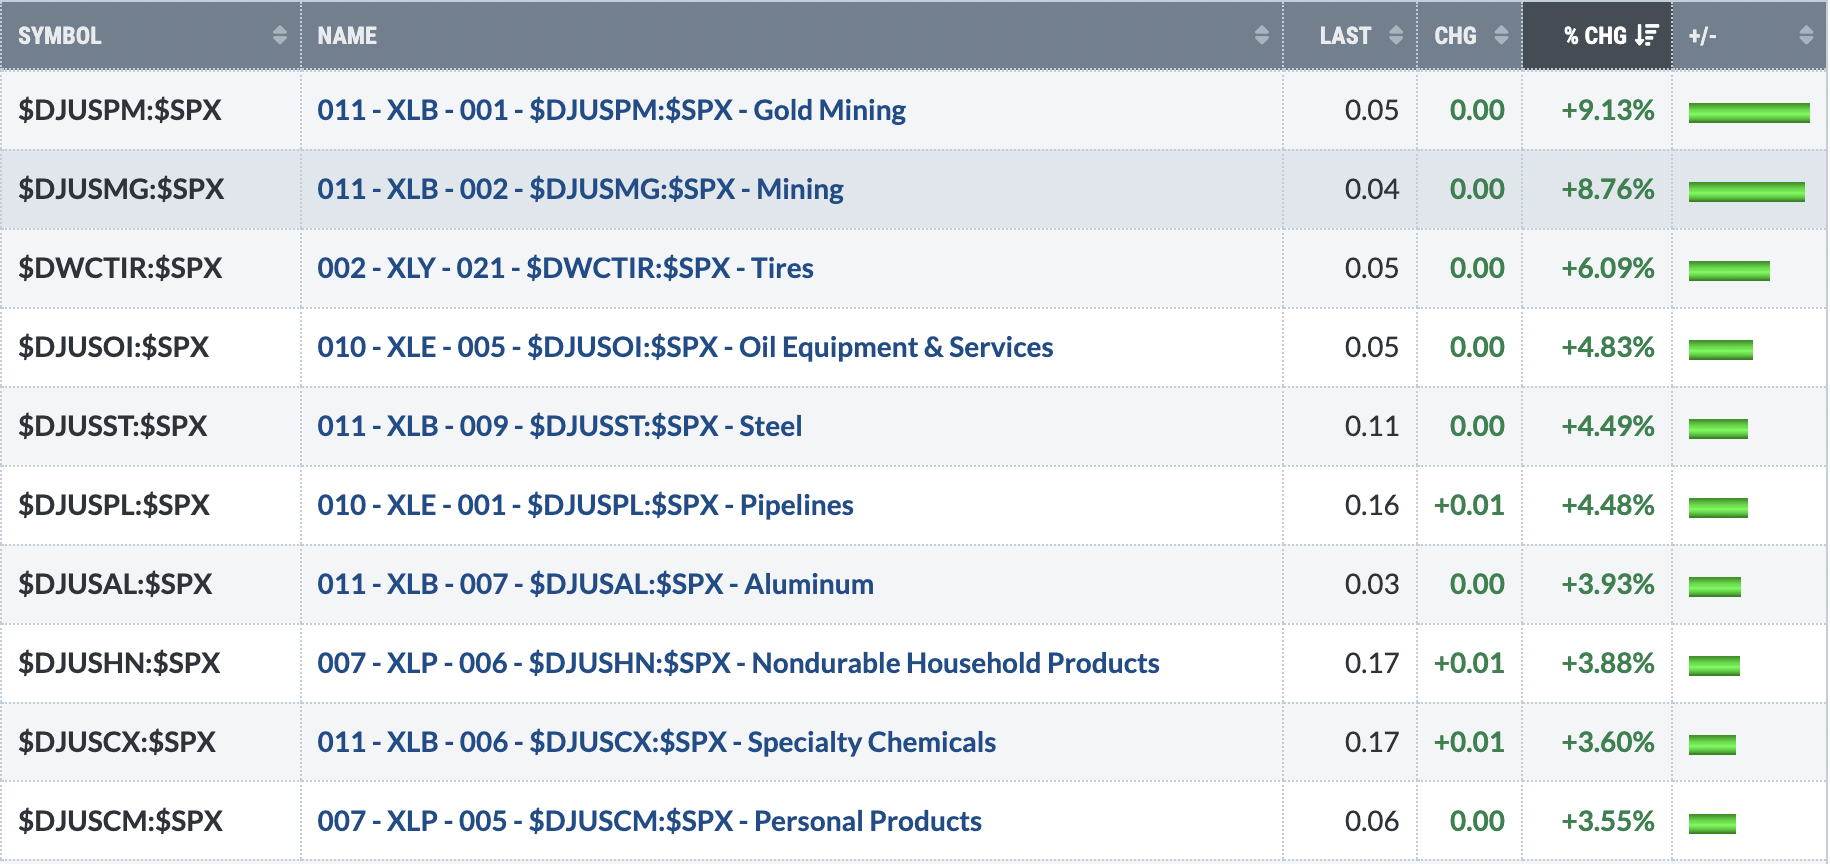
Top 10 Industries Last Week
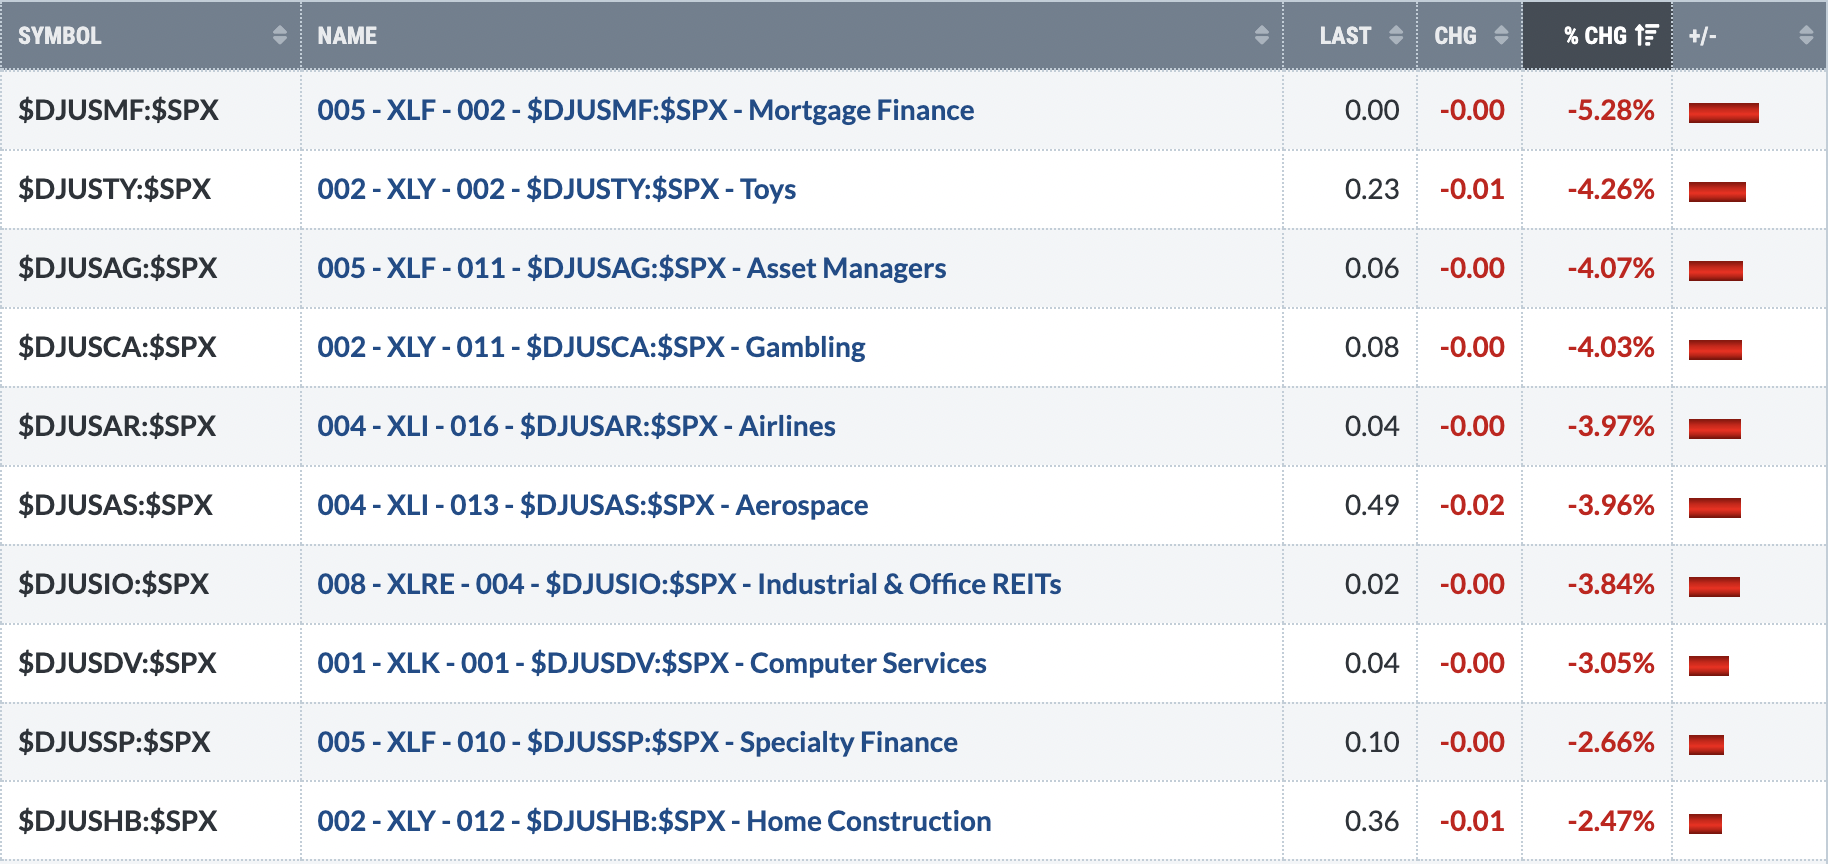
Bottom 10 Industries Last Week
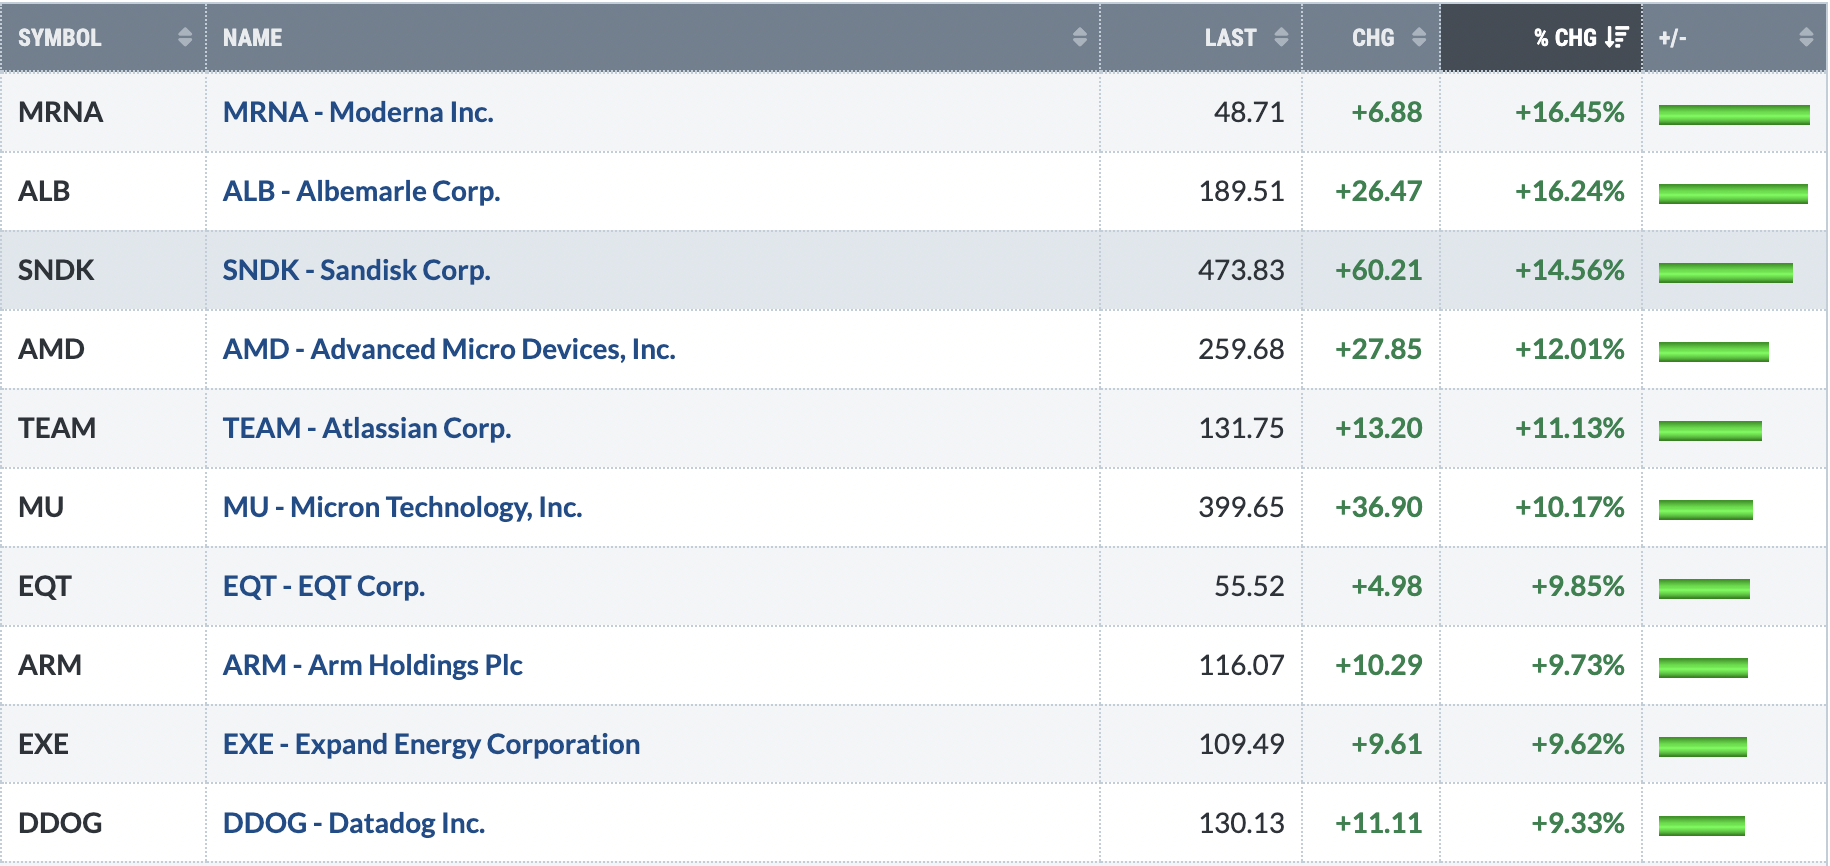
Top 10 Stocks - S&P 500/NASDAQ 100
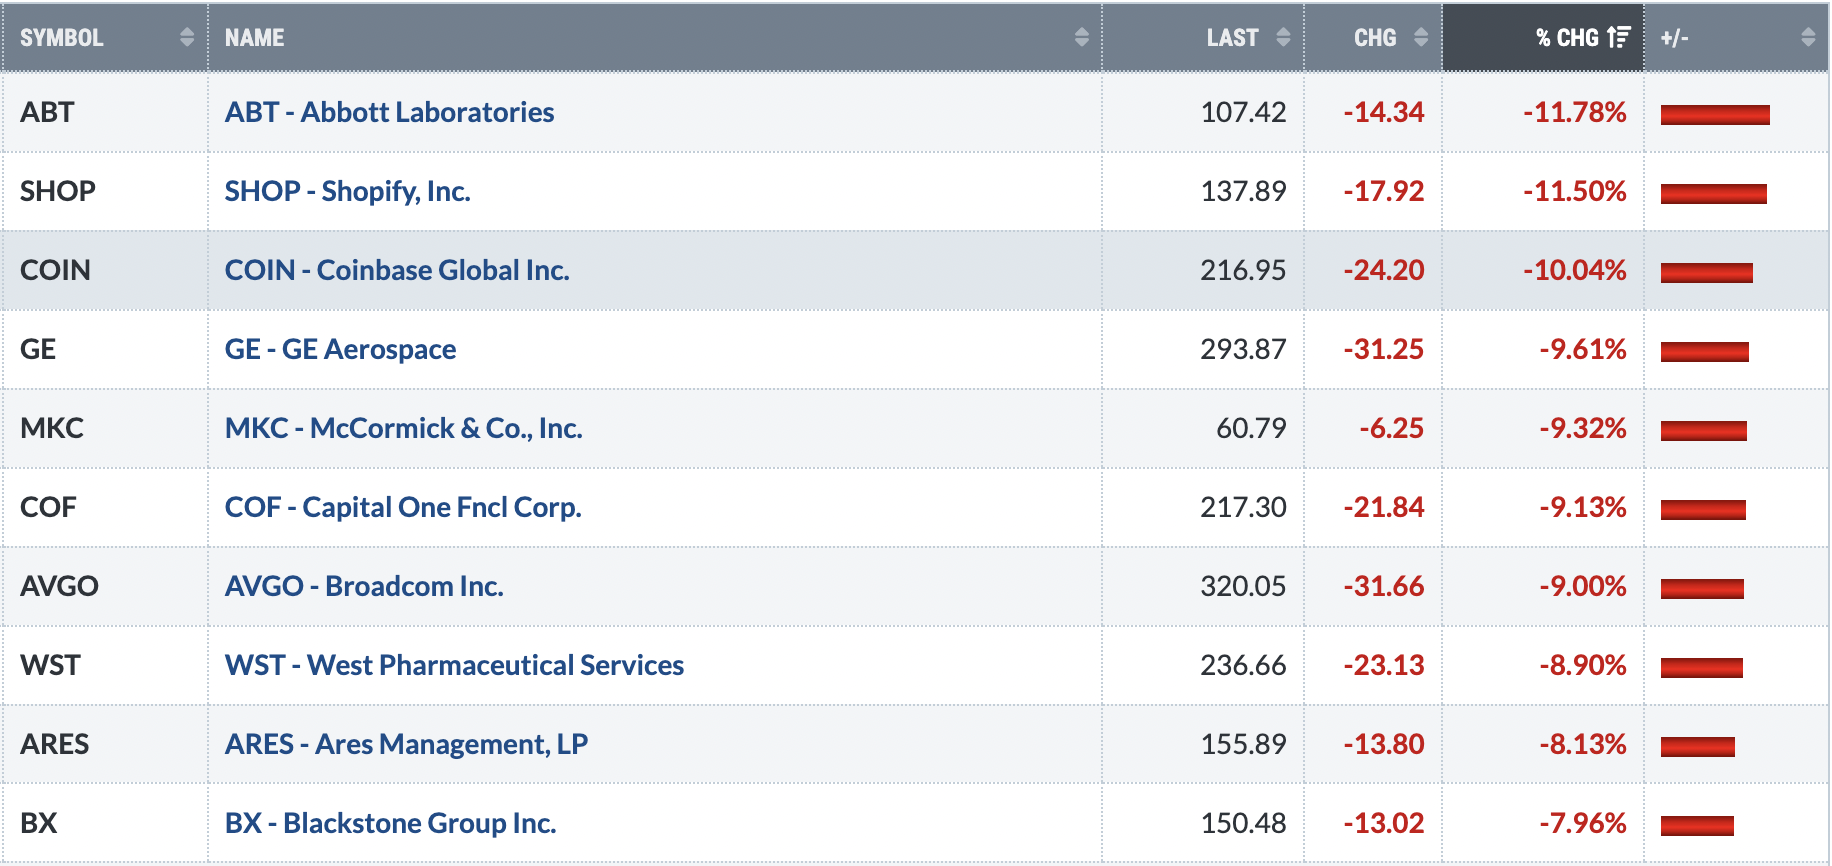
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
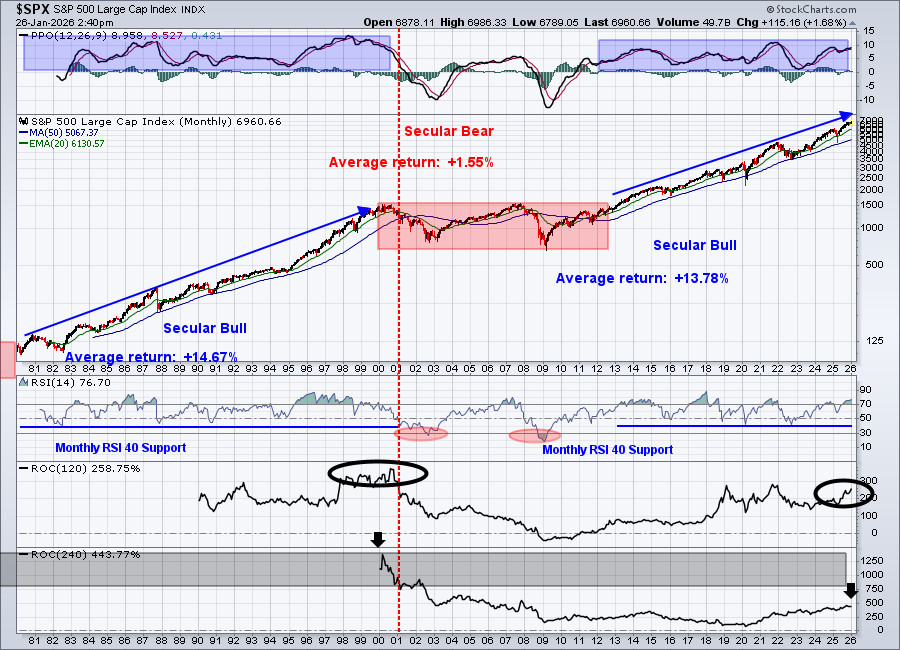
Nothing has changed, either short-term or long-term. I still see short-term warning signs that are more applicable for short-term traders. I also still see the S&P 500 going much, much higher over time - great news for long-term investors.
All of our major indices are pushing up to or near all-time highs, but the large cap indices (S&P 500 and NASDAQ primarily) have struggled due to the relative weakness found in many of the Mag 7 stocks. It's difficult for the major indices to move higher when their highest-weighted stocks aren't. That's what's facing the market right now. Either the Mag 7 needs to rebound to push the major indices to new highs OR the weight of the struggling Mag 7 names could become too much of a weight to bear, leading to a decline, possibly even a correction.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
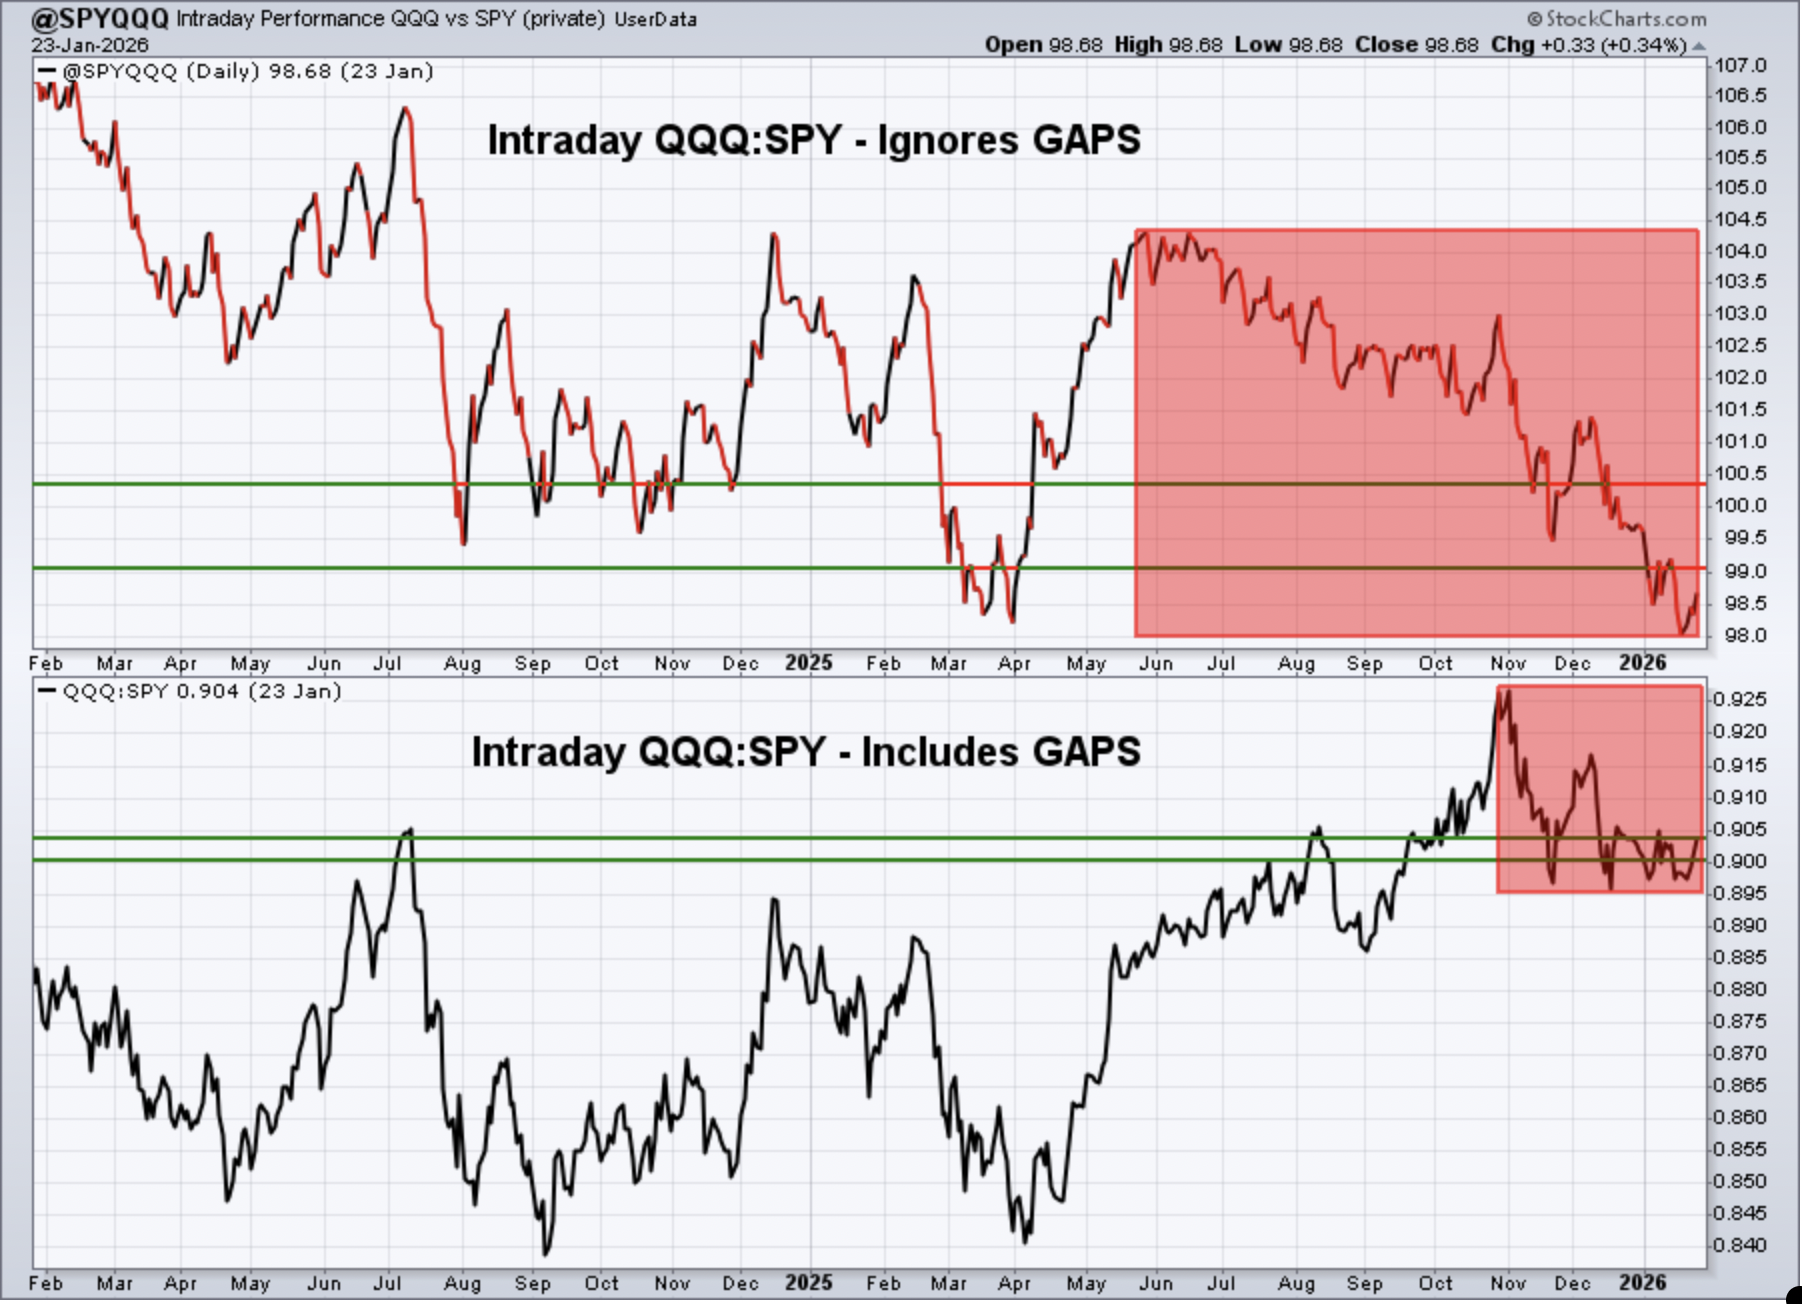
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
There are no real changes here. Growth continues to lag value, and that's the opposite of what historically drives secular bull markets higher.
IWM:QQQ
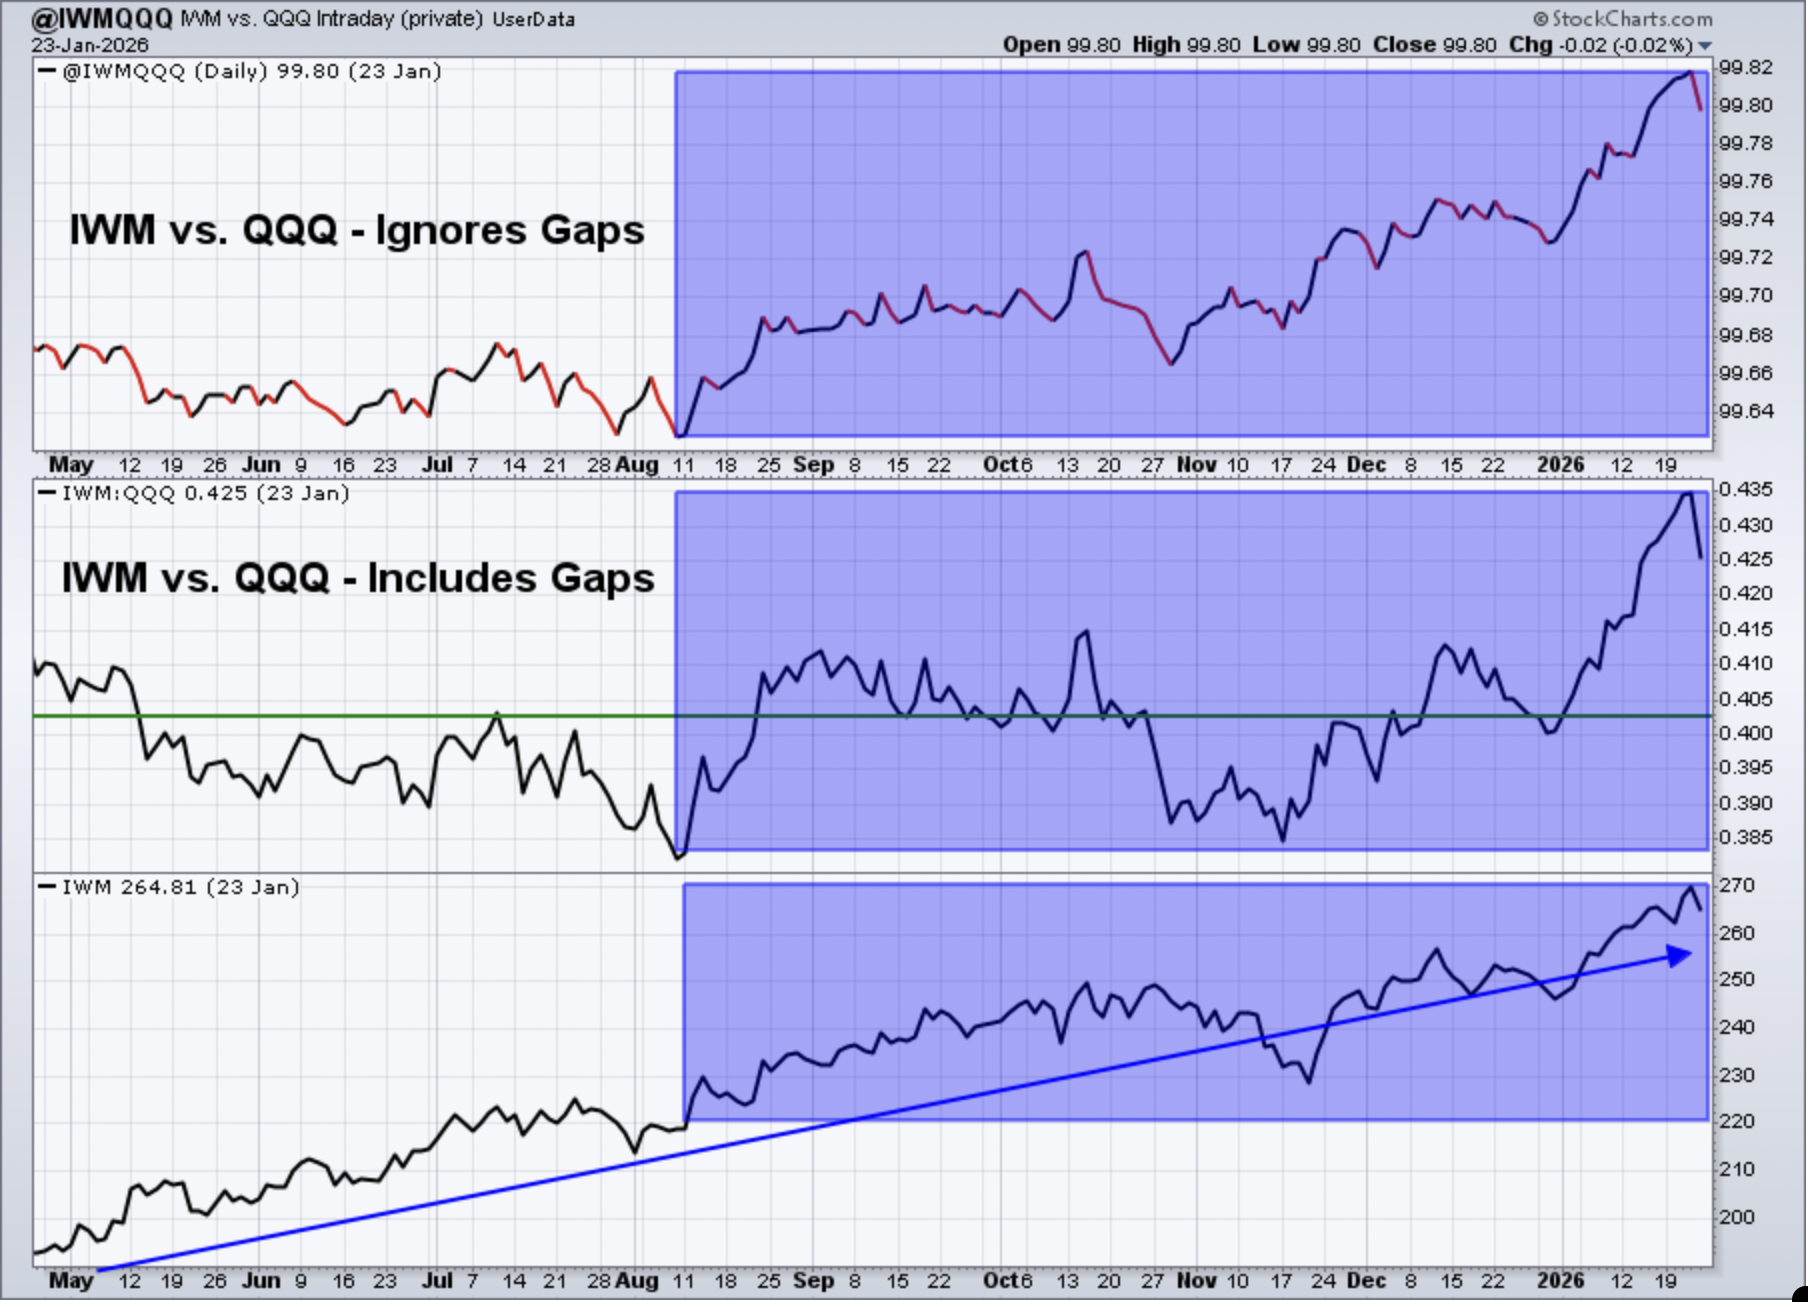
Small caps fell back a bit late last week vs. their large cap counterparts. After several weeks of outperformance, however, it's fine to see a bit of profit taking in the asset class. I'd expect to see renewed strength ahead after a brief resting period.
XLY:XLP
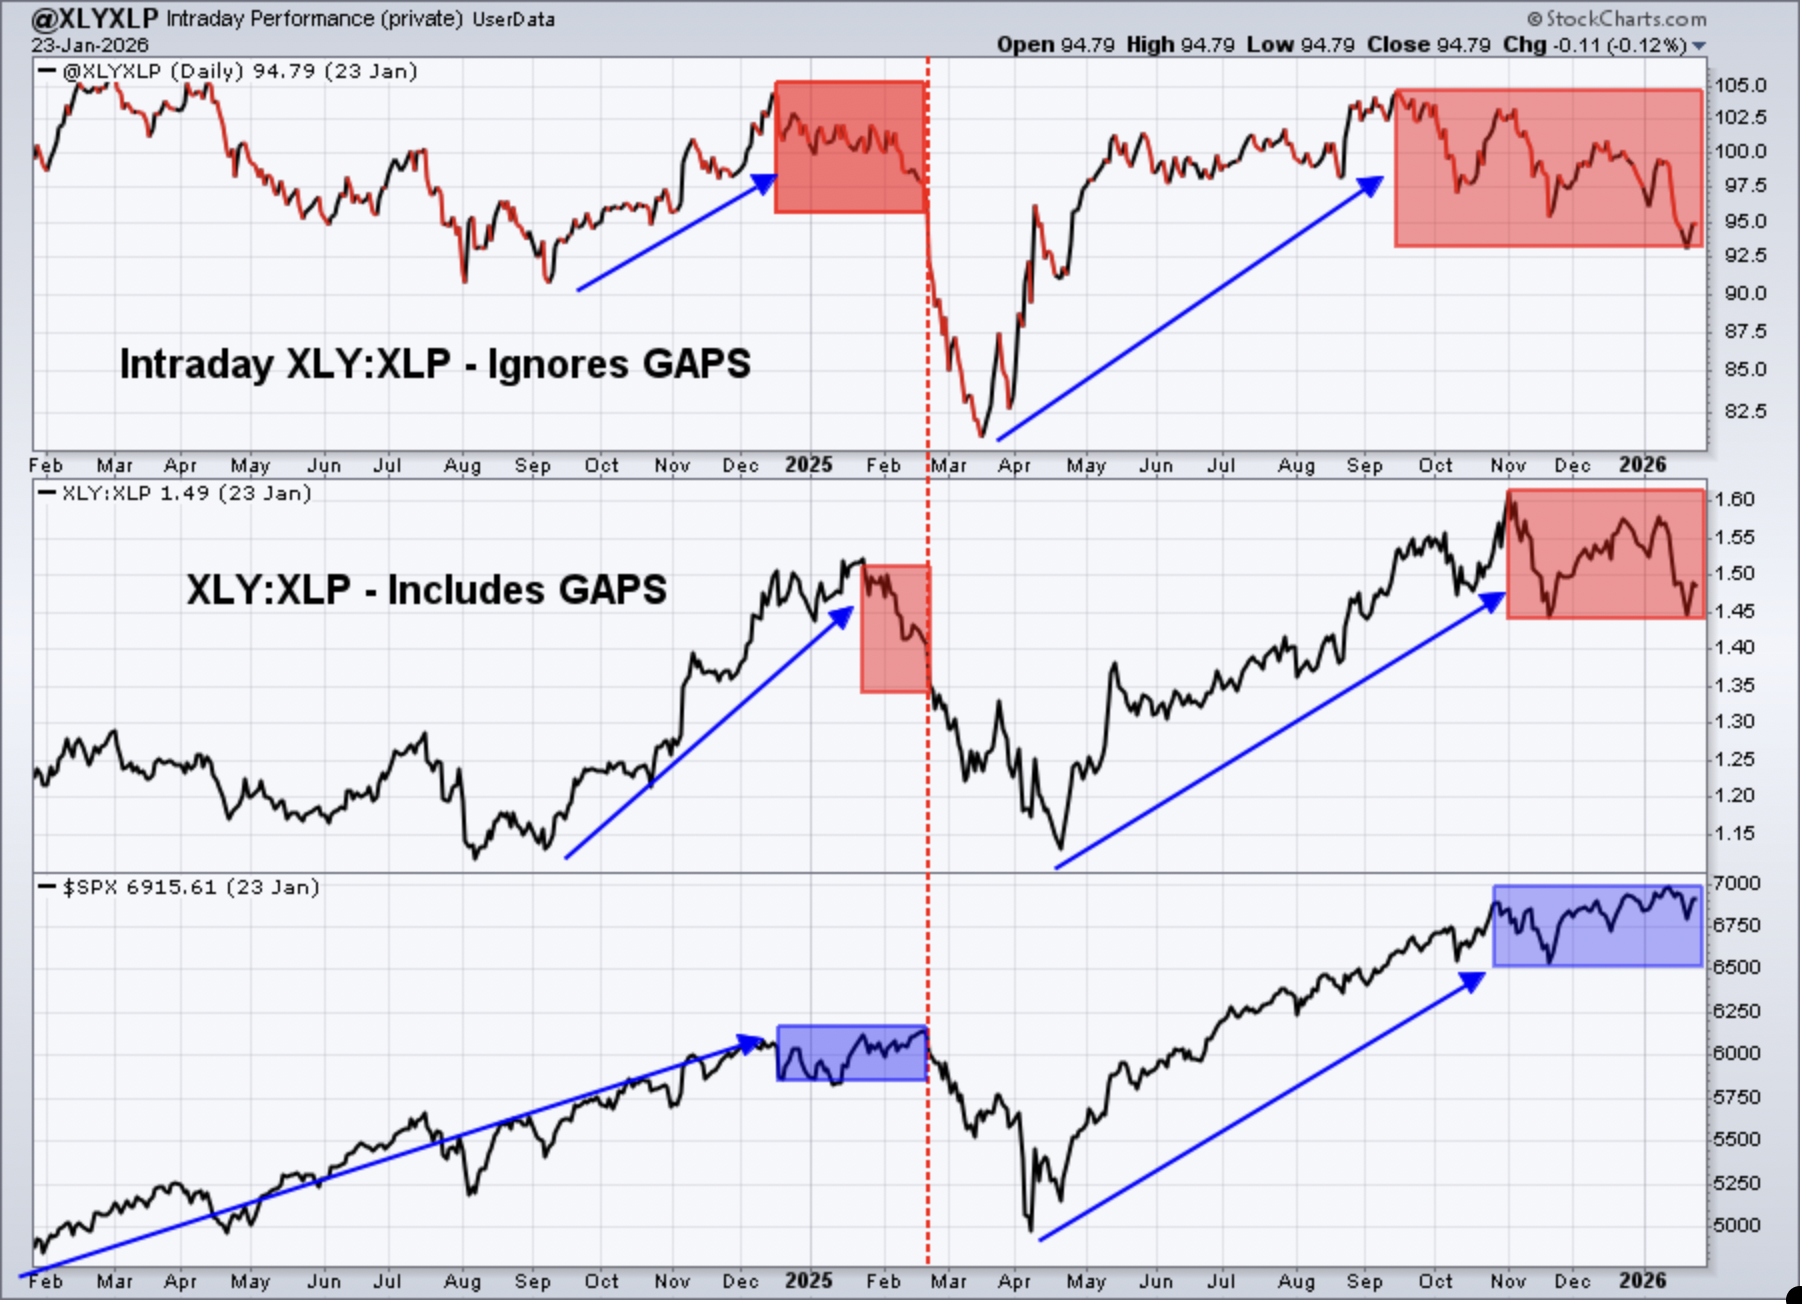
There was stabilization in this ratio last week, which was calming. However, a lot of damage has already been inflicted in consumer stocks. The clear test will be whether discretionary can bounce back vs. staples on an intraday basis. In my opinion, it's a necessity to truly drive another healthy secular bull market advance.
Sentiment
5-day SMA ($CPCE)
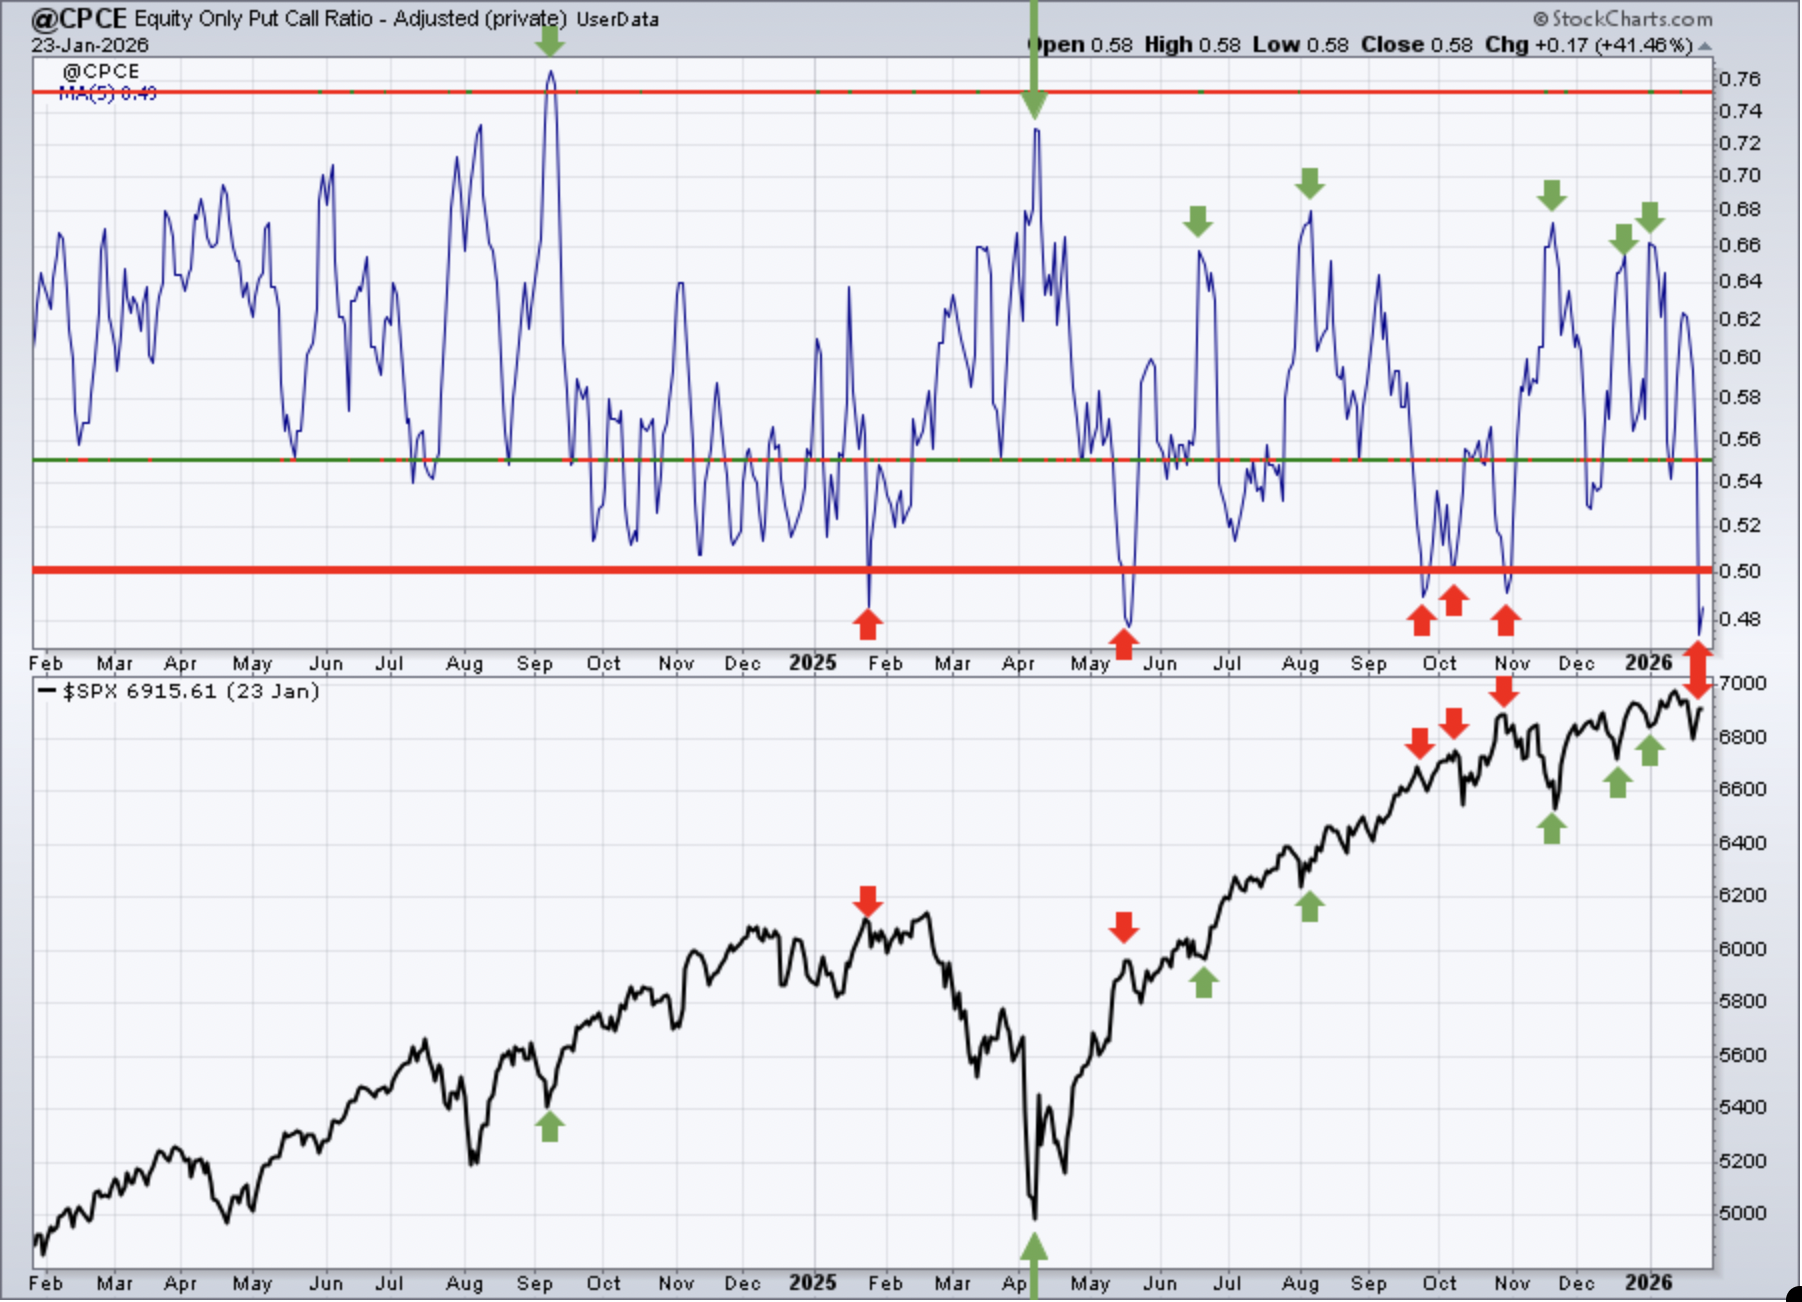
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Keep in mind that the above 5-day SMA reading of the CPCE is our "speed boat" sentiment indicator that changes quite frequently. While the .75+ level has been where many short-term bottoms have occurred in the past, the .65 or so level has been marking short-term bottoms in 2025 and 2026. Last week's strength had the options bulls out in full force with a couple very low daily readings in the 5-day CPCE, with one reaching 0.41. The 5-day CPCE reached a level typically found with short-term market tops. It'll be interesting to see if that's the case this time.
253-day SMA ($CPCE)
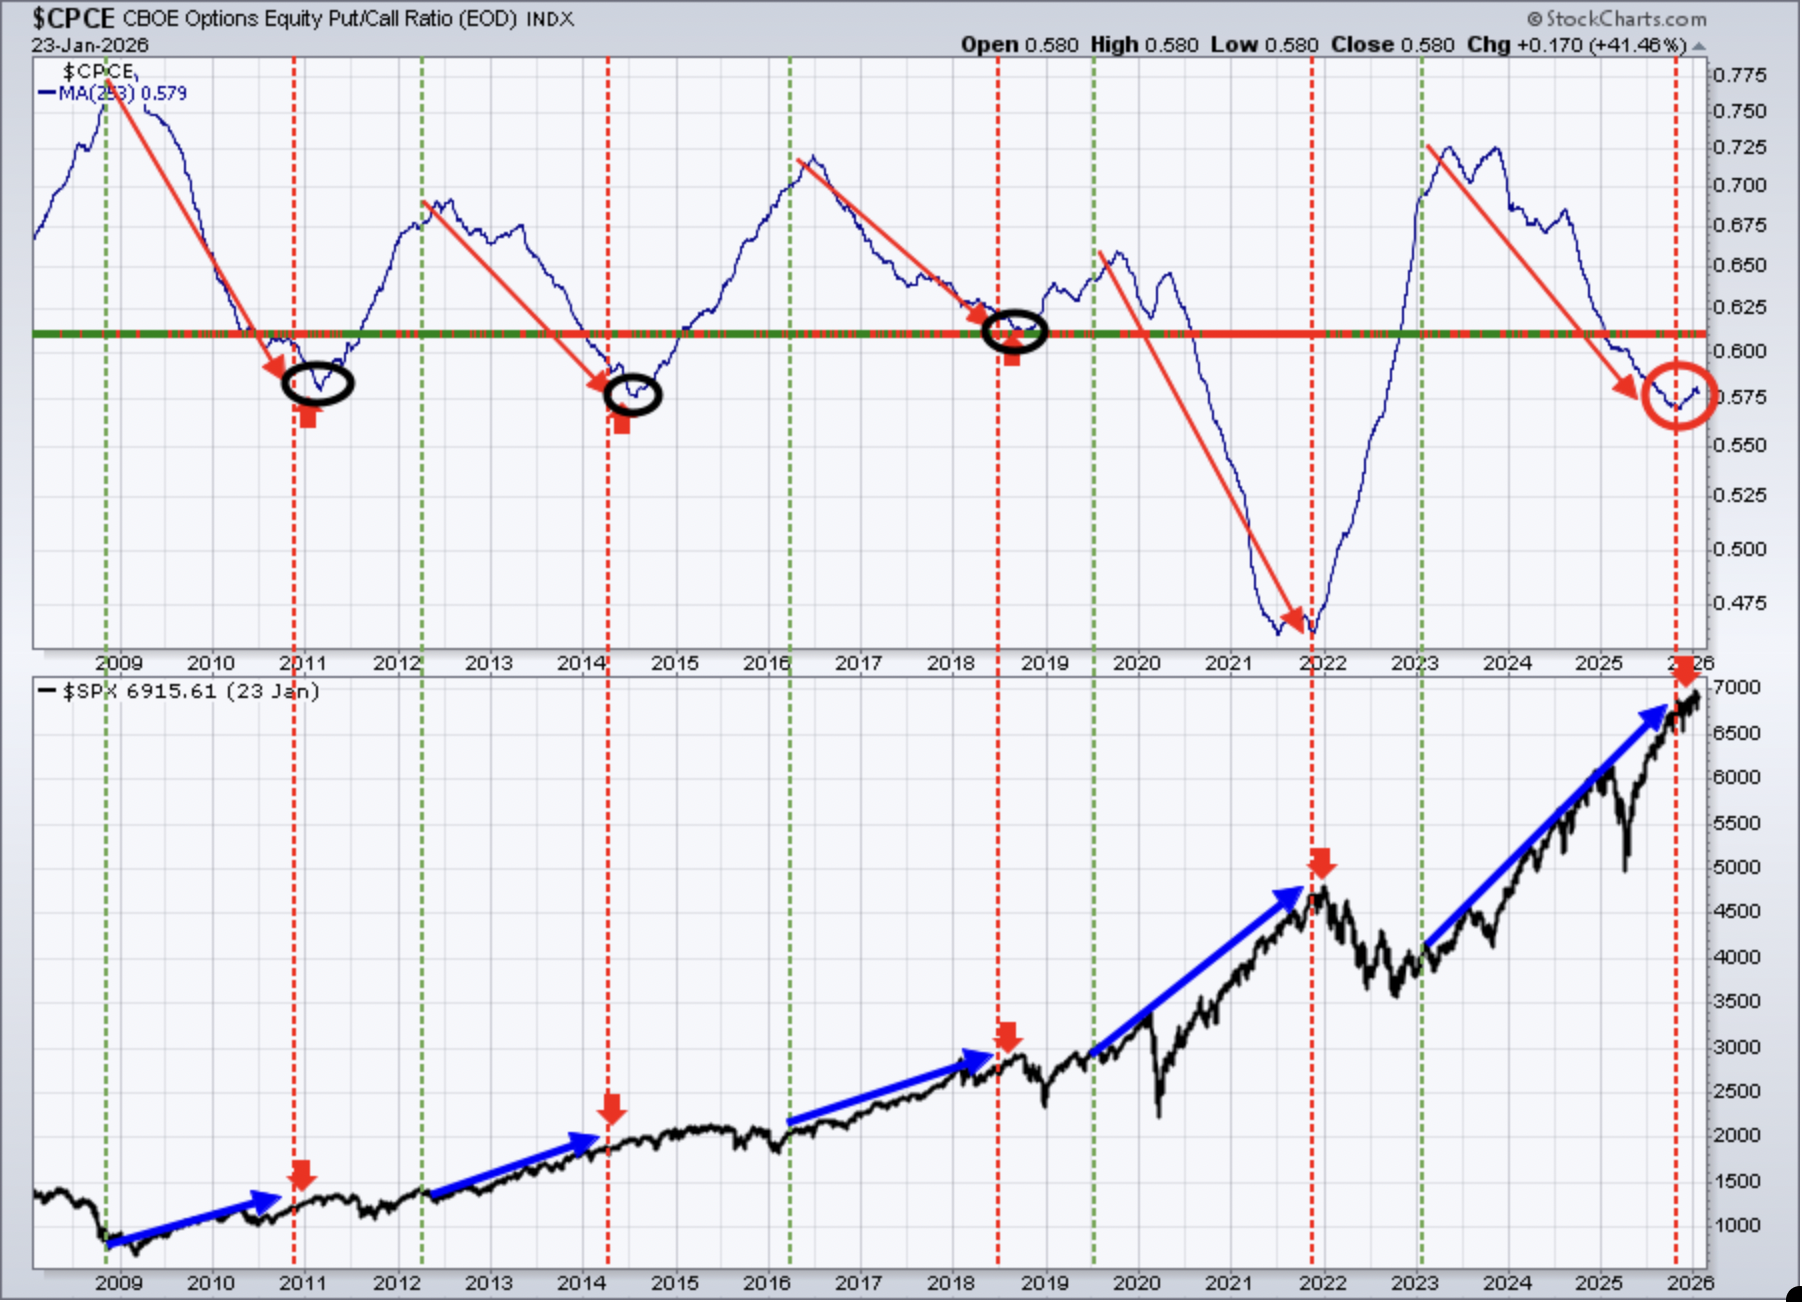
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500. I wouldn't want to bet against what this indicator is telling us, which is that we should be cautious in 2026. For the first time since mid-2025, we are clearly seeing this 253-day SMA turn back higher. That suggests that sentiment may have bottomed and that pessimism will begin to return to higher levels over time. That nearly always occurs when stock prices are declining or, at a minimum, consolidating.
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month or so and I updated them last week. Below is a quick recap of how these stocks looked as of Monday, January 12th:
- JPM – monthly PPO could be rolling over after a strong 3-year run
- BA – attempting to close at highest weekly level in over two years
- FFIV – tested its April low, rebounded and is now testing 20-week EMA
- MA – key price support remains near 525
- GS – has more than doubled since April low; very overbought on monthly chart
- FDX – just breaking out to all-time high
- AAPL – recent weakness has resulted in bullish 20-week EMA test
- CHRW – another that has now doubled off April low; very overbought
- JBHT – surge continues; key overhead resistance is from 210-215
- STX - extremely overbought and negative divergence is now on weekly chart
- HSY – rallying again, but 200 price resistance remains critical for now
- DIS – multi-year consolidation remains; needs to clear 125
- MSCI – been in fairly tight 520-590 range since rallying off April low
- SBUX - looking to close over 90 this week for the first time since August
- KRE – excellent uptrend since October, looking to clear 68-70 resistance
- ED – bounced again off 95 support; currently in 95-105 range
- AJG – bouncing on weekly chart, but 20-week EMA and 280 are resistance
- NSC – love the long-term chart, 270-300 is current range
- RHI – did 25 mark the bottom? First bullish step is close over 20-week EMA
- ADM – weekly chart solid, breakout above 64.50 is next key
- BG – bounced off 20-week EMA support and broke out again; 109 next?
- CVS – continues to trend higher and above rising 20-week EMA
- IPG – acquired by Omnicom Group (OMC); will no longer track this one
- HRL - moved back up to test 25 resistance and failed, currently in 21-25 range
- DE – needs to clear 500, then 530; 430-440 is support range
- LULU - cleared 20-week EMA, that is now huge support
- TTD - lost support at 39-40, struggling to clear that resistance level now
- META - as mentioned last month, can it clear its falling 20-week EMA?
- ADBE - looks like potential reversing right shoulder, but new low would negate
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: NUE ($42 billion)
- Tuesday: UNH ($321 billion), RTX ($263 billion), BA ($191 billion), TXN ($177 billion)
- Wednesday: MSFT ($3.35 trillion), META ($1.63 trillion), TSLA ($1.49 trillion), LRCX ($277 billion), APH ($187 billion)
- Thursday: AAPL ($3.65 trillion), V ($595 billion), MA ($479 billion), CAT ($303 billion)
- Friday: XOM ($564 billion), CVX ($336 billion), AXP ($254 billion)
Key Economic Reports
- Monday: November durable goods (delayed)
- Tuesday: January consumer confidence
- Wednesday: FOMC policy statement
- Thursday: Initial jobless claims, Q3 productivity, November wholesale inventories (delayed), November factory orders (delayed)
- Friday: December PPI (delayed), January Chicago PMI
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Jan 26: +29.56% (Ex: cumulative gains = +6.31% over 54 trading days since 1950. +6.31% x 253/54 = +29.56%)
- Jan 27: +0.64%
- Jan 28: +57.59%
- Jan 29: +18.30%
- Jan 30: +4.64%
- Jan 31: +70.43%
- Feb 1: +47.30%
- Feb 2: +45.54%
- Feb 3: +32.29%
- Feb 4: -14.94%
- Feb 5: -34.10%
- Feb 6: +34.30%
- Feb 7: +7.17%
- Feb 8: -36.33%
NASDAQ (since 1971)
- Jan 26: +45.80%
- Jan 27: -62.78%
- Jan 28: +93.44%
- Jan 29: +10.57%
- Jan 30: -7.03%
- Jan 31: +83.40%
- Feb 1: +119.96%
- Feb 2: +37.65%
- Feb 3: +30.20%
- Feb 4: -5.10%
- Feb 5: -24.49%
- Feb 6: +66.99%
- Feb 7: -13.89%
- Feb 8: +9.50%
Russell 2000 (since 1987)
- Jan 26: +74.67%
- Jan 27: -95.74%
- Jan 28: +40.38%
- Jan 29: +1.76%
- Jan 30: -74.34%
- Jan 31: +104.07%
- Feb 1: +198.28%
- Feb 2: +21.08%
- Feb 3: +57.79%
- Feb 4: -36.03%
- Feb 5: -32.89%
- Feb 6: +74.45%
- Feb 7: +10.71%
- Feb 8: +29.93%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
The bulls had a solid week last week, but mostly due to commodities. Mining stocks remained on fire and energy stocks jumped on board as well. Still, technology is struggling and that's going to be a problem given its huge weighting in both the S&P 500 and especially the NASDAQ 100.
Here are a few things I'll be watching this week:
Inflation and the 10-Year Treasury Yield ($TNX). After gapping higher to open last week, the TNX fell throughout the week and it's down again today. The November PPI will be released later this week and the Fed will announce its latest interest rate decision, which will most likely be no change. But what will the Fed say? Has anything become more visible for them? Remember the stock market reacts as much to what it believes the Fed will do down the road as it does to what the Fed does this week.
January Effect. This week's performance could send the S&P 500 up in terms of relative January performance.....or not. As I've been discussing recently, balance-of-year performance has often been tied to January performance. Hence, the Wall Street adage, "as goes January, so goes the year." This is the final week of January. Let's see how we finish out the month.
Earnings. This is going to be a HUGE week for earnings. Any time you have 4 of the Mag 7 stocks (AAPL, MSFT, META, TSLA) reporting in the same week, there is a formula for a potentially big move in our major indices one way or the other. Of the 4 shown, only MSFT is leading its peer group. AAPL and META are both at or near 52-week relative lows vs. their peers and TSLA is near a multi-month relative low. In my opinion, this increases the possibility of not-so-great quarterly results/forward-looking guidance.
Growth vs. Value. The growth to value ratio that I like to follow (IWF:IWD) has rebounded over the past few days and it's starting the week out fairly strong today. More work needs to be done, though, and this is another reason why the 4 Mag 7 reports will be so important.
Happy trading!
Tom