
EB Weekly Market Report - Monday, March 2, 2026
ChartLists/Spreadsheets
The following ChartLists/Spreadsheets were updated over the weekend:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL)
- Key Manipulation Spreadsheet
- Upcoming Earnings
- Upcoming Earnings Relative Strength
The above ChartLists and spreadsheet have been updated through Friday, February 27th. You can view and/or download these ChartLists from our website, and also read about them to gain a better understanding of how they can help in your trading success.
Weekly Market Recap
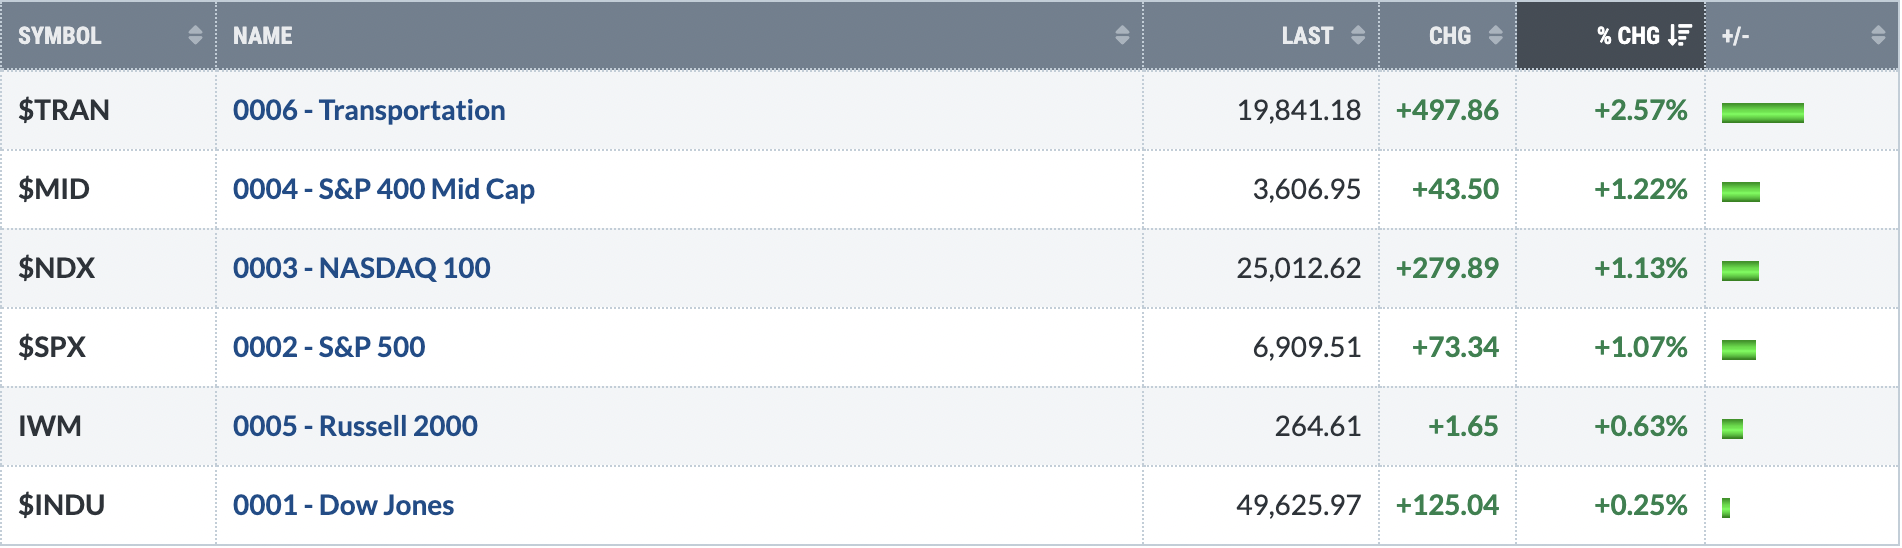
Major Indices
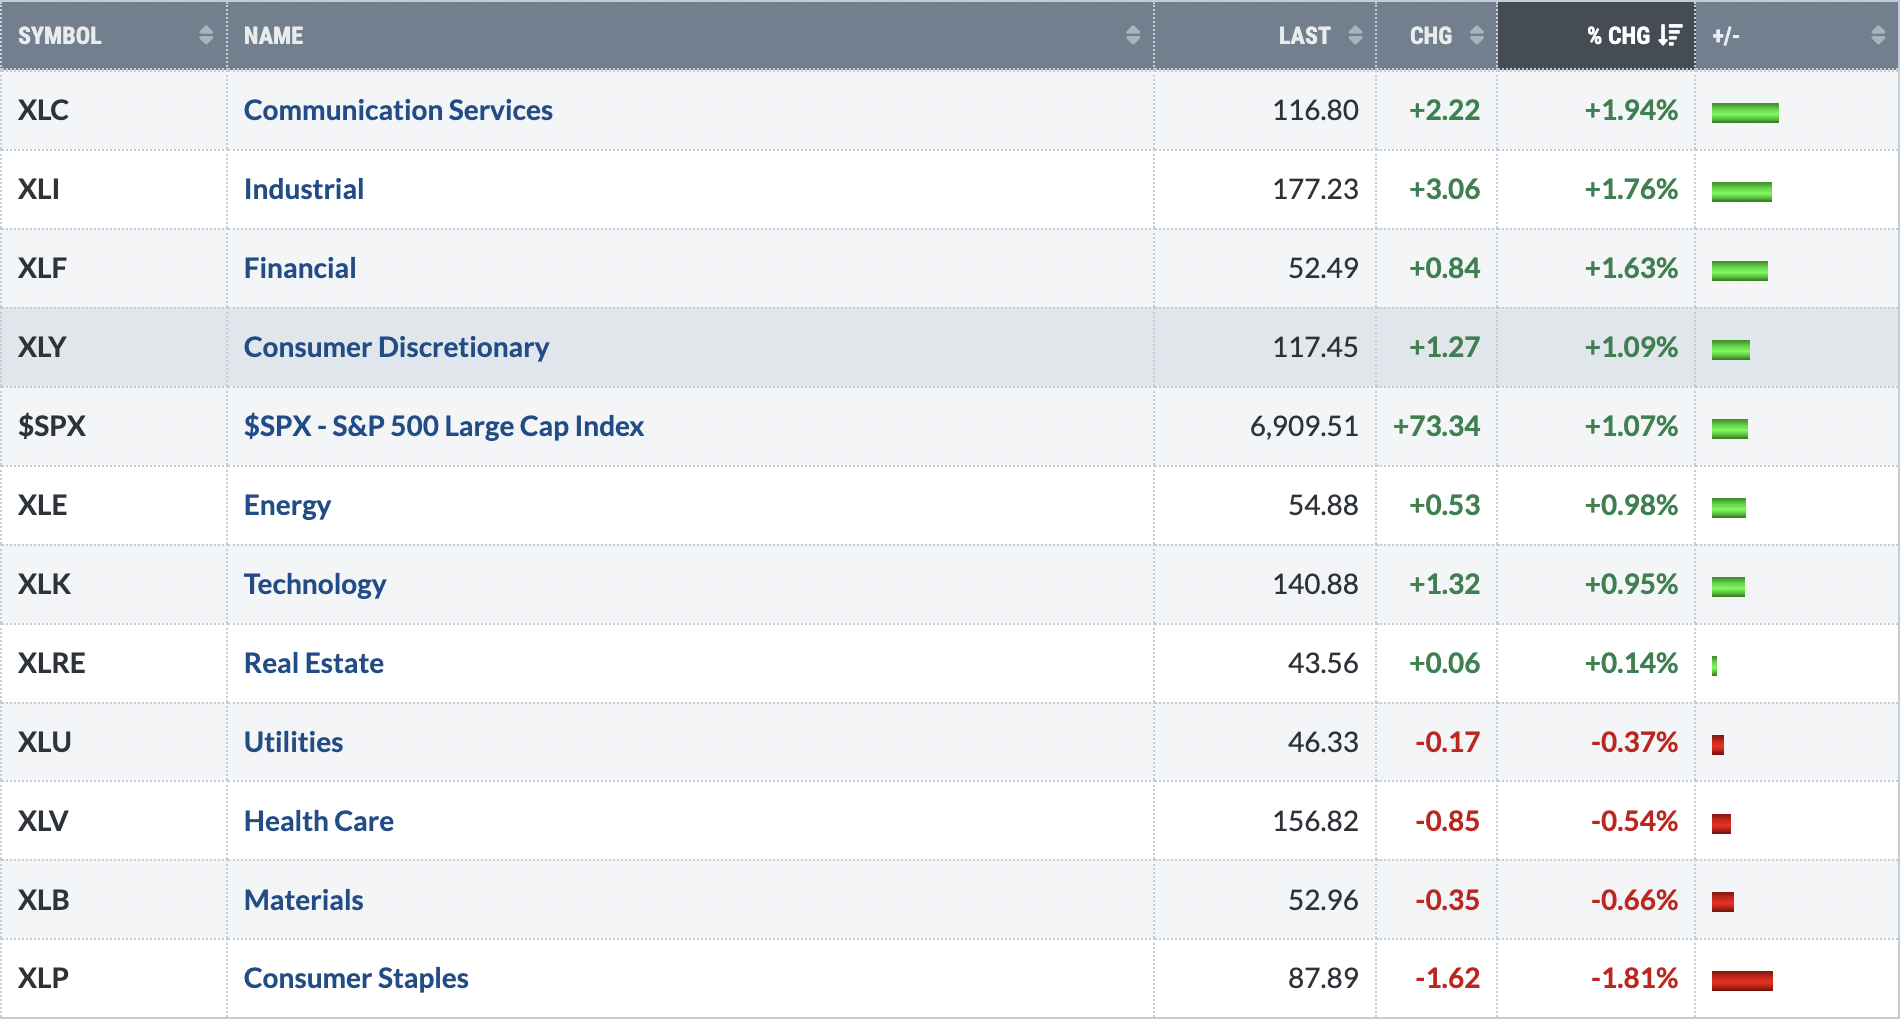
Sectors
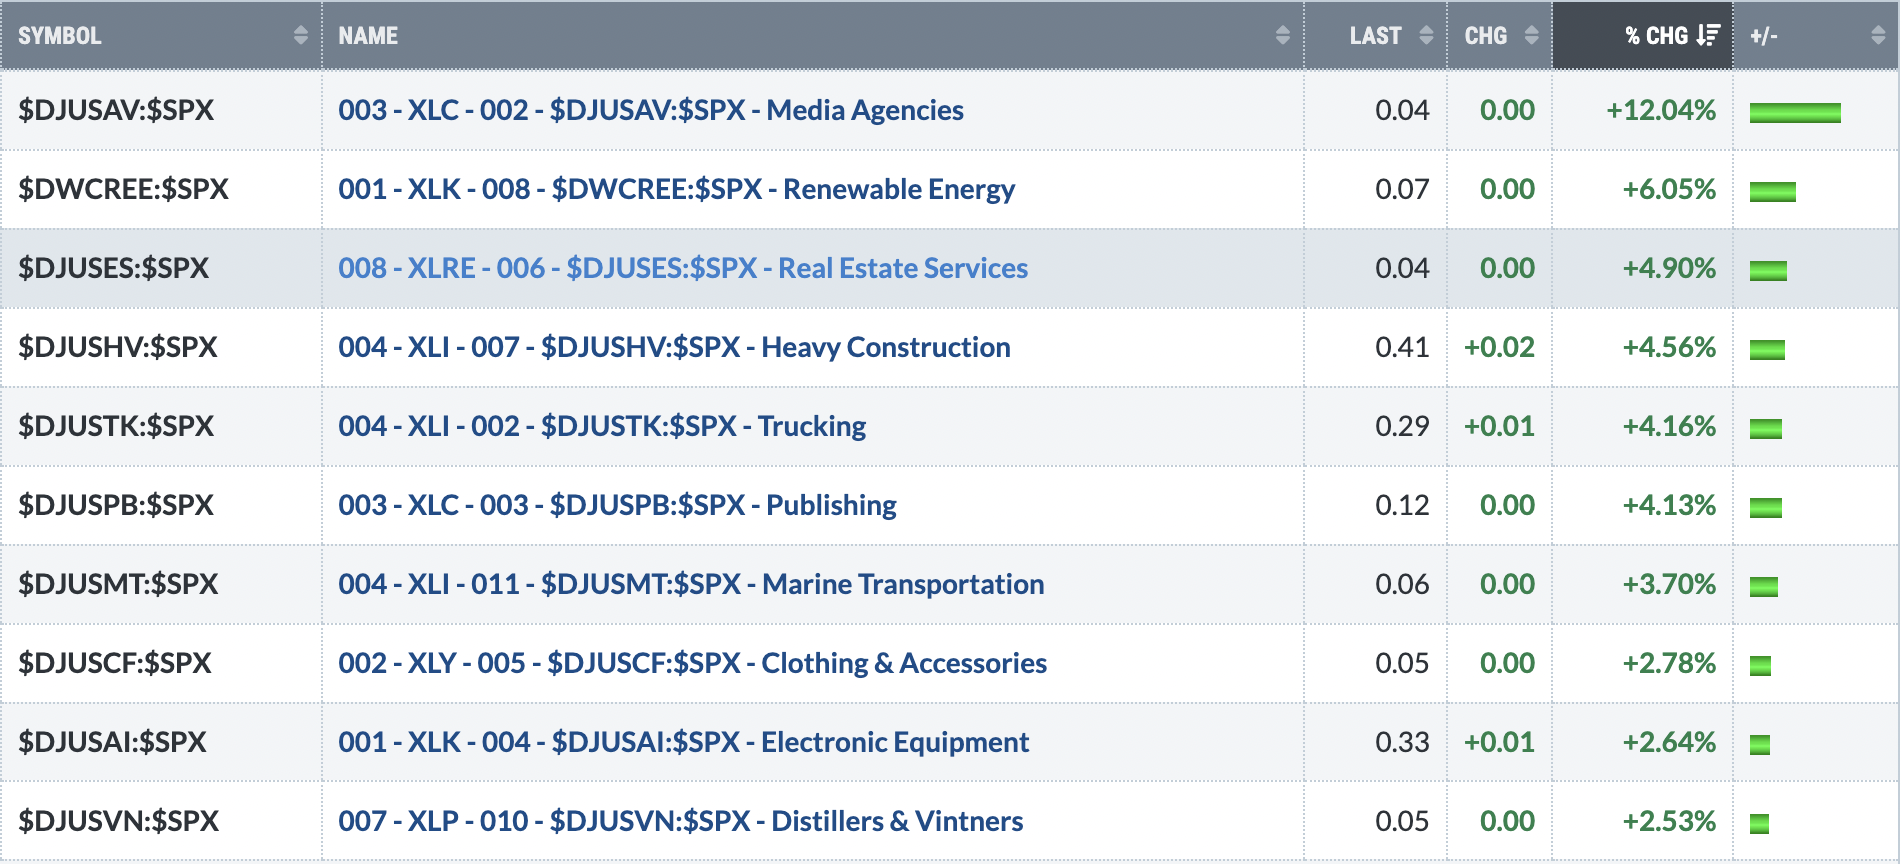
Top 10 Industries Last Week
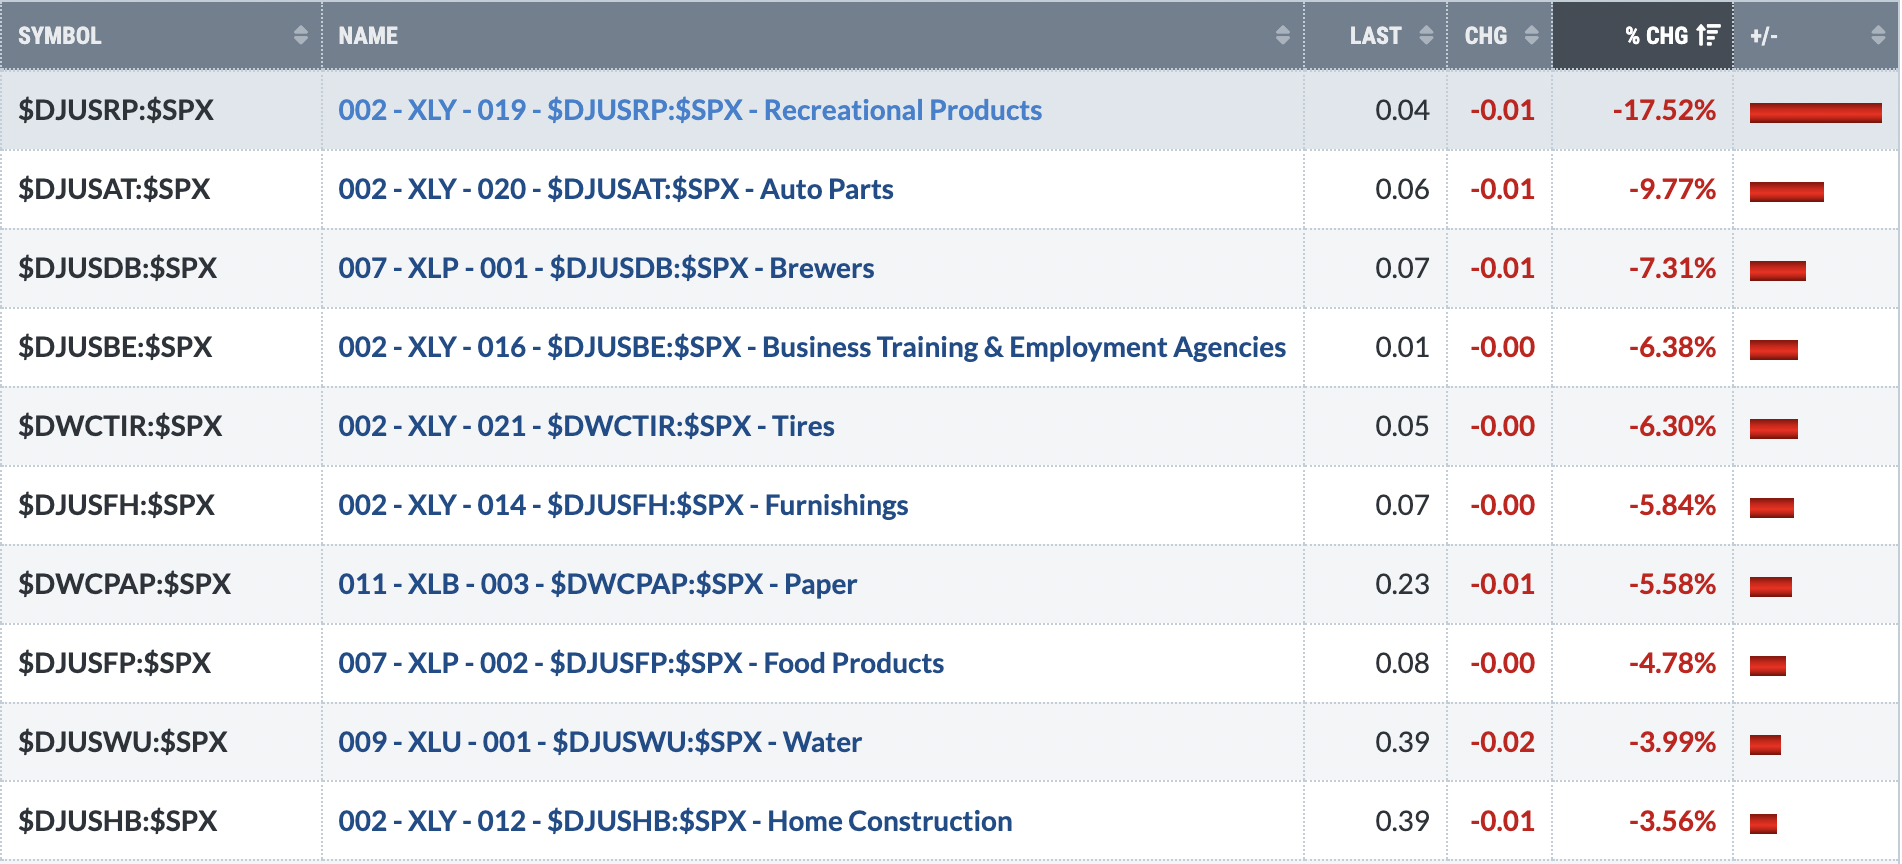
Bottom 10 Industries Last Week
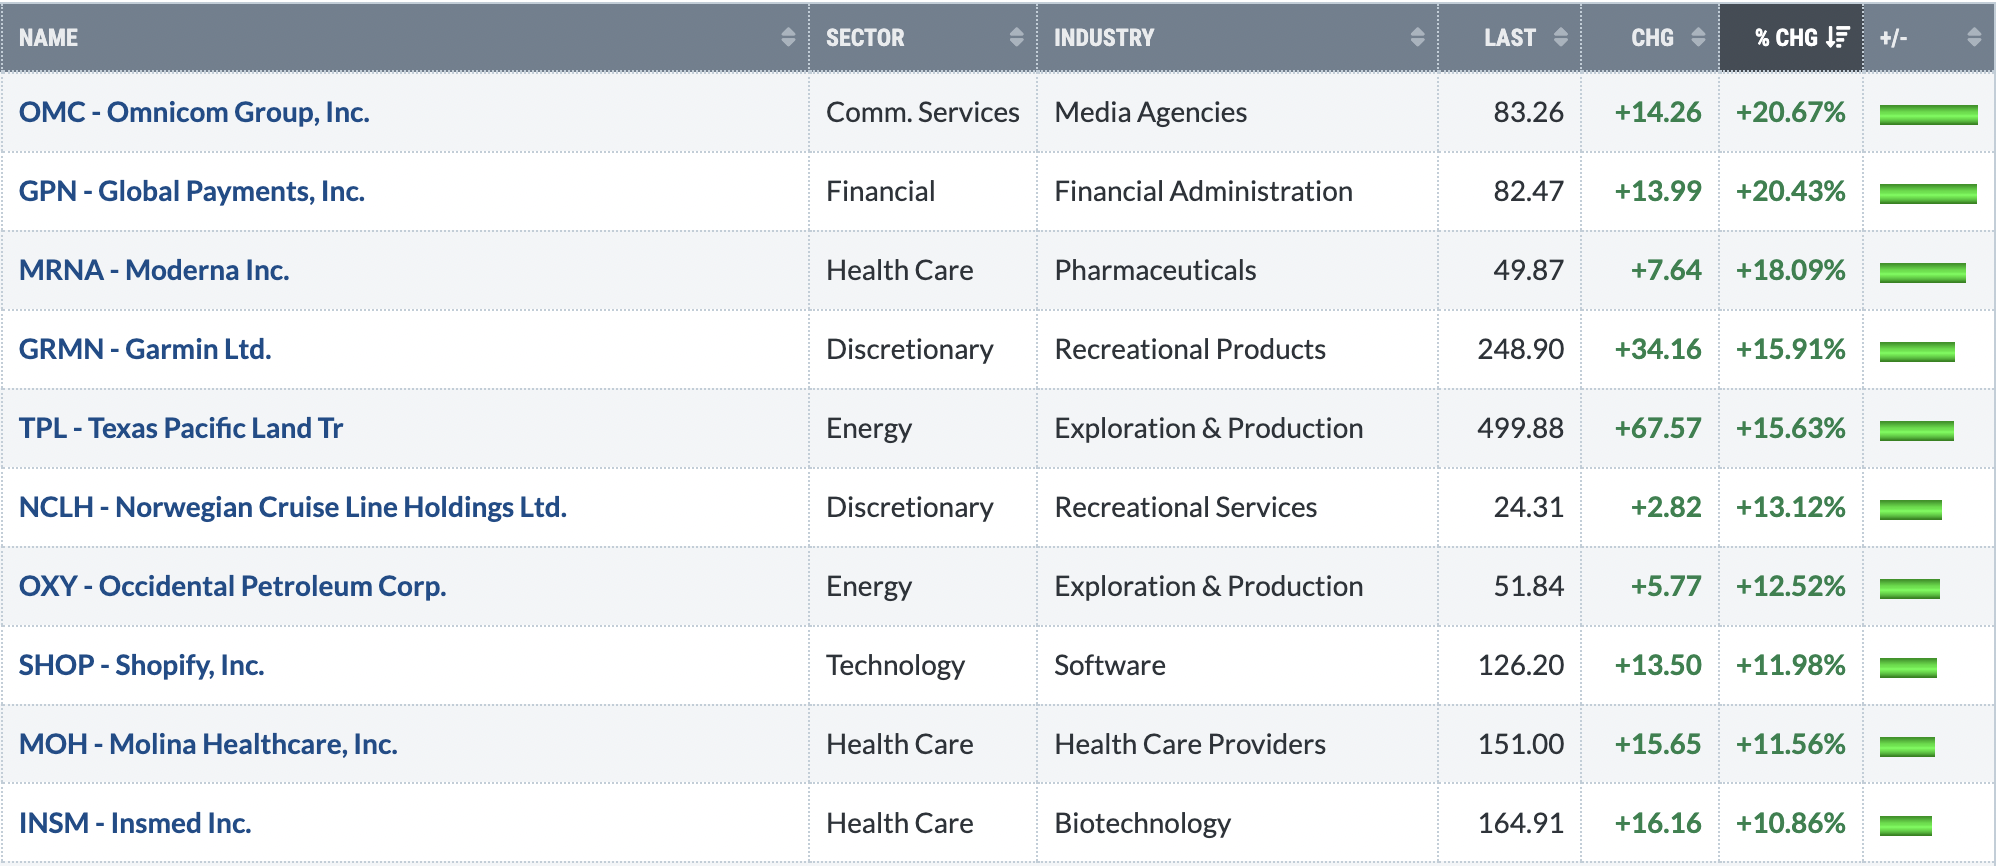
Top 10 Stocks - S&P 500/NASDAQ 100
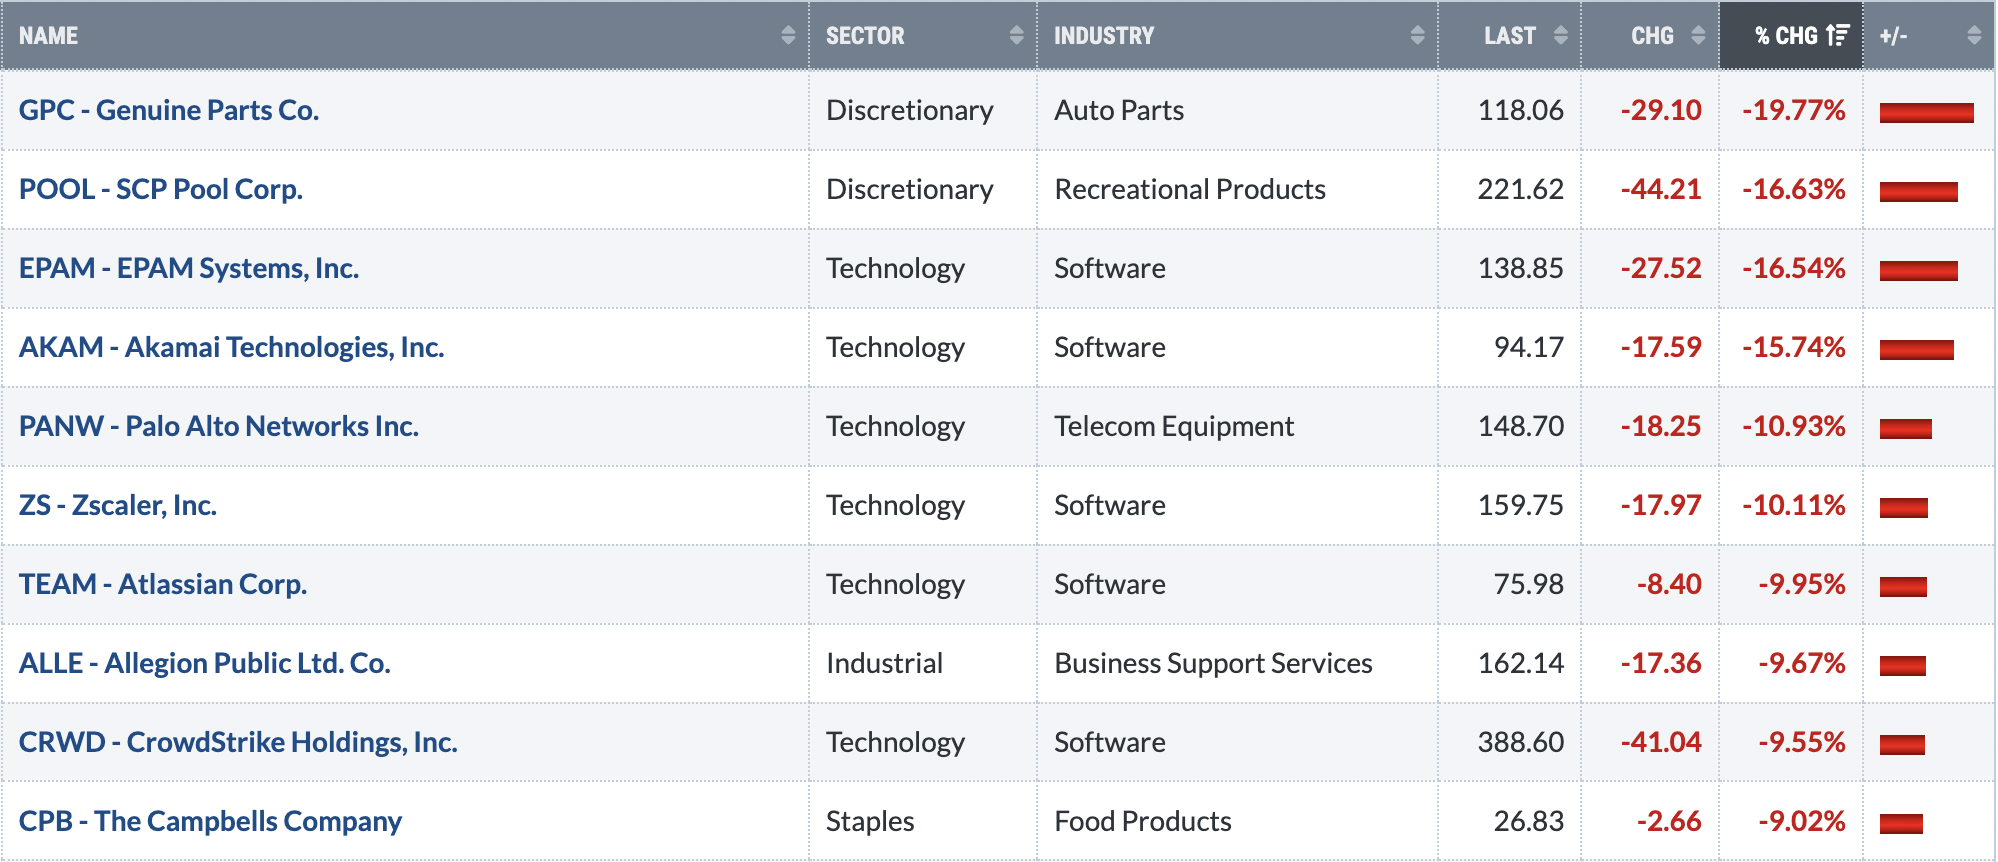
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
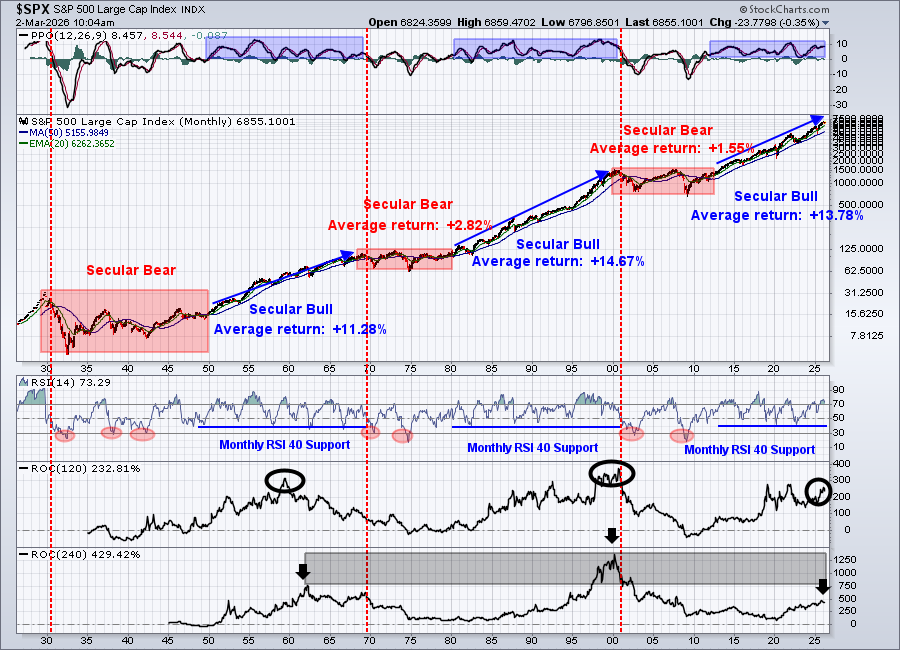
This might seem like a pointless chart to post week after week, but I think it's a great reminder of the secular bull market that we REMAIN in. It's a reminder that, while short-term issues are dominating the market environment, the long-term chart remains perfectly intact and long-term investors should simply resist the temptation to listen to the noise.
Stay long and strong!
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
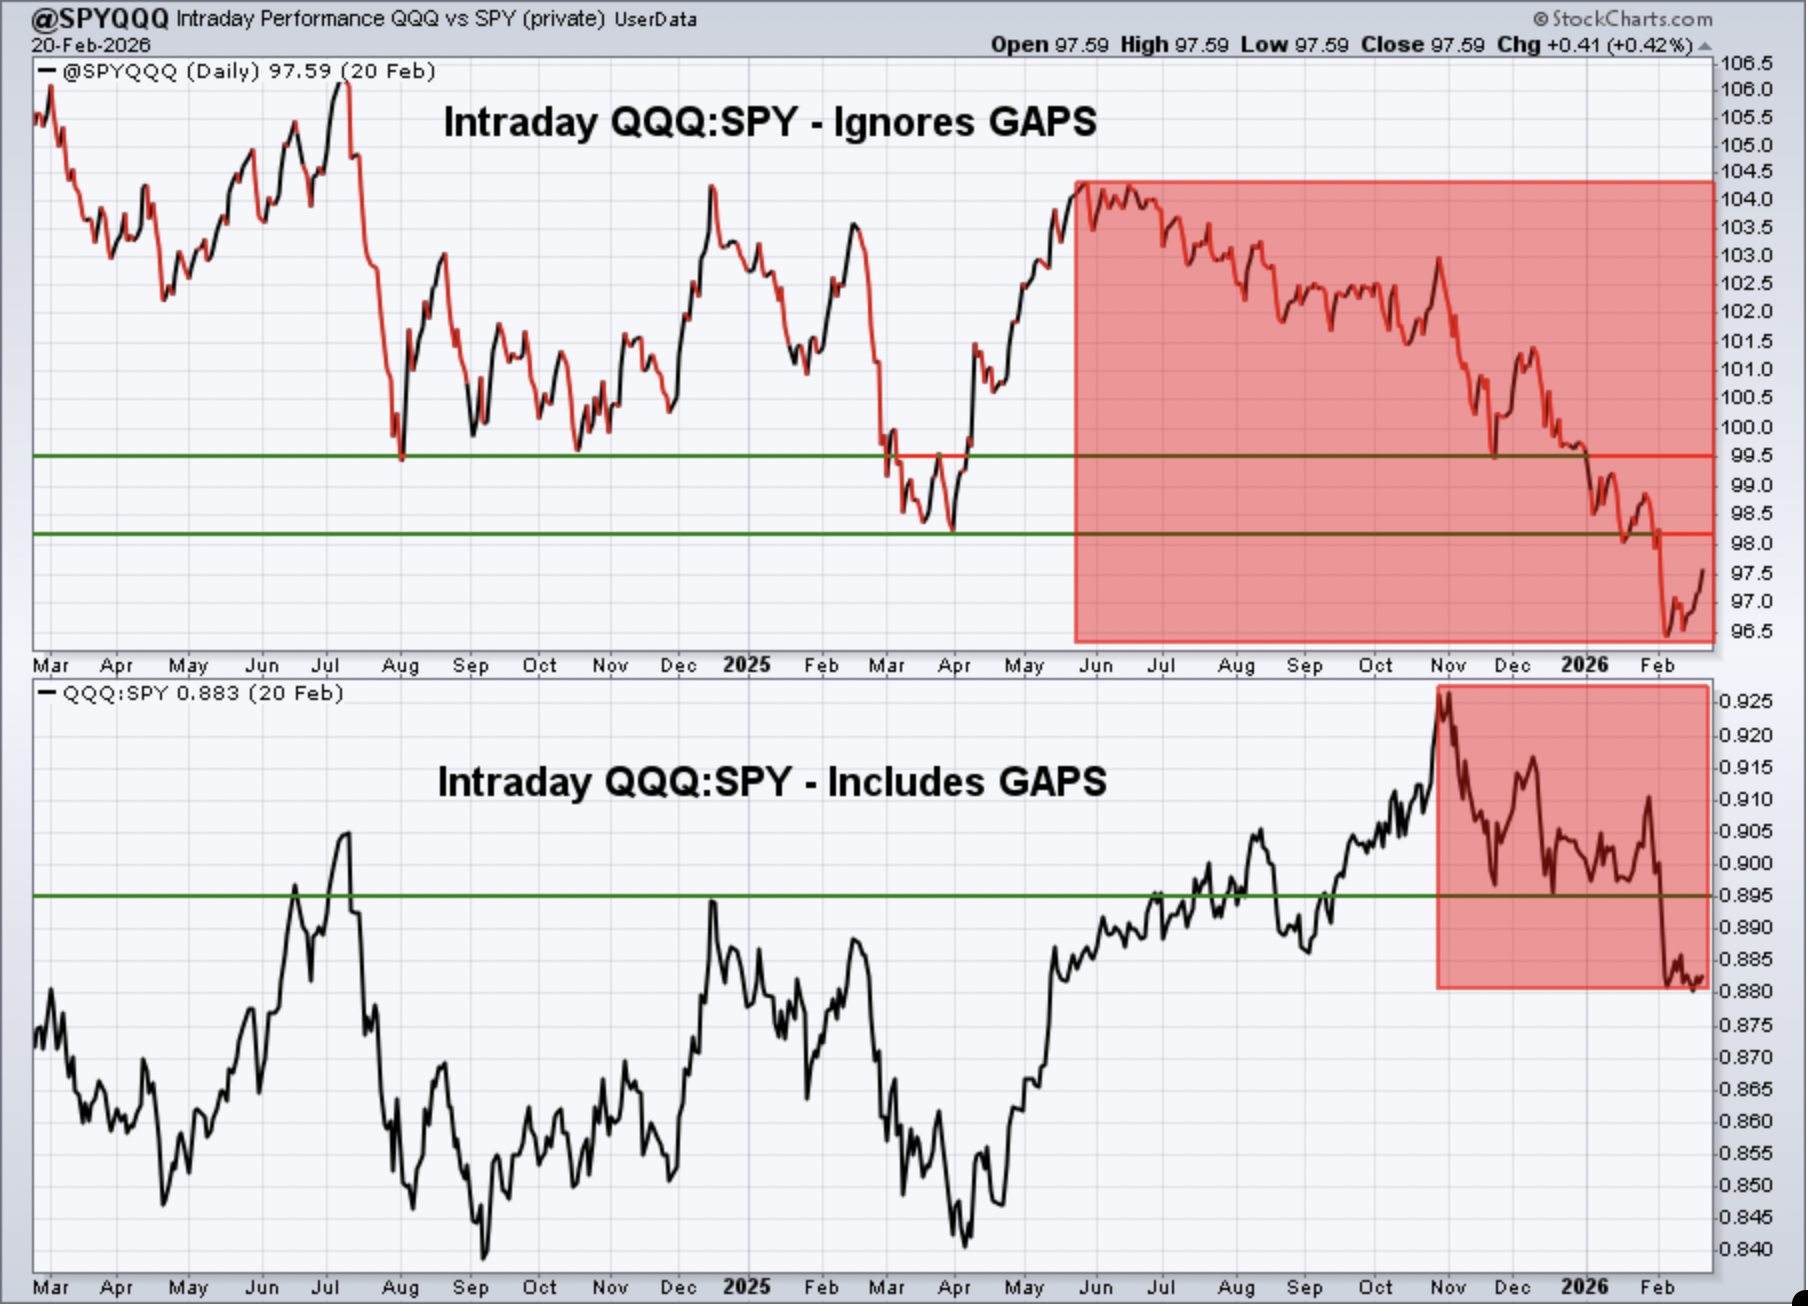
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
The overall downtrend remains in play and underscores one of the biggest underlying issues in the stock market right now......growth stocks continue to underperform their value counterparts on a relative basis.
IWM:QQQ
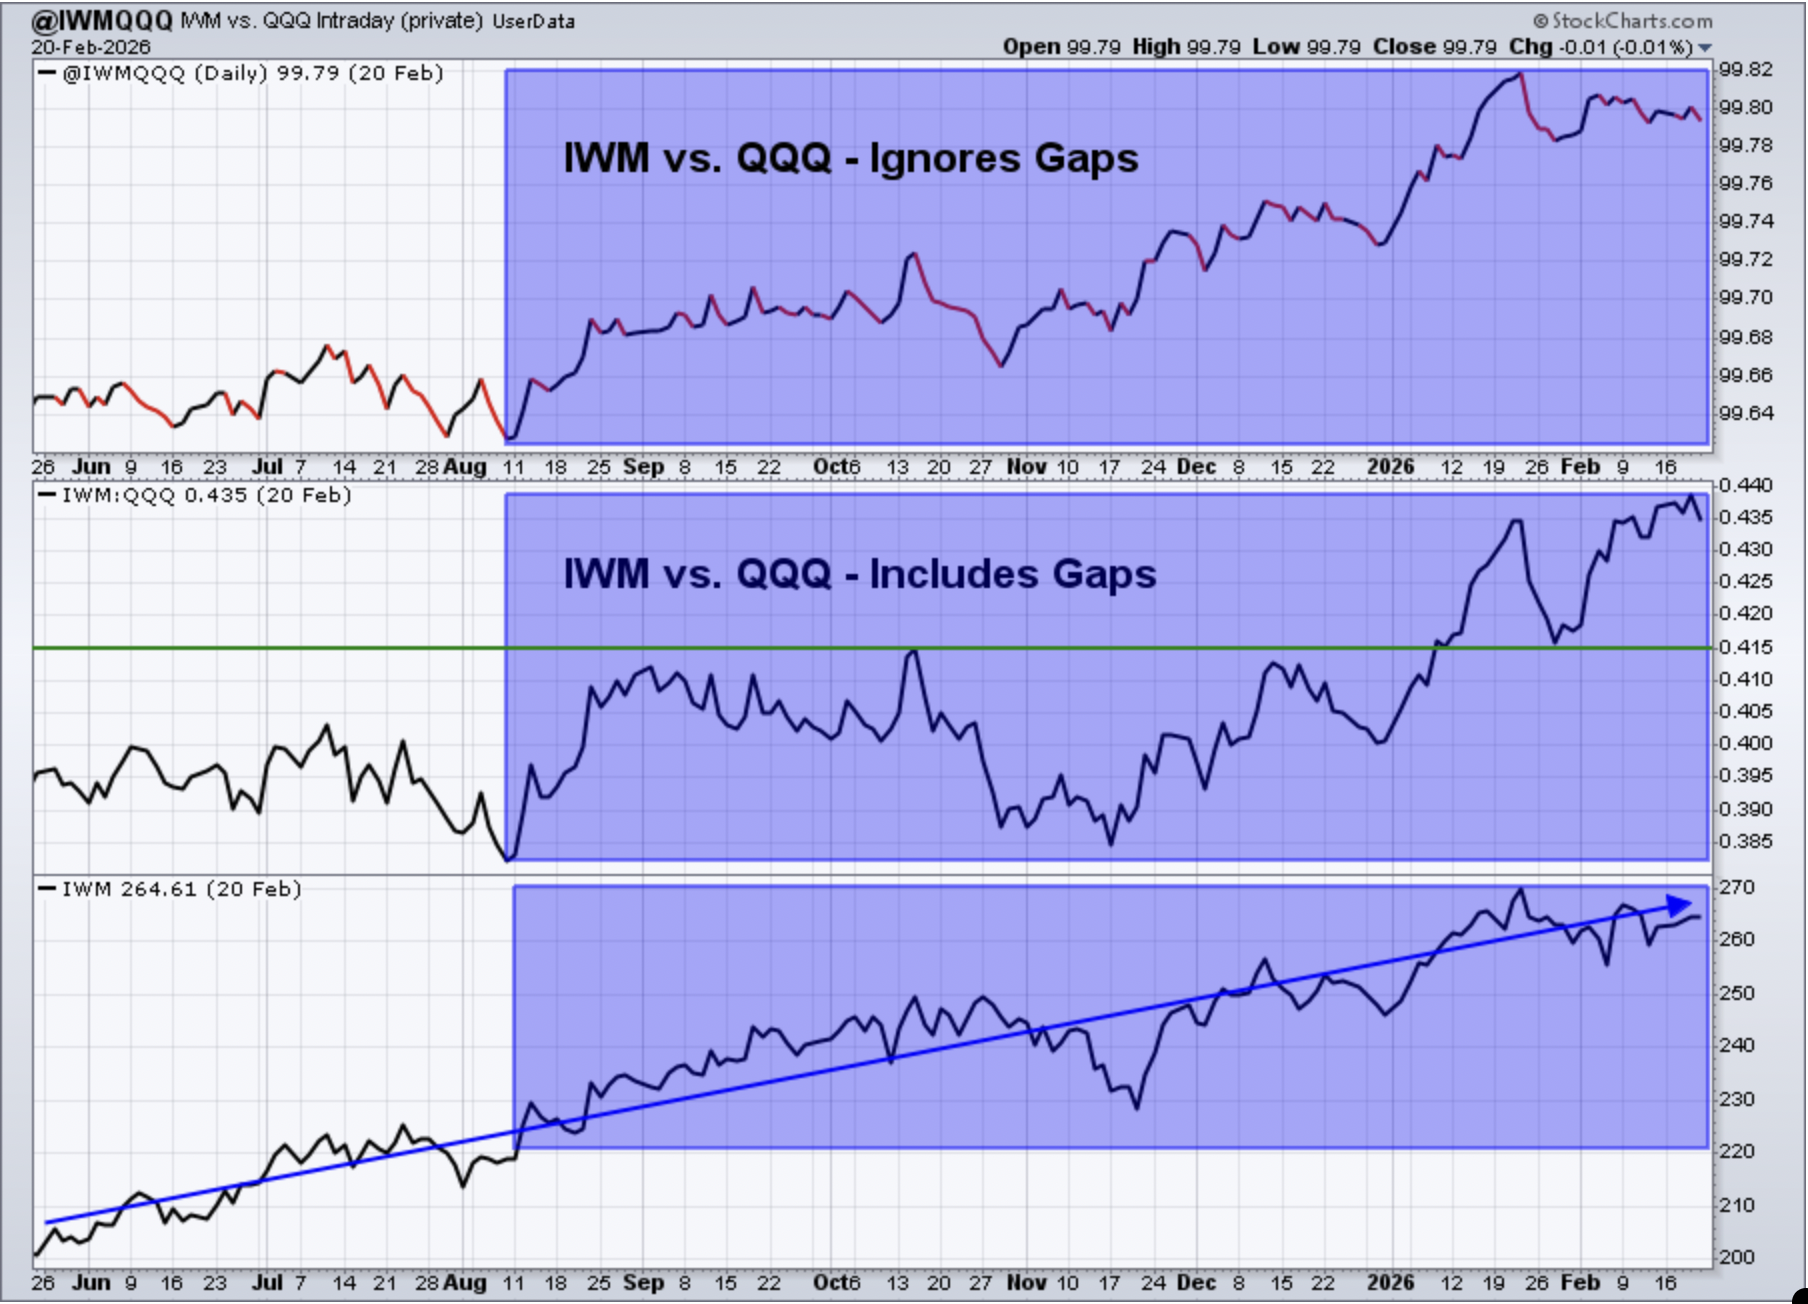
The trend in the small cap IWM cannot really be argued currently. Small caps and mid caps are definitely leading their larger cap counterparts and this very well could continue in 2026. The most critical differentiator is the "Mag 7" performance. When money rotates away from this very influential group, areas like small and mid caps benefit.
XLY:XLP
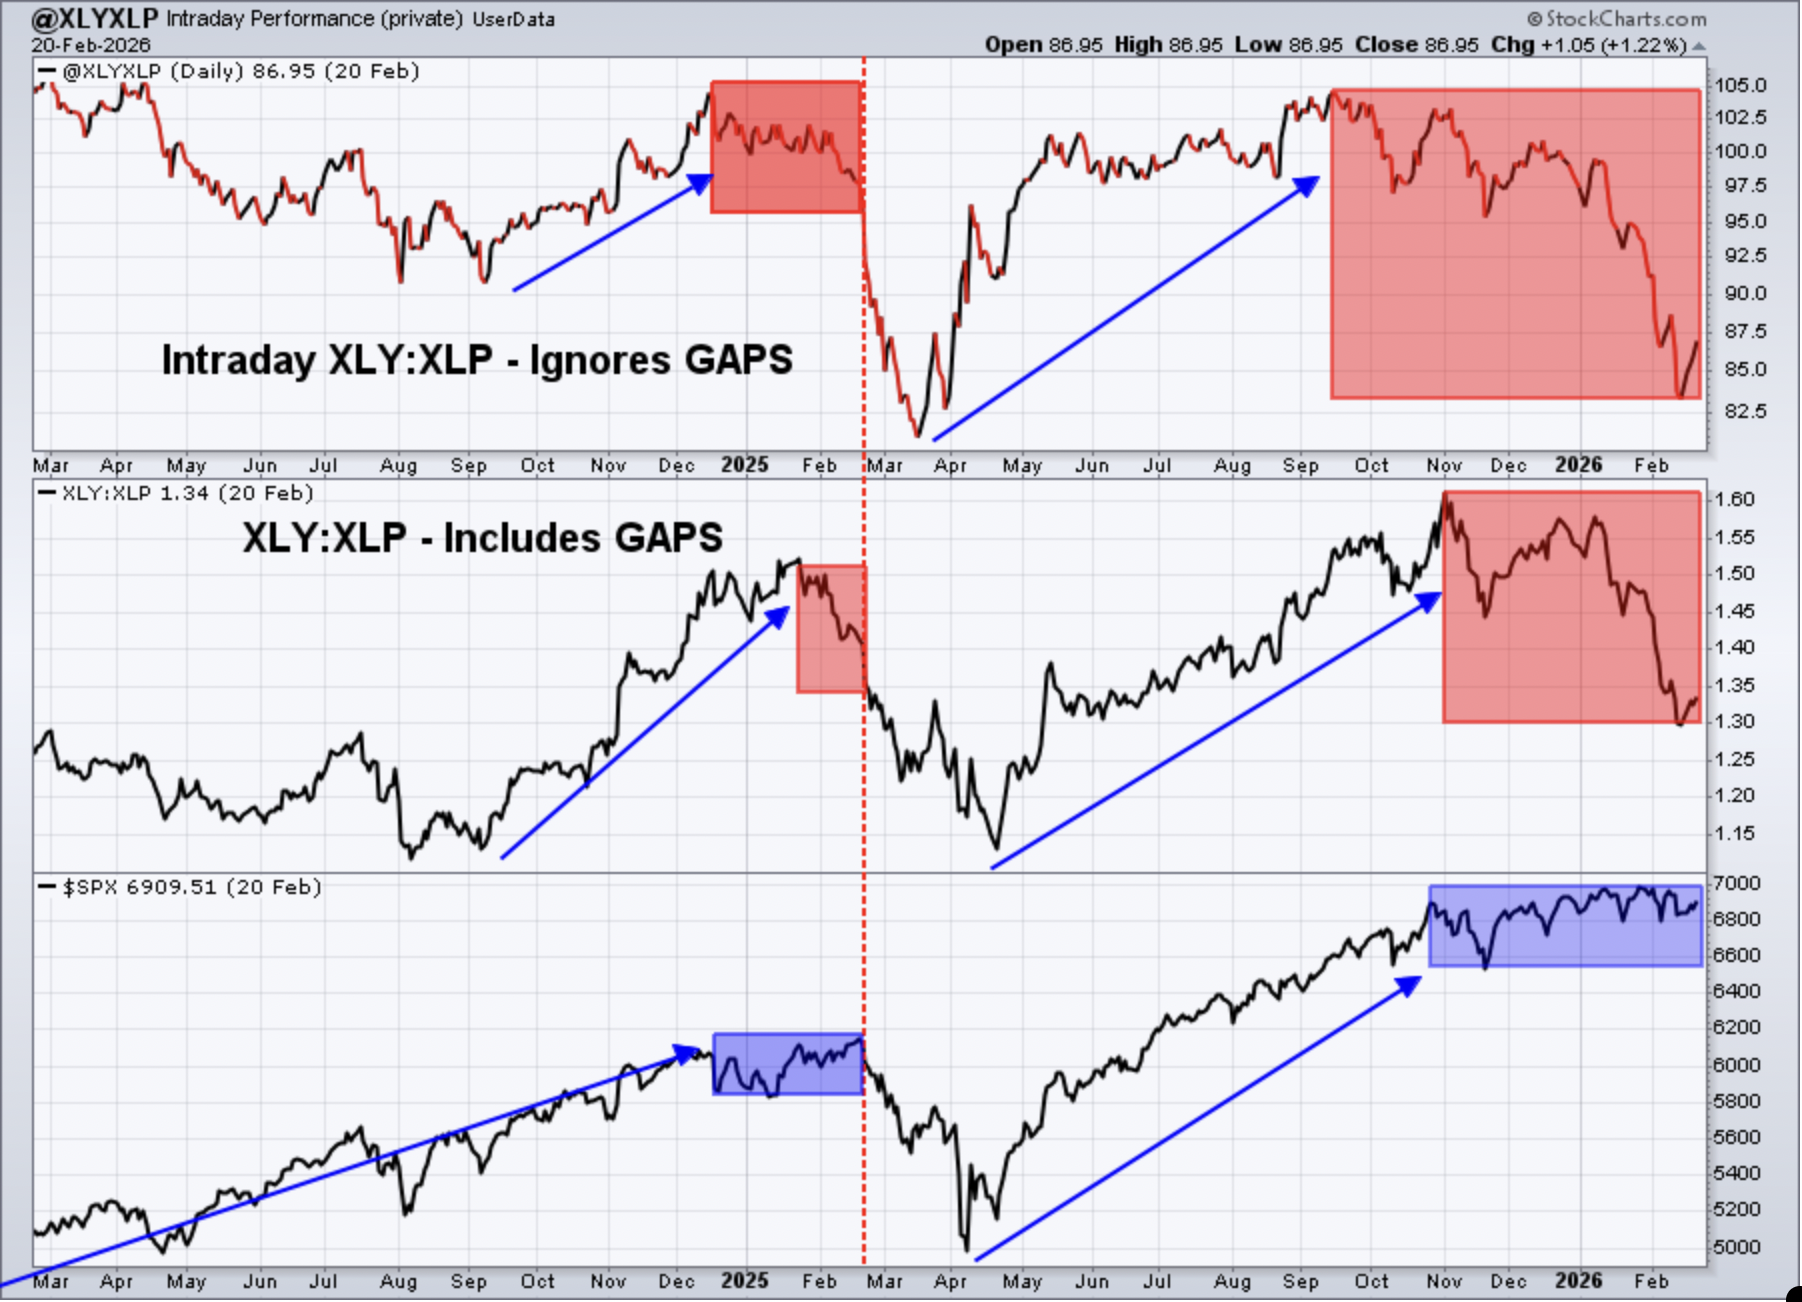
2026 has been an eye opener for consumer stocks. U.S. GDP is comprised of two-thirds consumer spending. Watching to see which group of consumer stocks outperforms is critical in determining Wall Street's mindset and the likely future direction of the benchmark S&P 500. The current downtrend screams to us to remain cautious short-term. When this ratio begins moving higher in earnest, the S&P 500 will very likely find its new all-time high.
Sentiment
5-day SMA ($CPCE)
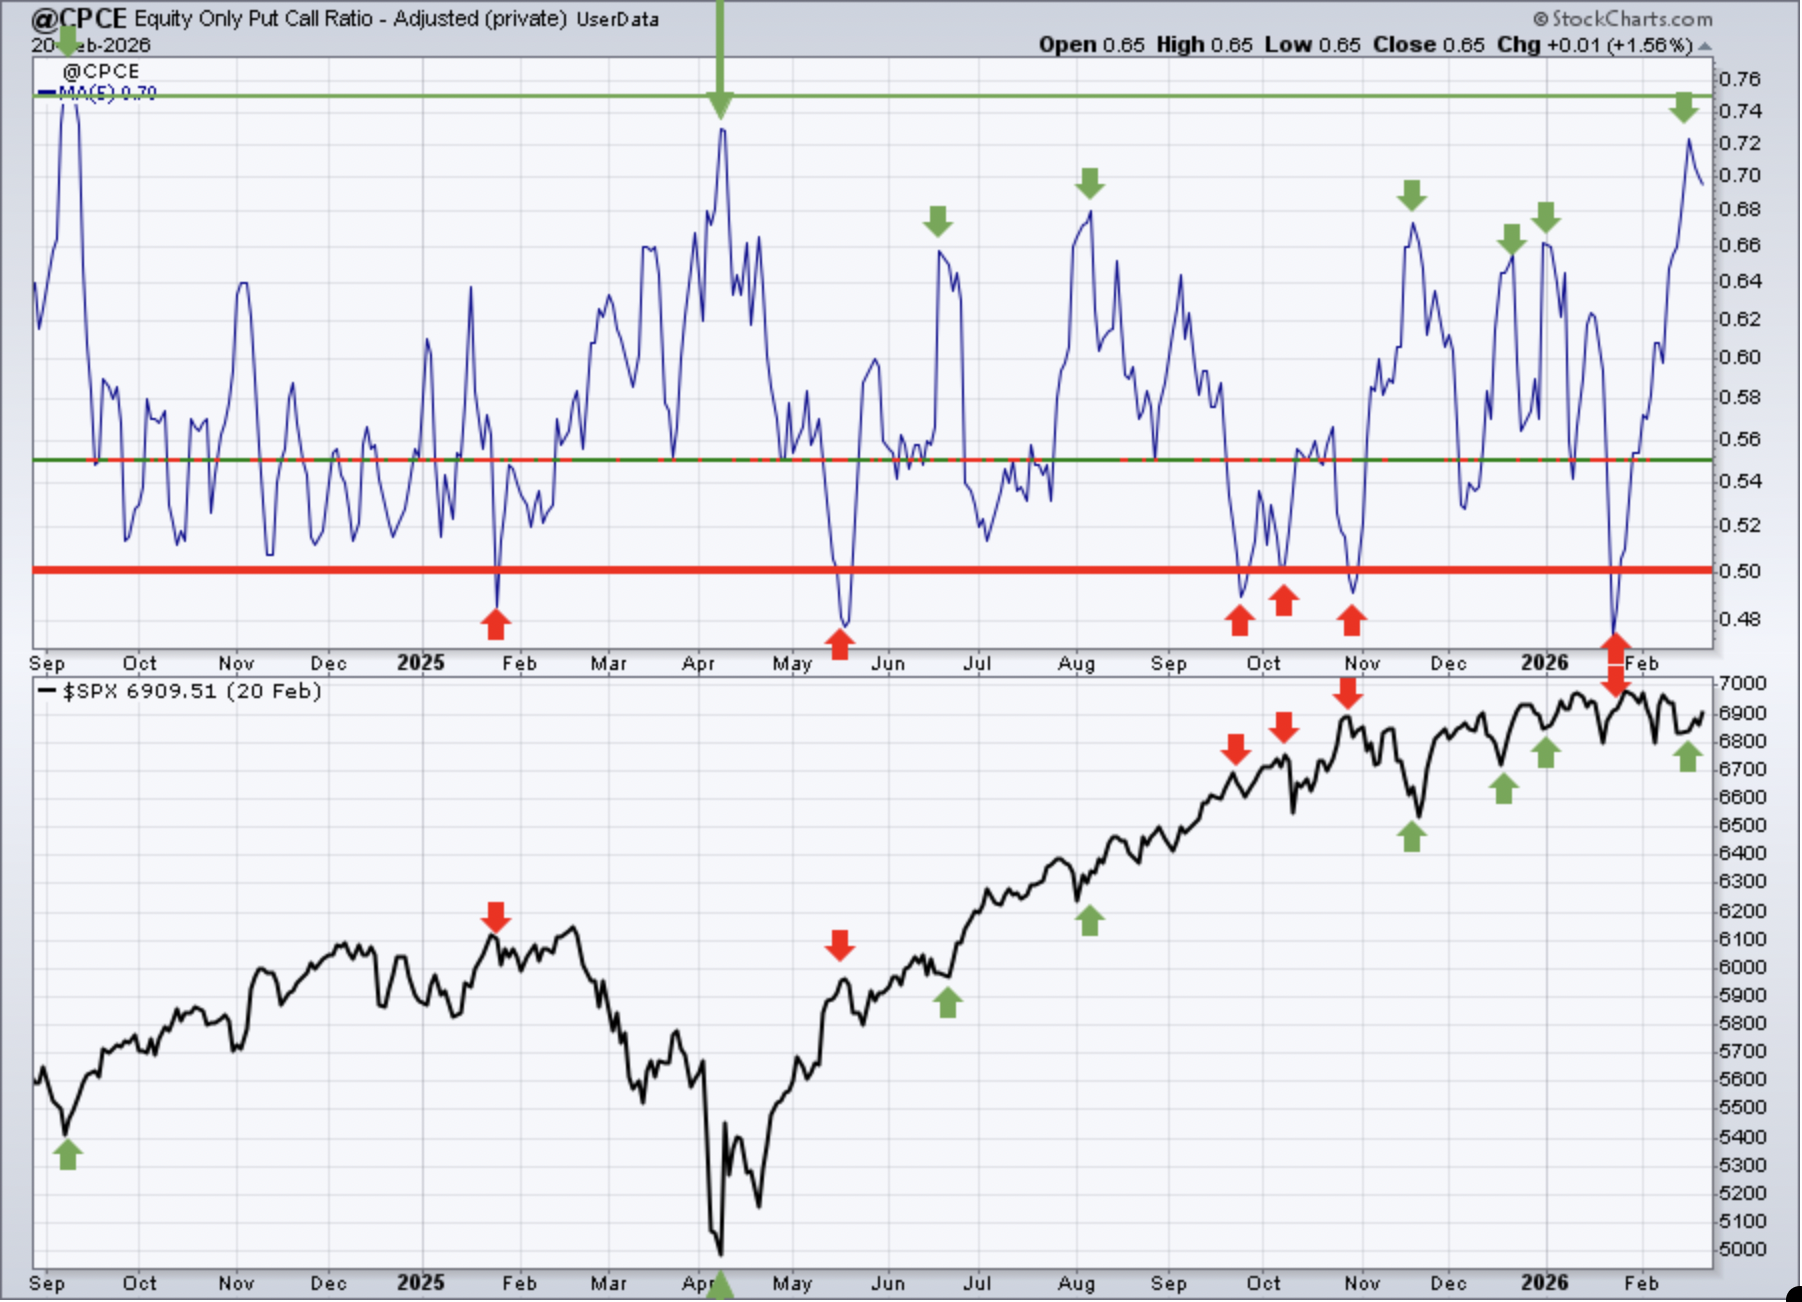
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Keep in mind that the above 5-day SMA reading of the CPCE is our "speed boat" sentiment indicator that changes quite frequently. While the .75+ level has been where many short-term bottoms have occurred in the past, the .65 or so level has been marking short-term bottoms in 2025 and 2026. The 5-day CPCE is now moving back and forth, much like our major key indices. I'd expect to see a jump to .75 or higher on this 5-day SMA if the S&P 500 eventually loses support at 6797.
253-day SMA ($CPCE)
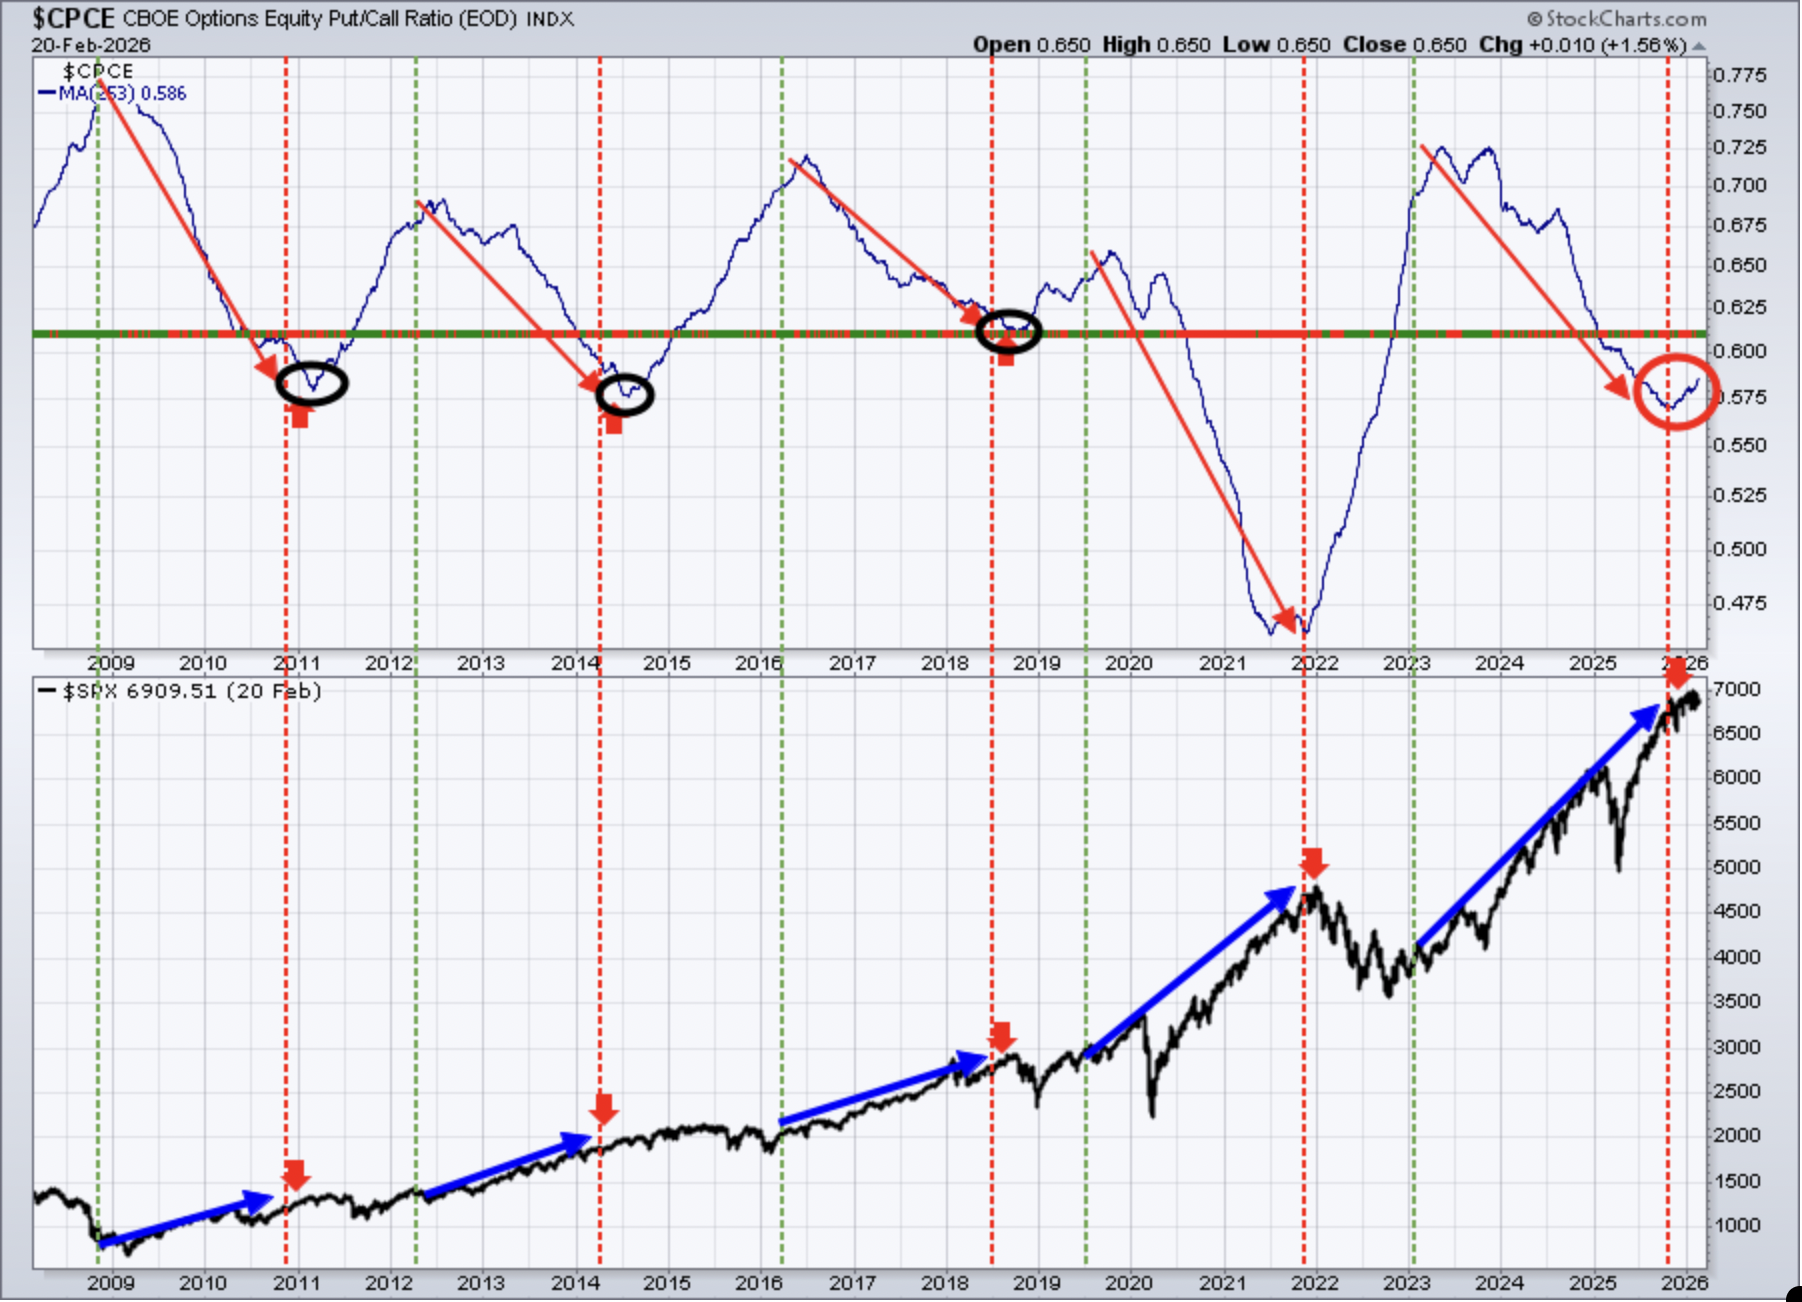
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500. It seems that long-term sentiment is now "resetting". Any time we see a bottom in this 253-day SMA and a turn to the upside, it's a challenge for U.S. equities. Please note that these turns to the upside have previously occurred in the middle of our secular bull market. So while the recent turn higher does suggest a challenge ahead, it does NOT signal the start of a significant bear market.
Long-Term Trade Setup
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month. Below is a quick recap of how these stocks looked on MONTHLY charts as of Monday, March 2nd:
- JPM – look for more sideways action ahead as the monthly PPO rolls over
- BA – could be on the verge of a major move; needs to clear 250-275
- FFIV – long-term trend is higher, now back above its rising 20-month EMA
- MA – 525 price support holding, solid entry point with weekly RSI at 44
- GS – likely needs a rest after a massive 2-year run; 20-month EMA near 700
- FDX – this one looks great, just breaking above double top at 300
- AAPL – steady climber, consolidating 2025 rise; 20-month EMA is support
- CHRW – overbought after massive 9-10 month run higher
- JBHT – a leader in the red-hot transportation area; monthly PPO strengthens
- STX - monthly RSI at 92+, so clearly overbought; what a massive rise
- HSY - waited patiently for a breakout above 200, now rolling
- DIS - 125 is the number; clear that and DIS could be off to the races
- MSCI - lots of consolidation, needs to break above 650
- SBUX - working on its 5th year of consolidation, needs a breakout
- KRE – ran to all-time high before pulling back recently
- ED – breaking out as it heads into the seasonally-favorable month of March
- AJG - steady performer for 15 years; might have found support with bounce
- NSC – like JBHT, rallying and breaking out on heels of transports strength
- RHI – January rally gave way to big February selling; expect a dividend cut
- ADM – rallying back over past year with monthly PPO now above zero line
- BG – breakout after 4 years of consolidation a very bullish signal
- CVS – holding 70 support remains key, continues to improve
- HRL - short-term rally is nice, but key will be clearing 27.50
- DE – latest earnings report sent stock to new all-time high; excellent chart
- LULU - needs a catalyst to end its 2+ year slide; looking for 150 to hold
- TTD - free falling within one of worst industries - software; 15-20 is support
- META - remains in range from 600-800; may consolidate further
- ADBE - broke down below 2022 low, reports earnings in two weeks
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: ASTS ($31 billion), MDB ($27 billion)
- Tuesday: CRWD ($96 billion), ROST ($66 billion), AZO ($61 billion), TGT ($52 billion)
- Wednesday: AVGO ($1.53 trillion), VEEV ($30 billion)
- Thursday: COST ($438 billion), MRVL ($69 billion), CIEN ($48 billion), KR ($43 billion)
- Friday: None
Key Economic Reports
- Monday: February ISM manufacturing
- Tuesday: None
- Wednesday: February ADP employment report, February ISM services, Fed beige book
- Thursday: Initial jobless claims, Q4 productivity
- Friday: February nonfarm payrolls, unemployment rate, & hourly wages
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Mar 2: +39.20% (Ex: cumulative gains =+8.37% over 54 trading days since 1950. +8.37% x 253/54 = +39.20%)
- Mar 3: +2.84%
- Mar 4: +44.05%
- Mar 5: +24.11%
- Mar 6: -24.31%
- Mar 7: -55.83%
- Mar 8: +0.60%
- Mar 9: -18.01%
- Mar 10: +28.20%
- Mar 11: +32.36%
- Mar 12: -29.45%
- Mar 13: +37.40%
- Mar 14: -12.13%
- Mar 15: +65.38%
NASDAQ (since 1971)
- Mar 2: +8.14%
- Mar 3: -24.15%
- Mar 4: +72.12%
- Mar 5: -3.59%
- Mar 6: -38.81%
- Mar 7: -47.82%
- Mar 8: +7.66%
- Mar 9: -39.99%
- Mar 10: +15.08%
- Mar 11: +26.89%
- Mar 12: -72.06%
- Mar 13: +100.86%
- Mar 14: -10.64%
- Mar 15: +3.76%
Russell 2000 (since 1987)
- Mar 2: -1.57%
- Mar 3: +3.91%
- Mar 4: +92.50%
- Mar 5: -39.76%
- Mar 6: -42.00%
- Mar 7: -23.95%
- Mar 8: +13.71%
- Mar 9: -76.04%
- Mar 10: +9.70%
- Mar 11: +10.81%
- Mar 12: -75.20%
- Mar 13: +89.11%
- Mar 14: -58.46%
- Mar 15: -22.48%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Well, when I discussed choppiness for 2026, or at least the first half of it, I didn't visualize the choppiness taking place over such a narrow range. It's somewhat shocking to see the Volatility Index ($VIX) closing near 20 last week, when the S&P 500 is simply consolidating after an uptrend. That's usually bull market material that keeps the VIX low in the 10-12 range, or slightly higher. But 20?
Here are a few things that I'll be watching in the week ahead and throughout March:
Rotation. The lack of participation in the Mag 7 stocks is really hurting our major indices - the opposite of what we saw in 2023 and 2024, when large cap growth investing was the only profitable game in town. NVDA was the last of the Mag 7 stocks to report earnings and they could not get a lift off, despite earnings well ahead of expectations. Keep watching this growth vs. value battle. So long as value wins, the task of the S&P 500 moving higher becomes more difficult.
Sentiment. As I just mentioned, the VIX is near 20 and the 253-day SMA of the CPCE is rising. Both of these can be quite problematic for U.S. stocks. I'd be VERY careful if the S&P 500 loses 6797 support and the VIX closes above 23. That combination could lead to more impulsive selling that could take the S&P 500 down into the 6500s. Obviously, the bulls will be looking to do the opposite - bring the VIX down and have the CPCE stabilize.
Technology (XLK) and Financials (XLF). The two largest sector representation in the S&P 500 is the XLK followed by the XLF. Both are teetering just above key price support. These two groups, especially the XLK, must hold onto price support or risk further deterioration in the benchmark S&P 500.
Seasonality. We're heading into the 3rd month within Q1. The 3rd month in quarters 1-3 tend to favor defensive-oriented sectors. In particular, utilities (XLU) have enjoyed excellent relative results in March, outpacing the S&P 500 in 12 of the last 13 years during March.
Nonfarm Payrolls Report. It's time for another jobs report. I'm honestly not sure what Wall Street wants most, a strong jobs report or a weak one. When that's the case, I tend to hope the report comes in close to the expected number. January came in at a more robust 130,000 jobs, but February only projects 54,000. Staying close to this number probably keeps the S&P 500 in its current trading range. A negative number could trigger recession fears, while a strong number could spur more inflation discussion.
Stay buckled up and happy trading!
Tom