
EB Weekly Market Report - Tuesday, May 26, 2026
ChartLists/Spreadsheets
The following ChartLists/Spreadsheets were updated either late yesterday or earlier this morning and have been updated on our website:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL)
- Upcoming Earnings
- Upcoming Earnings Relative Strength
The above ChartLists and spreadsheet have been updated through Friday, May 22nd. You can view and/or download these ChartLists from our website, and also read about them to gain a better understanding of how they can help in your trading success.
Weekly Market Recap
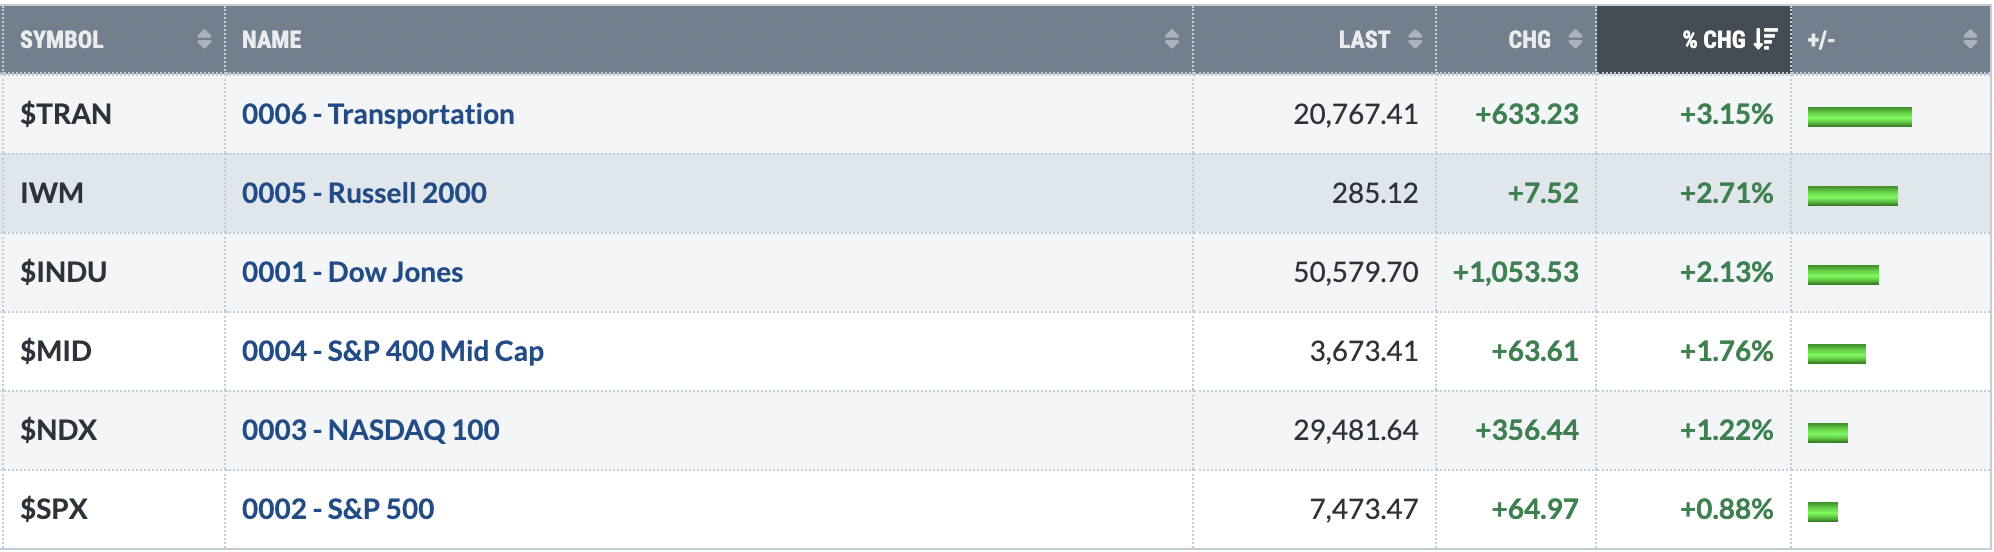
Major Indices
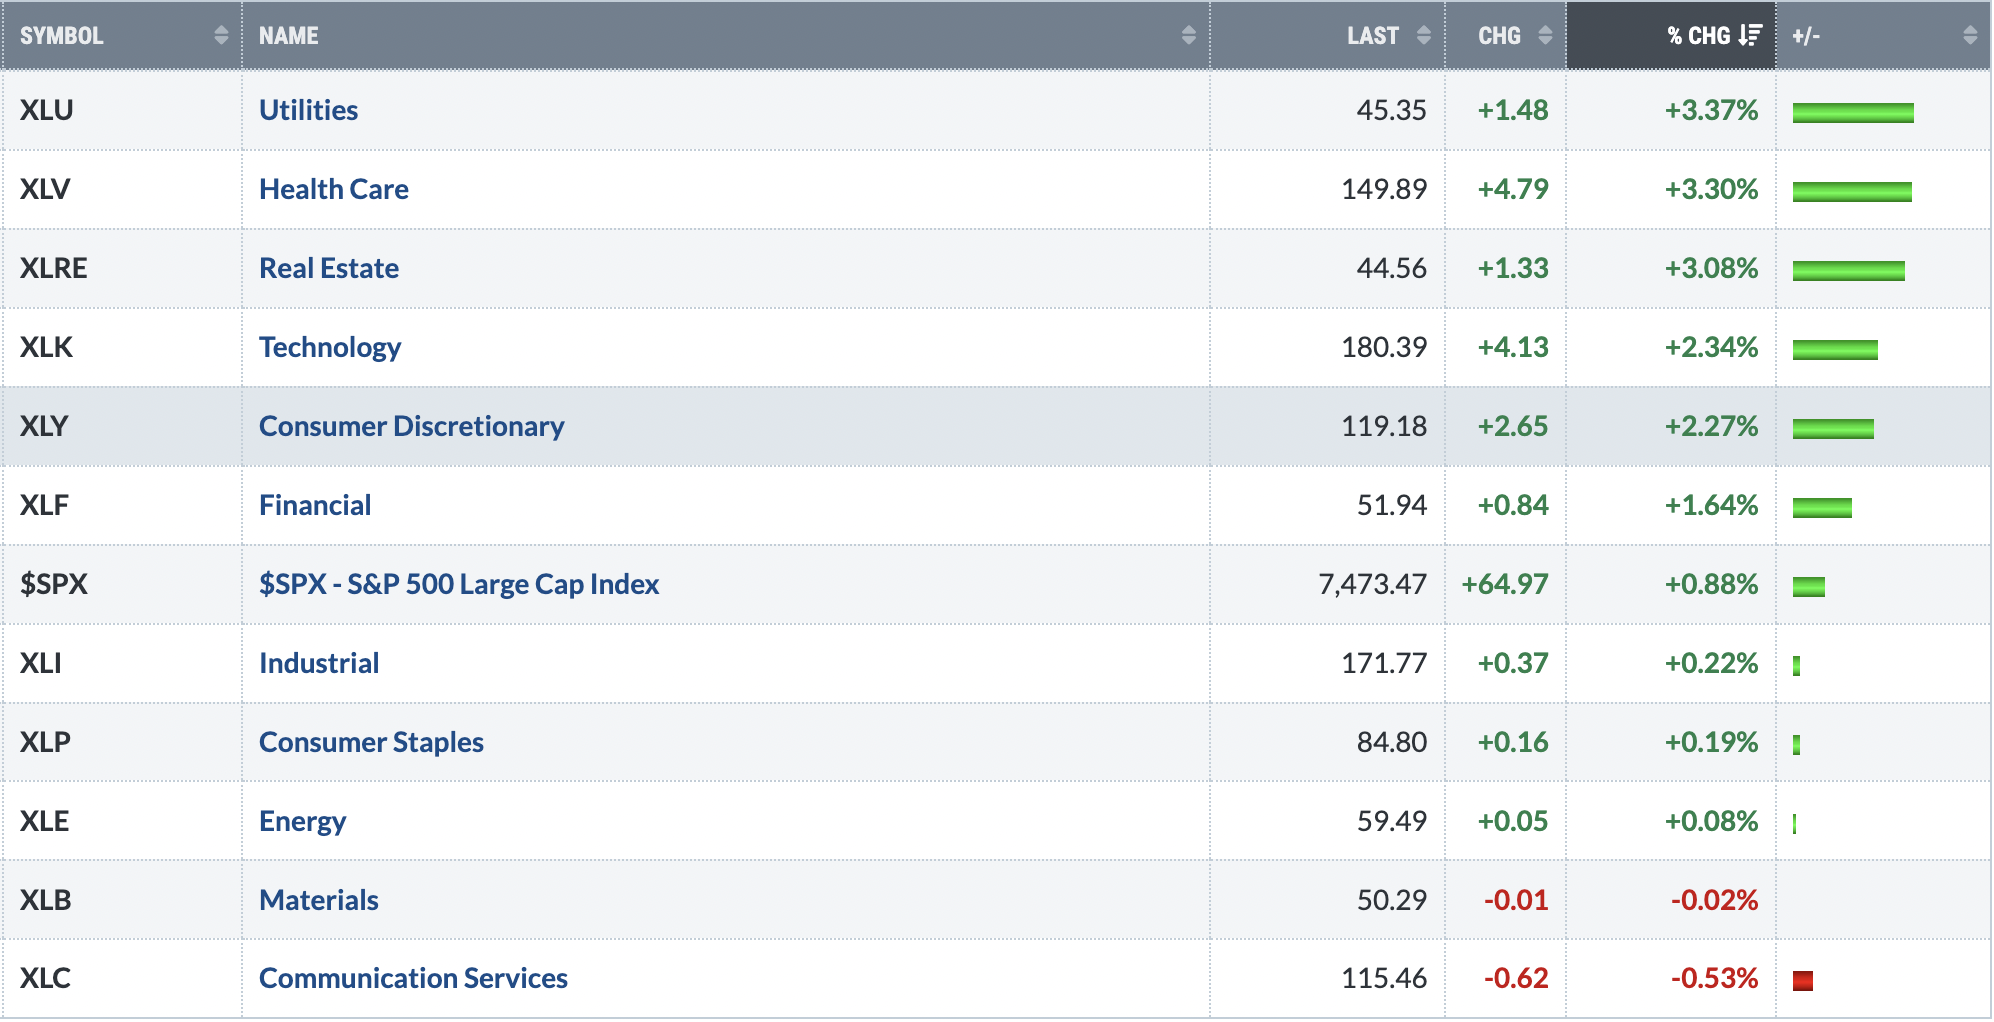
Sectors
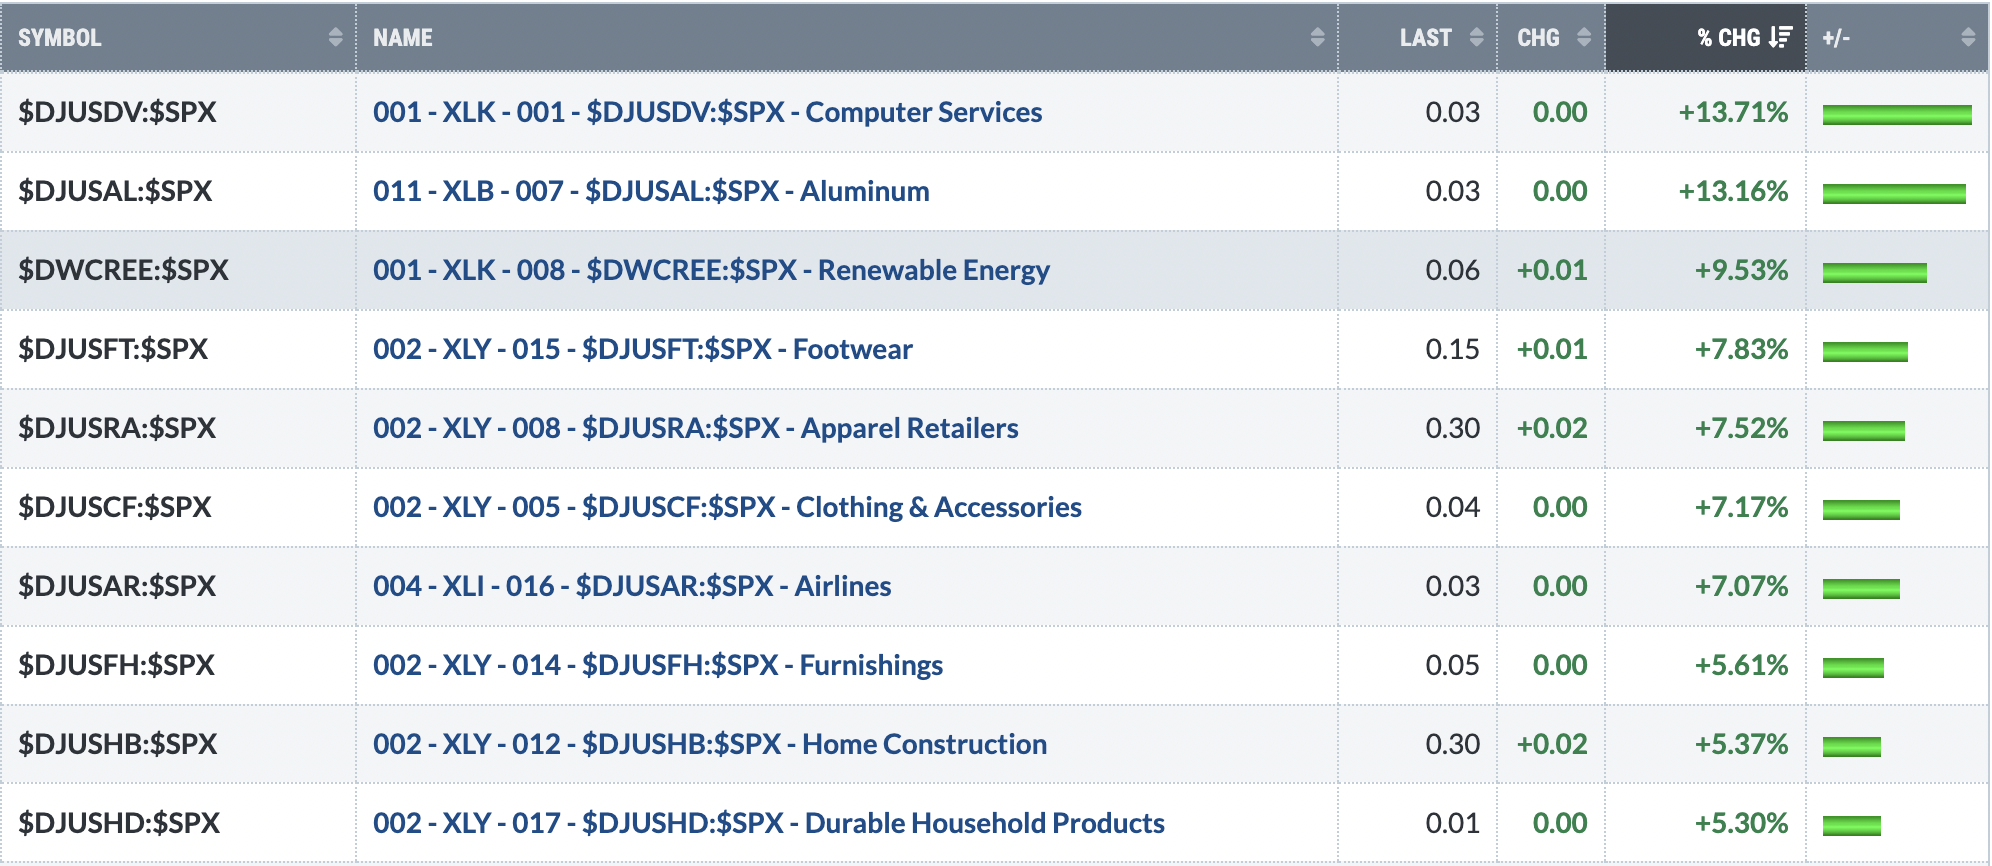
Top 10 Industries Last Week
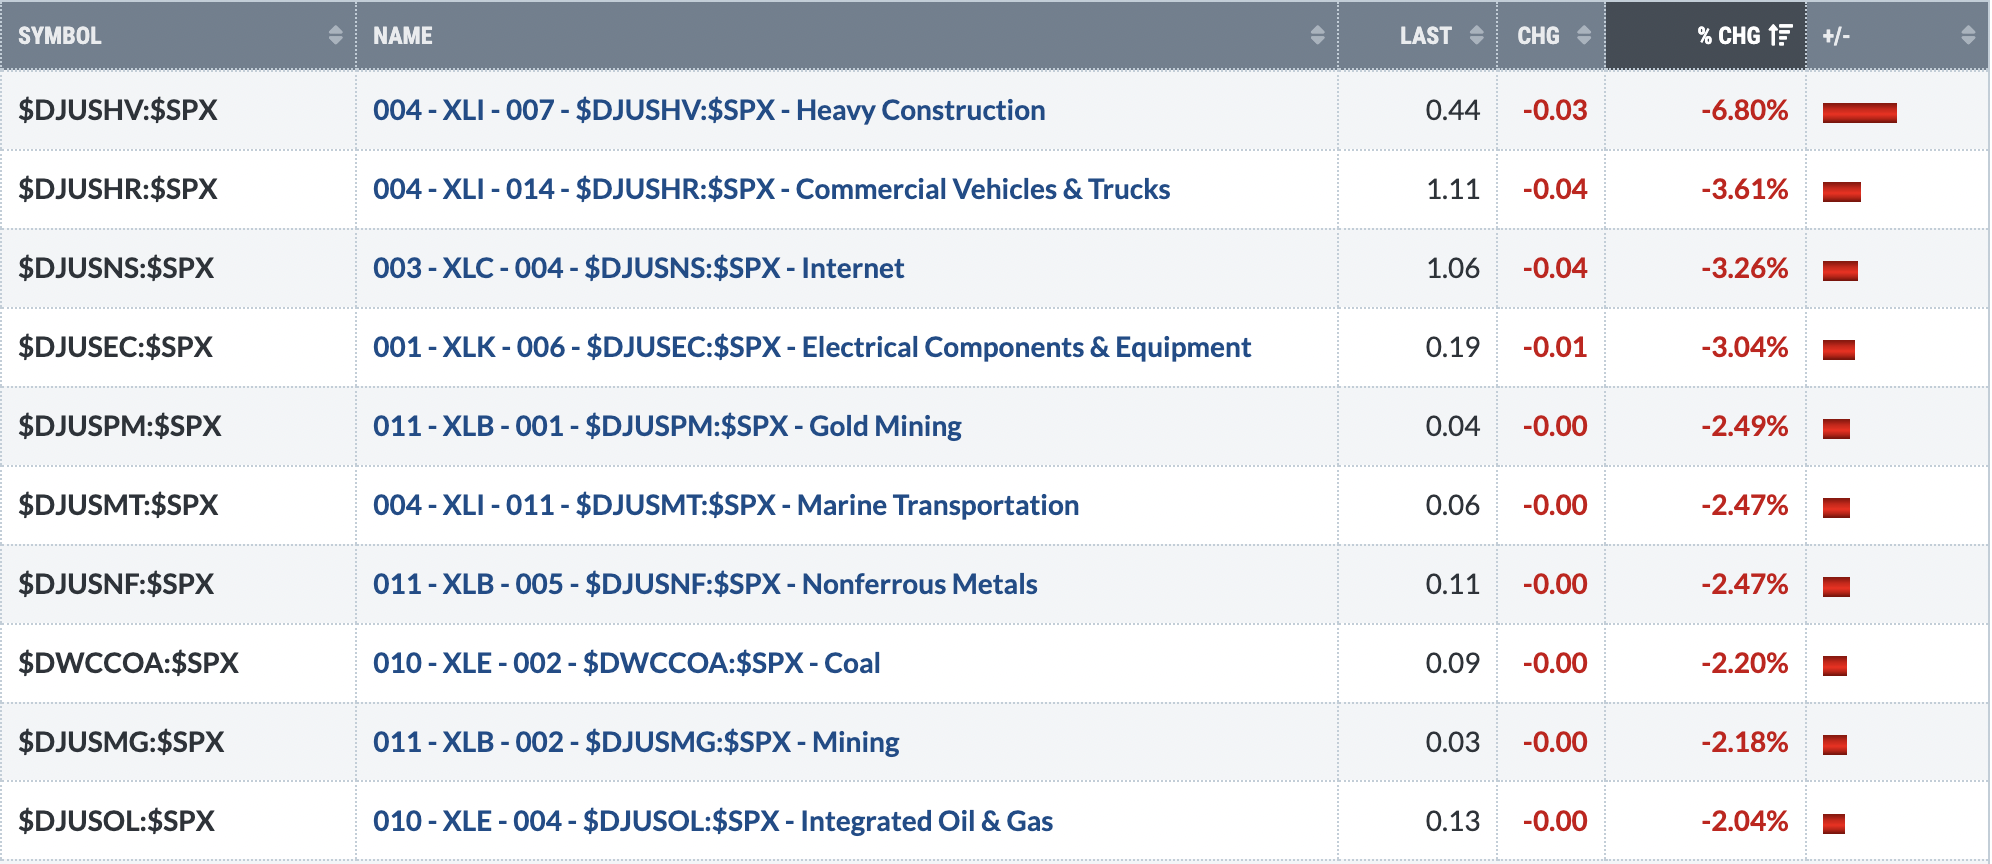
Bottom 10 Industries Last Week
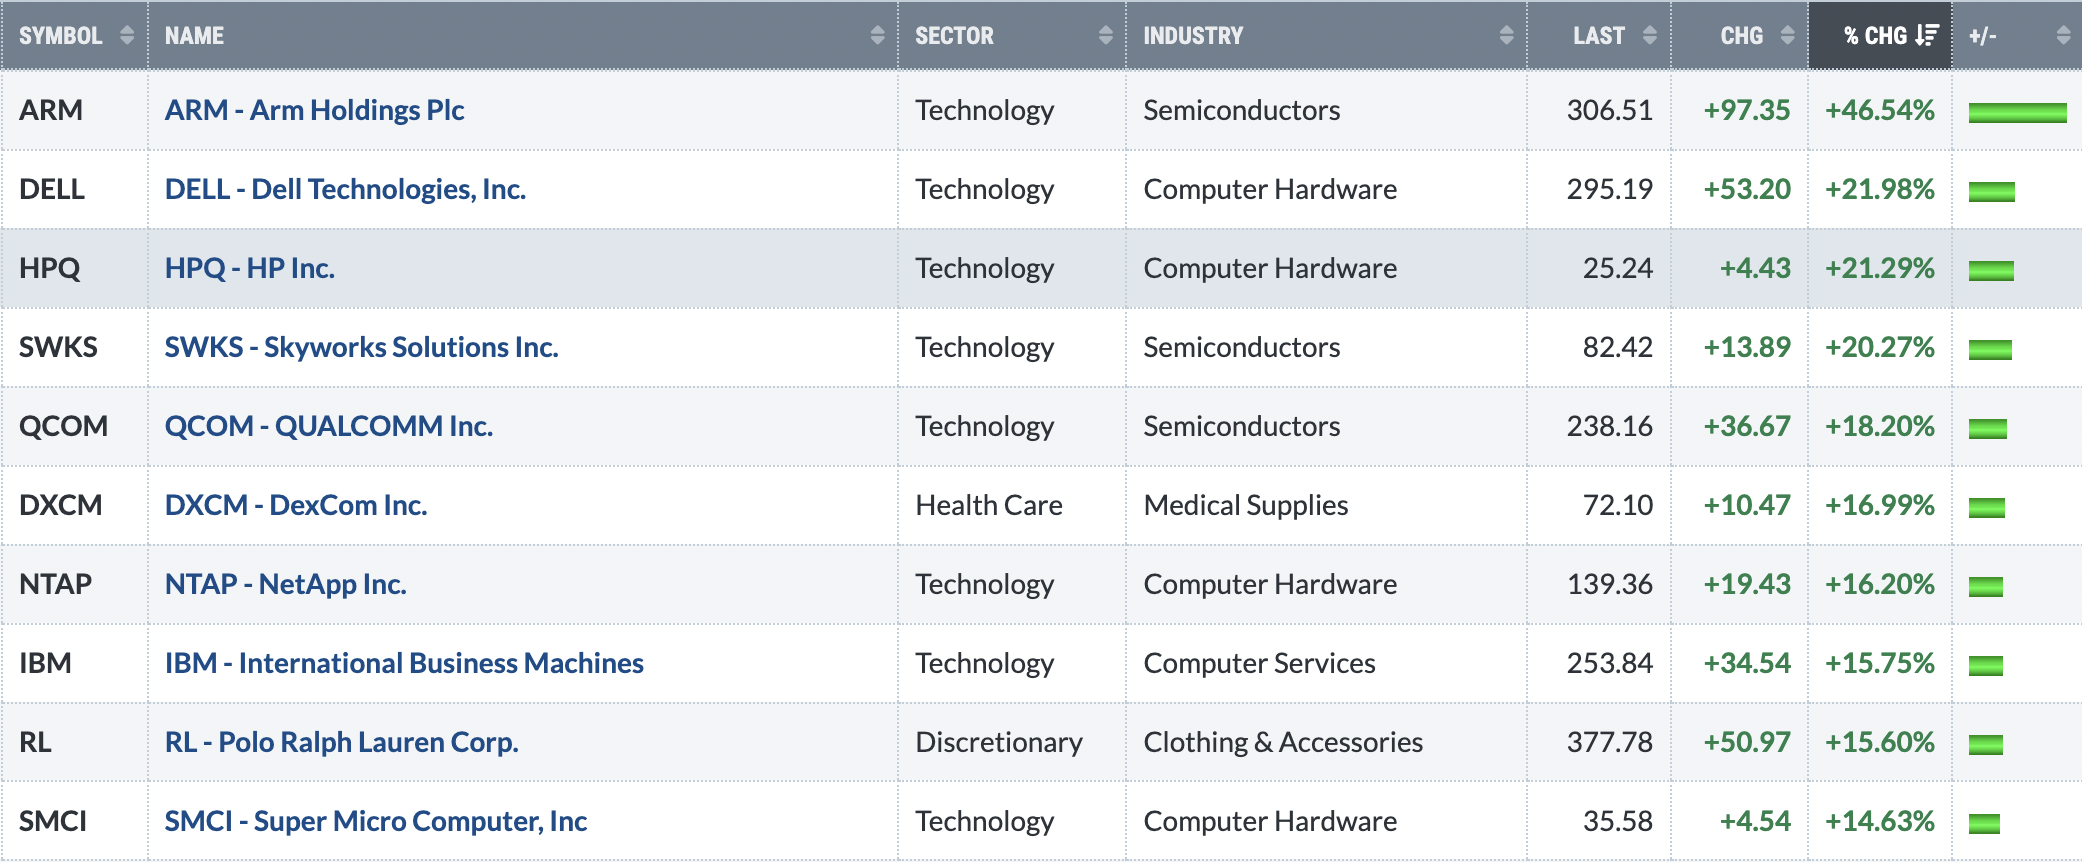
Top 10 Stocks - S&P 500/NASDAQ 100
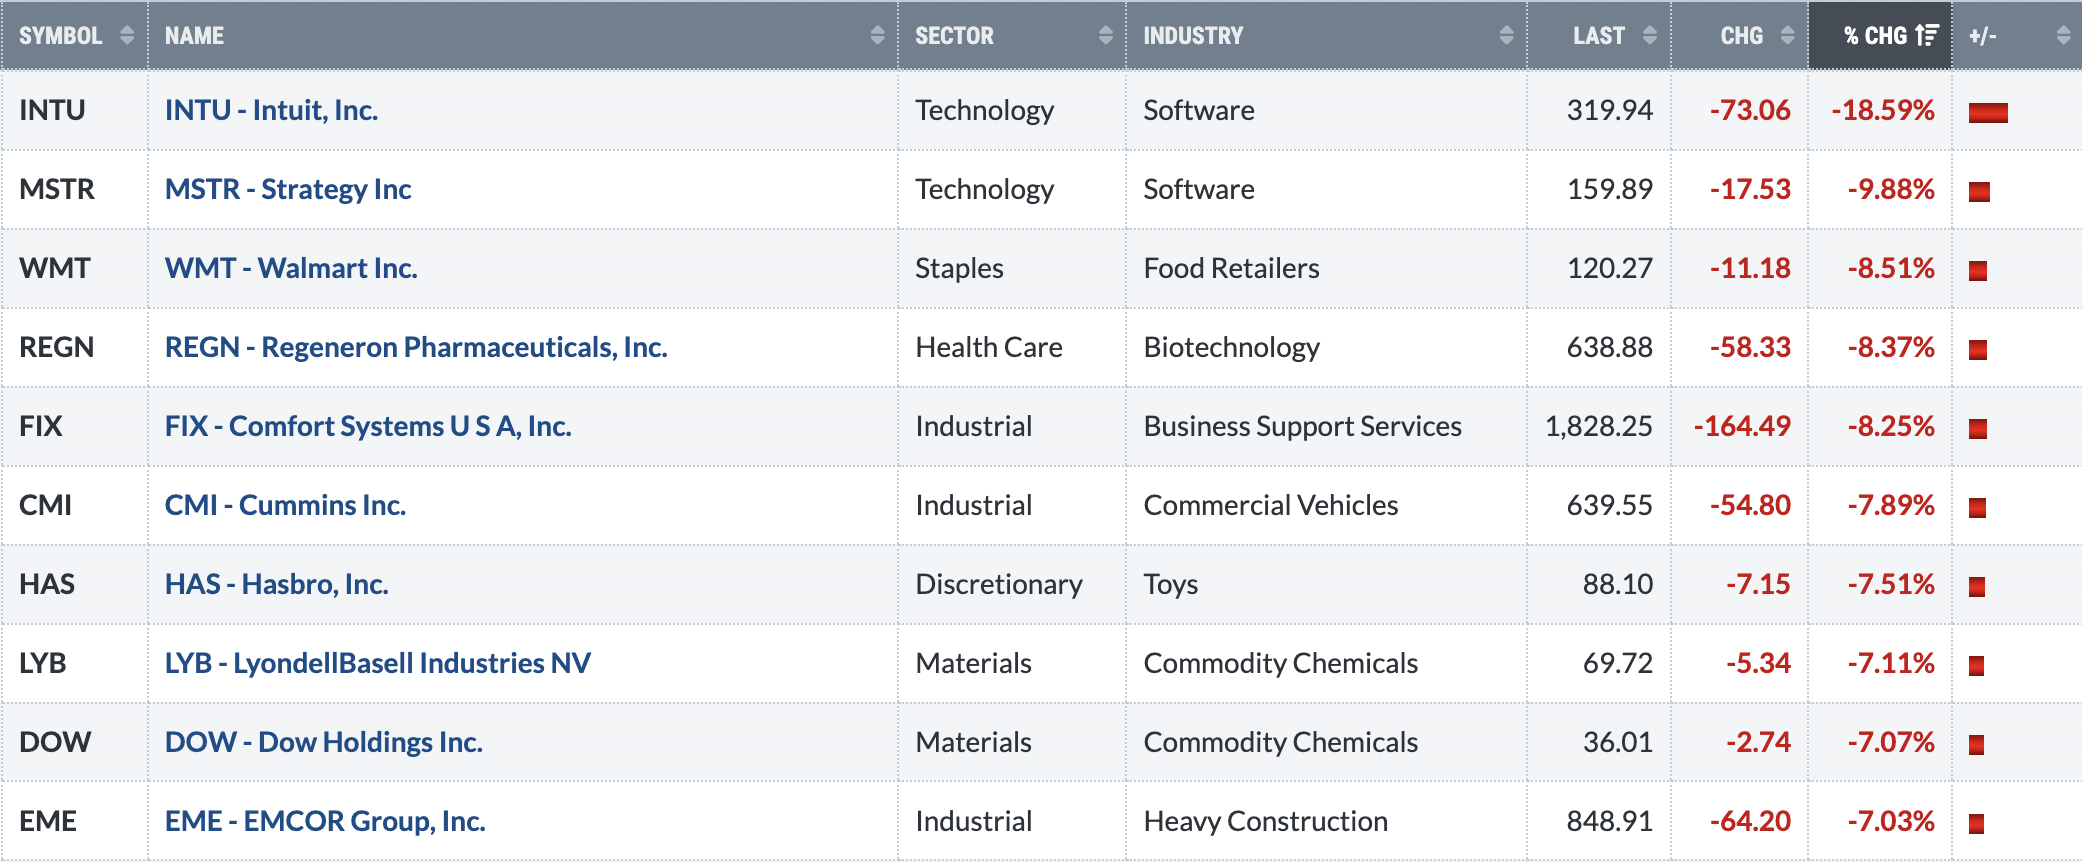
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
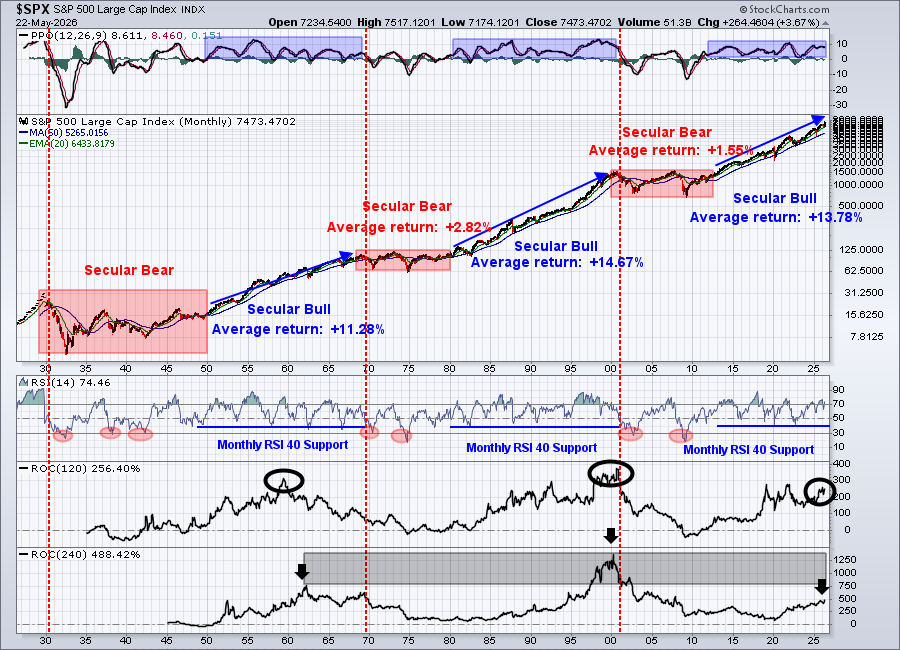
Last week, I suggested that 7500 was likely a short-term top and that we could see an upcoming 20-day EMA test. Well, there was a bit of weakness as the S&P 500 started the weak in negative territory, almost reaching its first 20-day EMA test since this rally started in late March. It didn't quite make it, however, and the bulls were at it again. The S&P 500 saw another test of 7500 on Friday, but wasn't able to clear it on a closing basis. This is a clear illustration why calling tops in a secular bull market advance is so dangerous. It took the bulls exactly 3 trading days to quickly resume the uptrend and test overhead price resistance.
I ALWAYS respect all-time high closes during secular bull markets, so if the S&P 500 can close above 7501, then it's "game on" once again for the bulls. Rotation into growth stocks did slow last week as we saw leadership from areas like utilities (XLU), health care (XLV), and real estate (XLRE) on the rebound.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
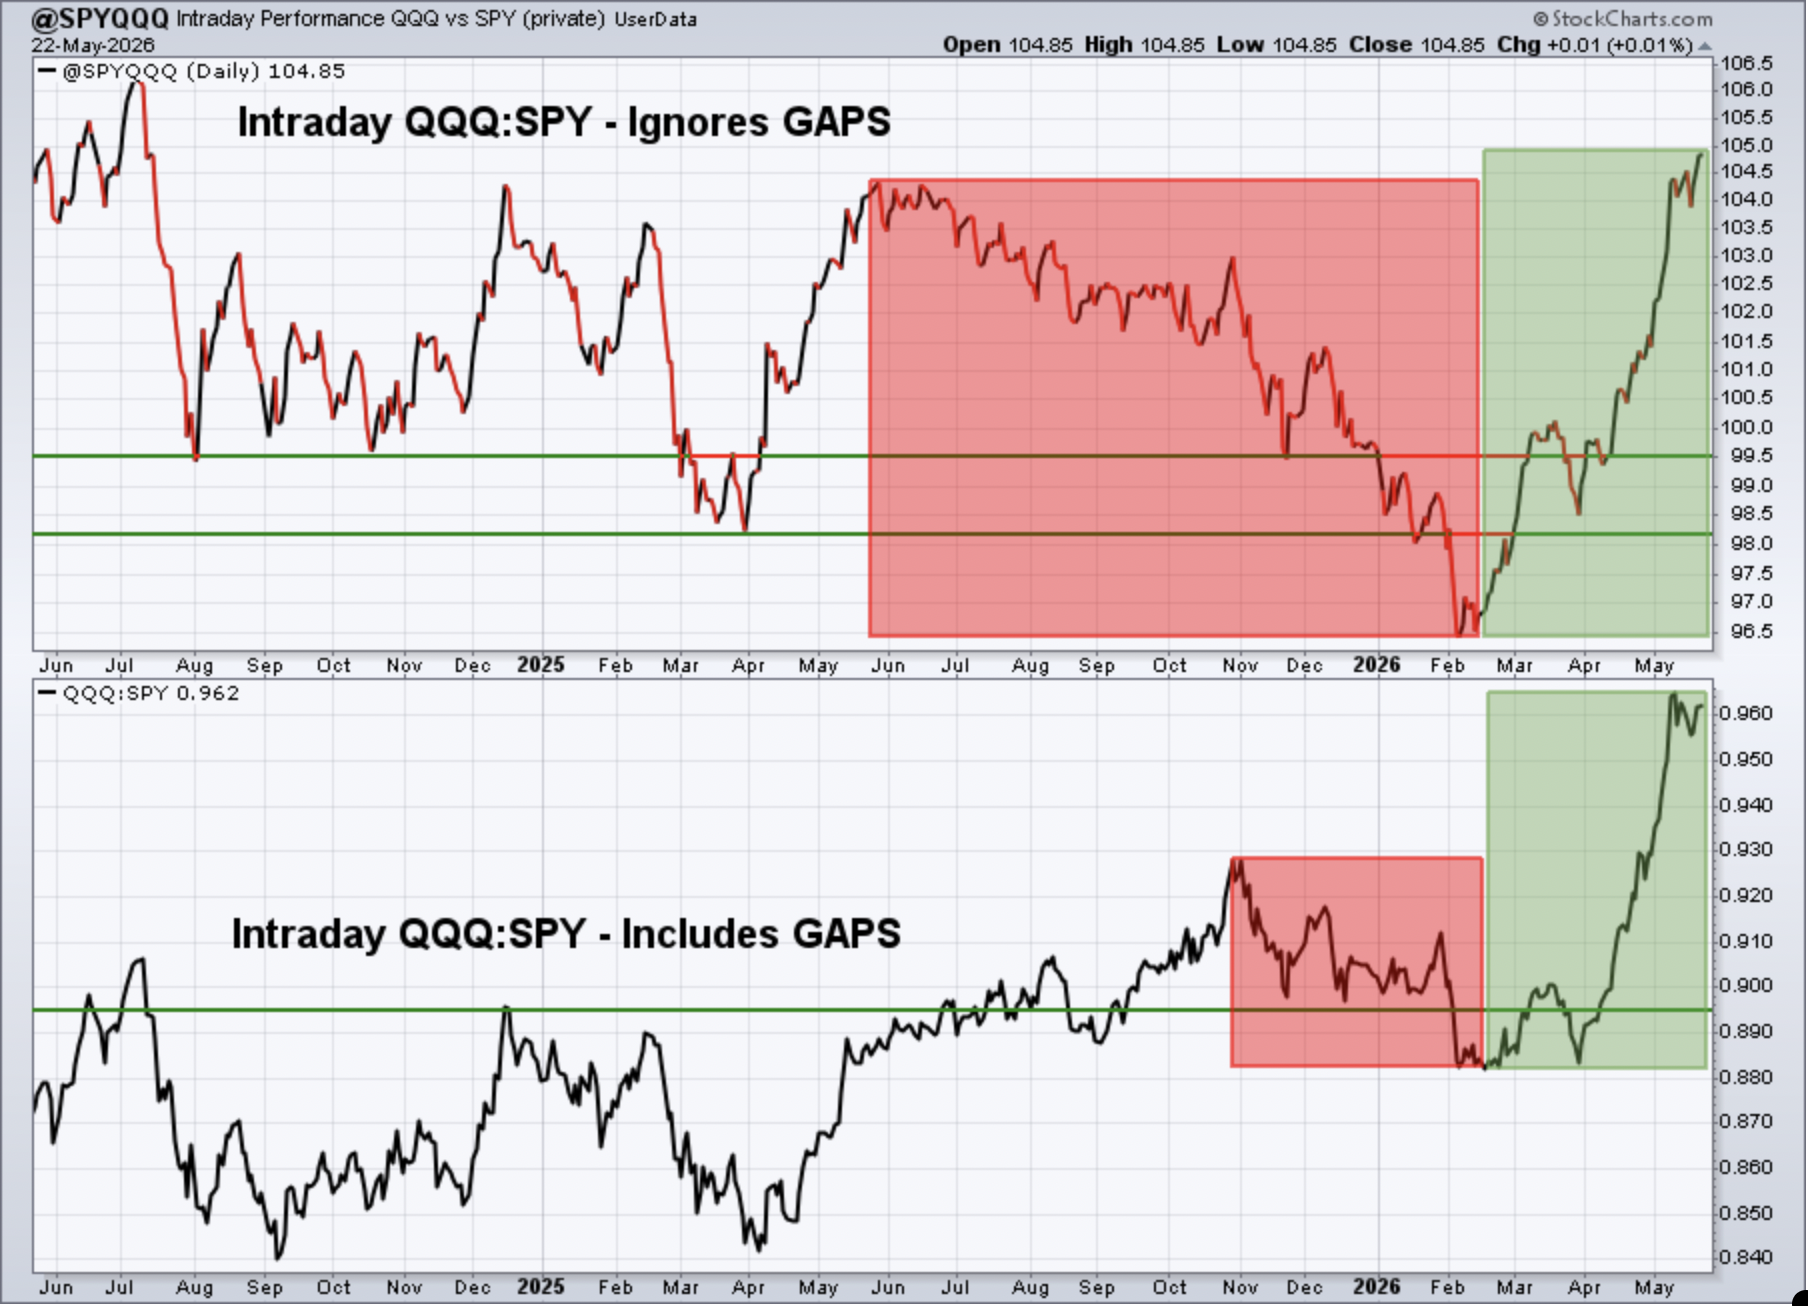
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
It's increasingly difficult to buy into the inflation hype when this ratio continues to push higher and higher.
IWM:QQQ
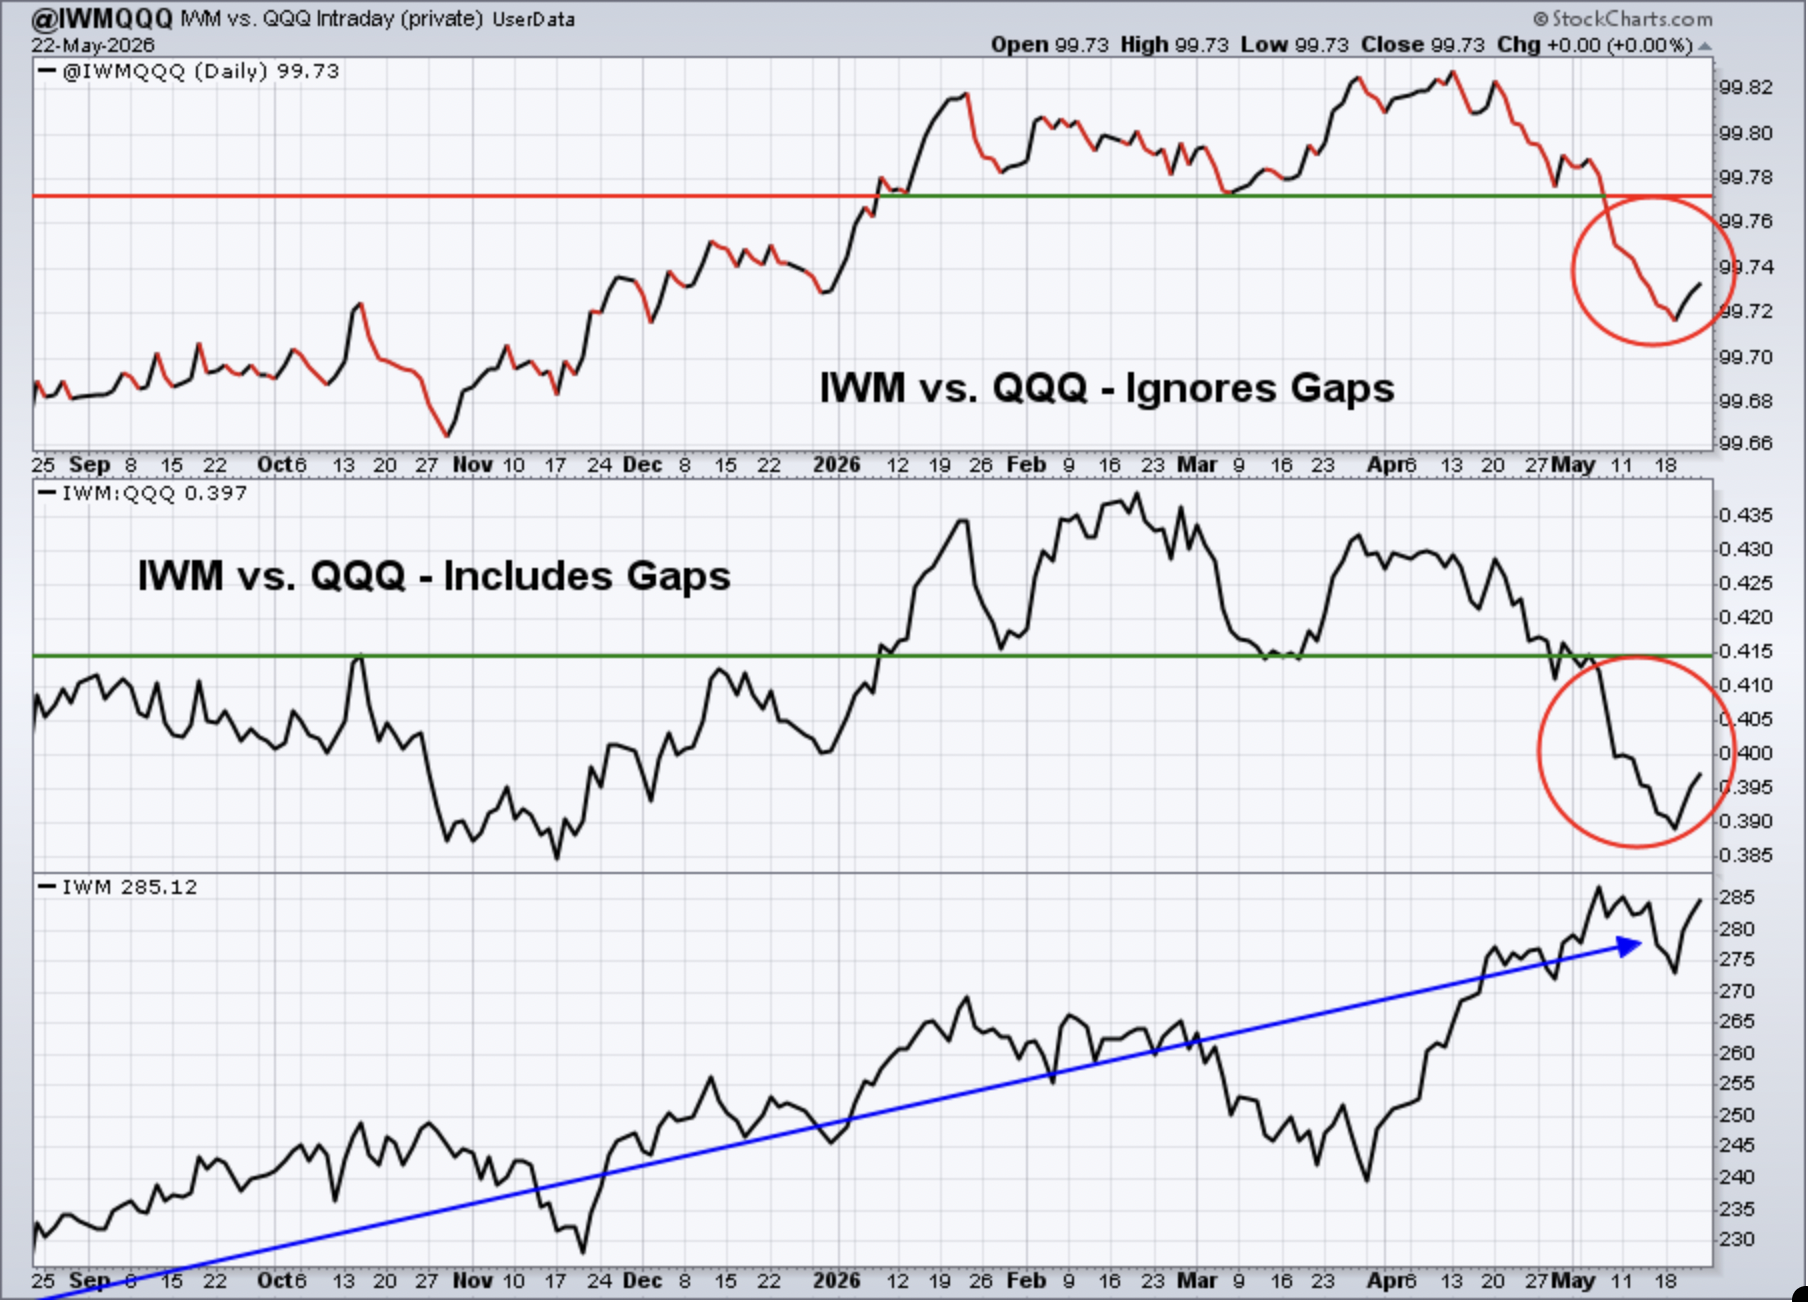
This intraday reading continues to spiral lower. While I don't believe inflation will be a longer-term issue, many market participants seem to be shying away from small caps with the 10-year treasury yield ($TNX) spiking. I see better days ahead for the IWM, but short-term, things are dicey in the small cap world.
XLY:XLP
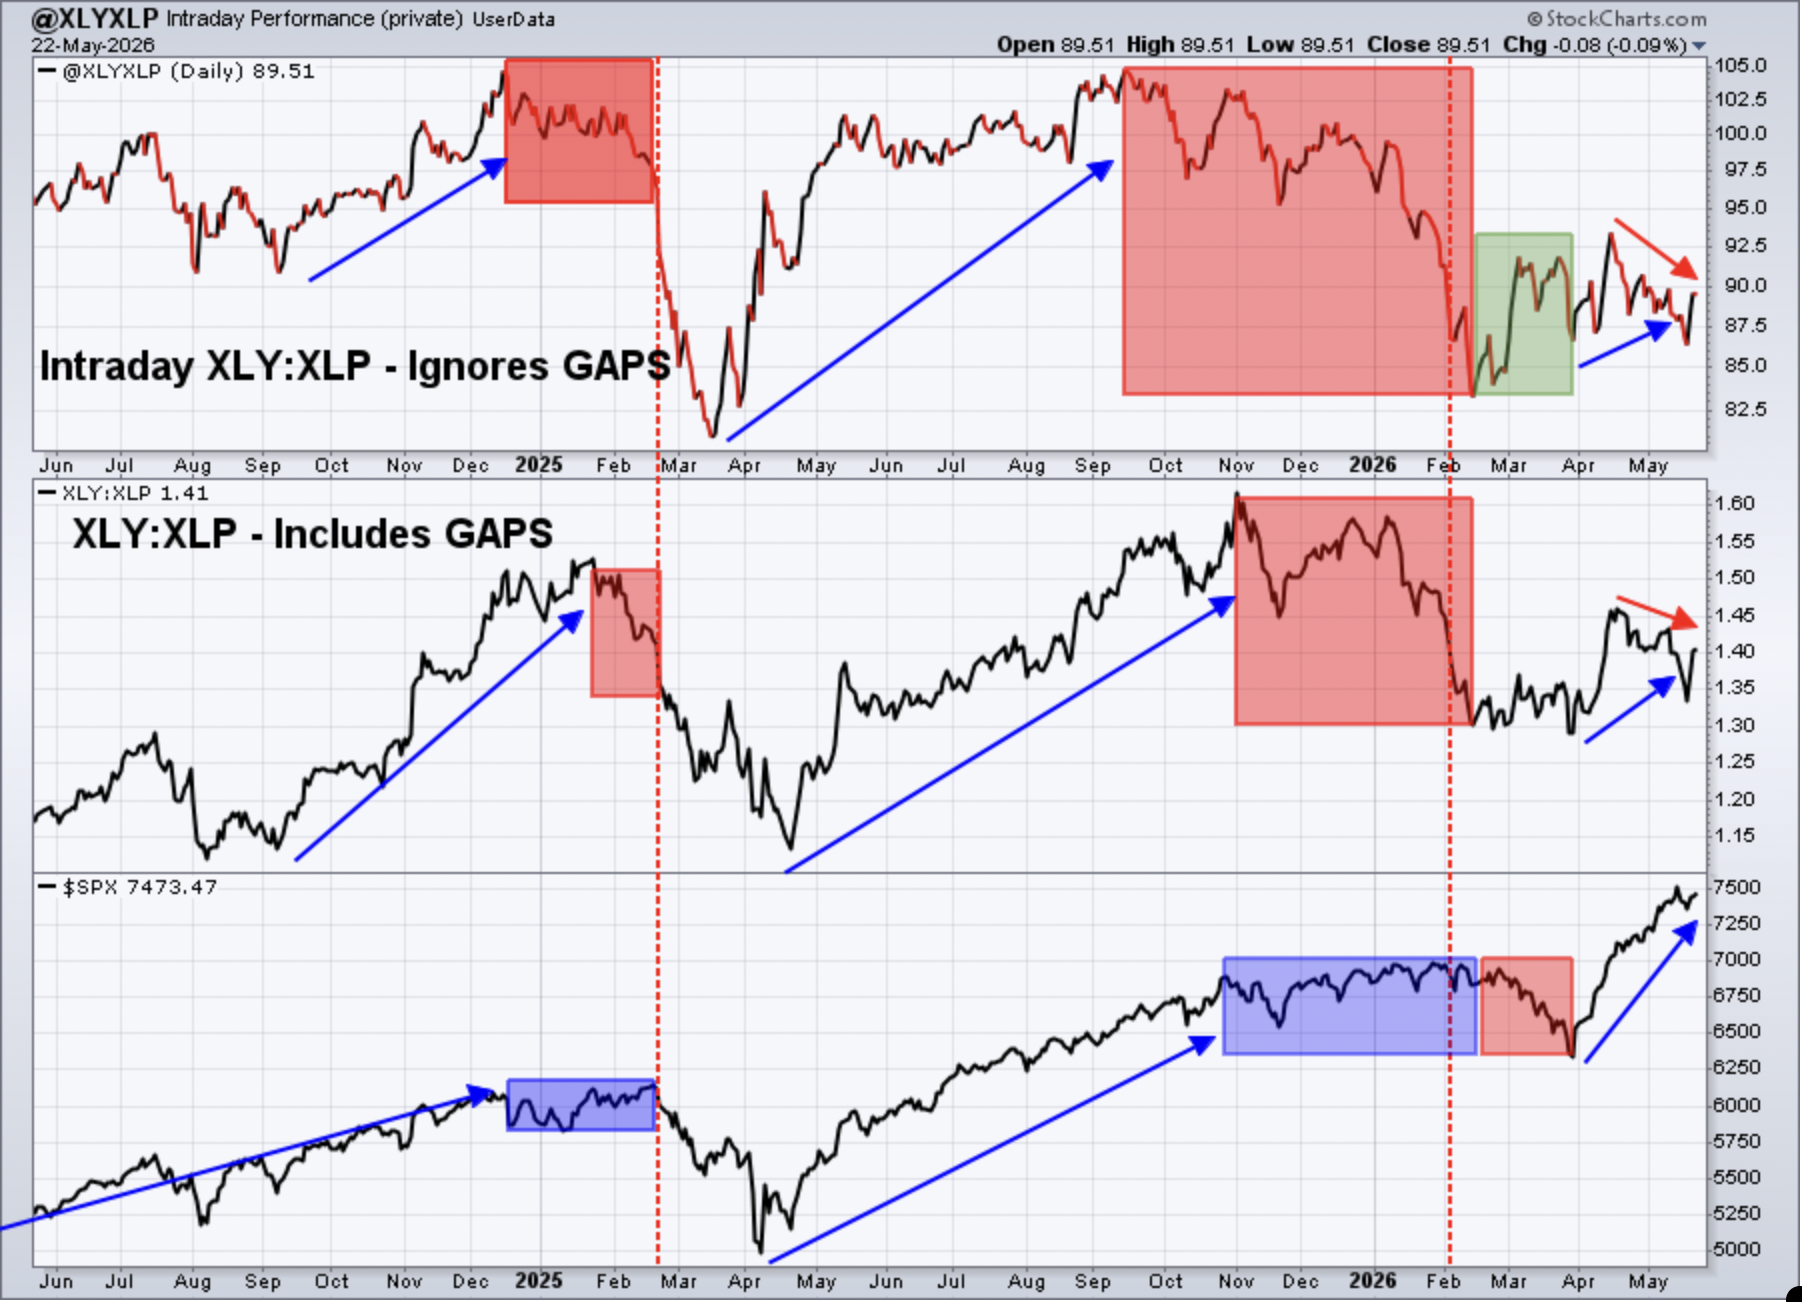
There remains some hesitation in this ratio, so it is reason to pause and check other indicators to see if there's corroboration. I don't see enough warning signs to believe that any pullback at hand would be anything other than a short-term pullback after an extended run. If this ratio should continue lower and clear both the intraday and closing XLY:XLP ratio support from late March, then I would be willing to consider that as a stronger warning.
There was reason for concern on the XLY:XLP ratio as it's been drifting lower and lower and is not really supporting the big upside move in the S&P 500. The bounce last week was welcome relief, though there is still plenty more work to do to reach new highs.
Sentiment
5-day SMA ($CPCE)
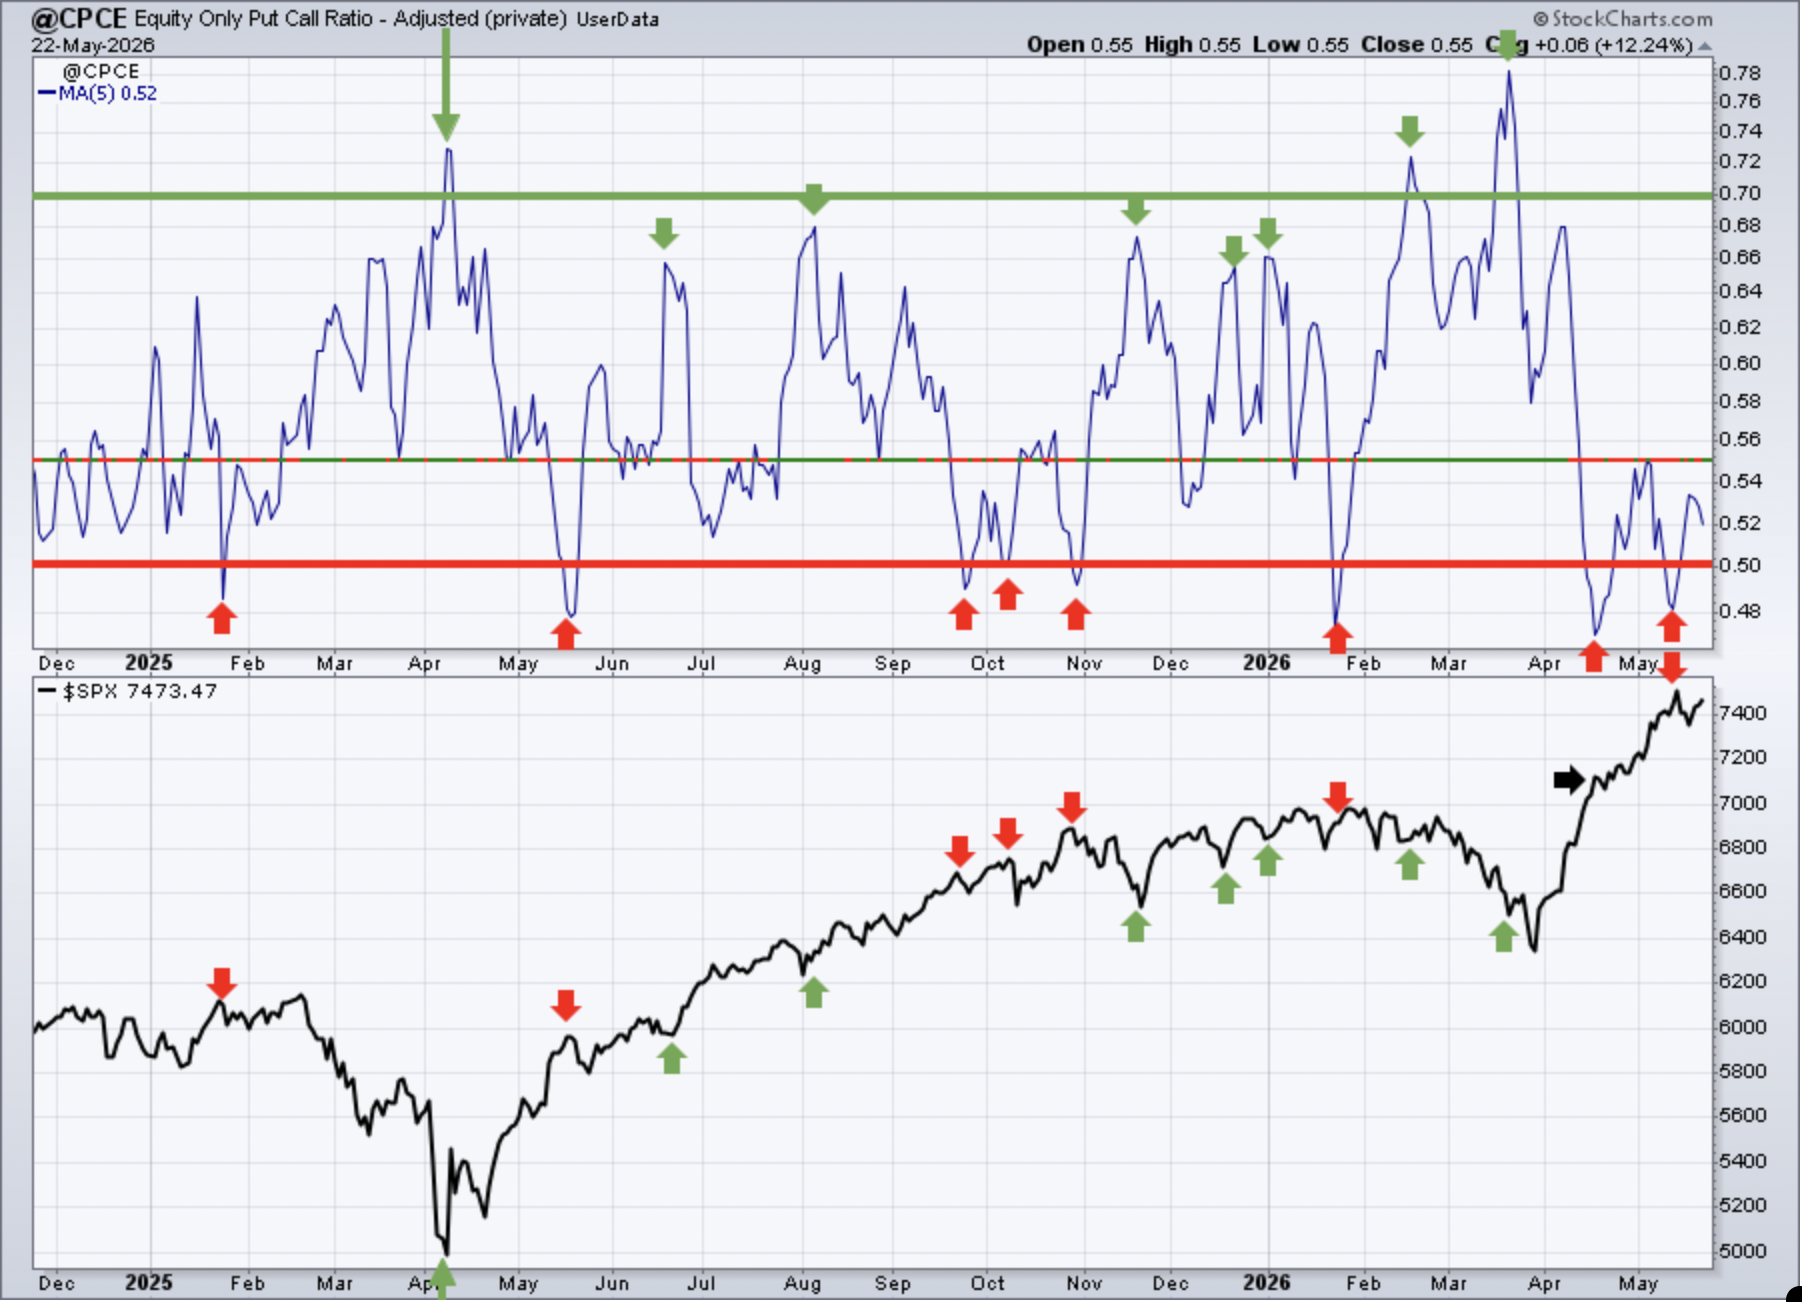
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
The latest short-term warning from this 5-day CPCE did produce a 2% or so drop in the S&P 500, but not much more. That's why I look at this sentiment indicator as my "speed boat" indicator. It provides very short-term reversal signals that, typically, are quite reliable.
253-day SMA ($CPCE)
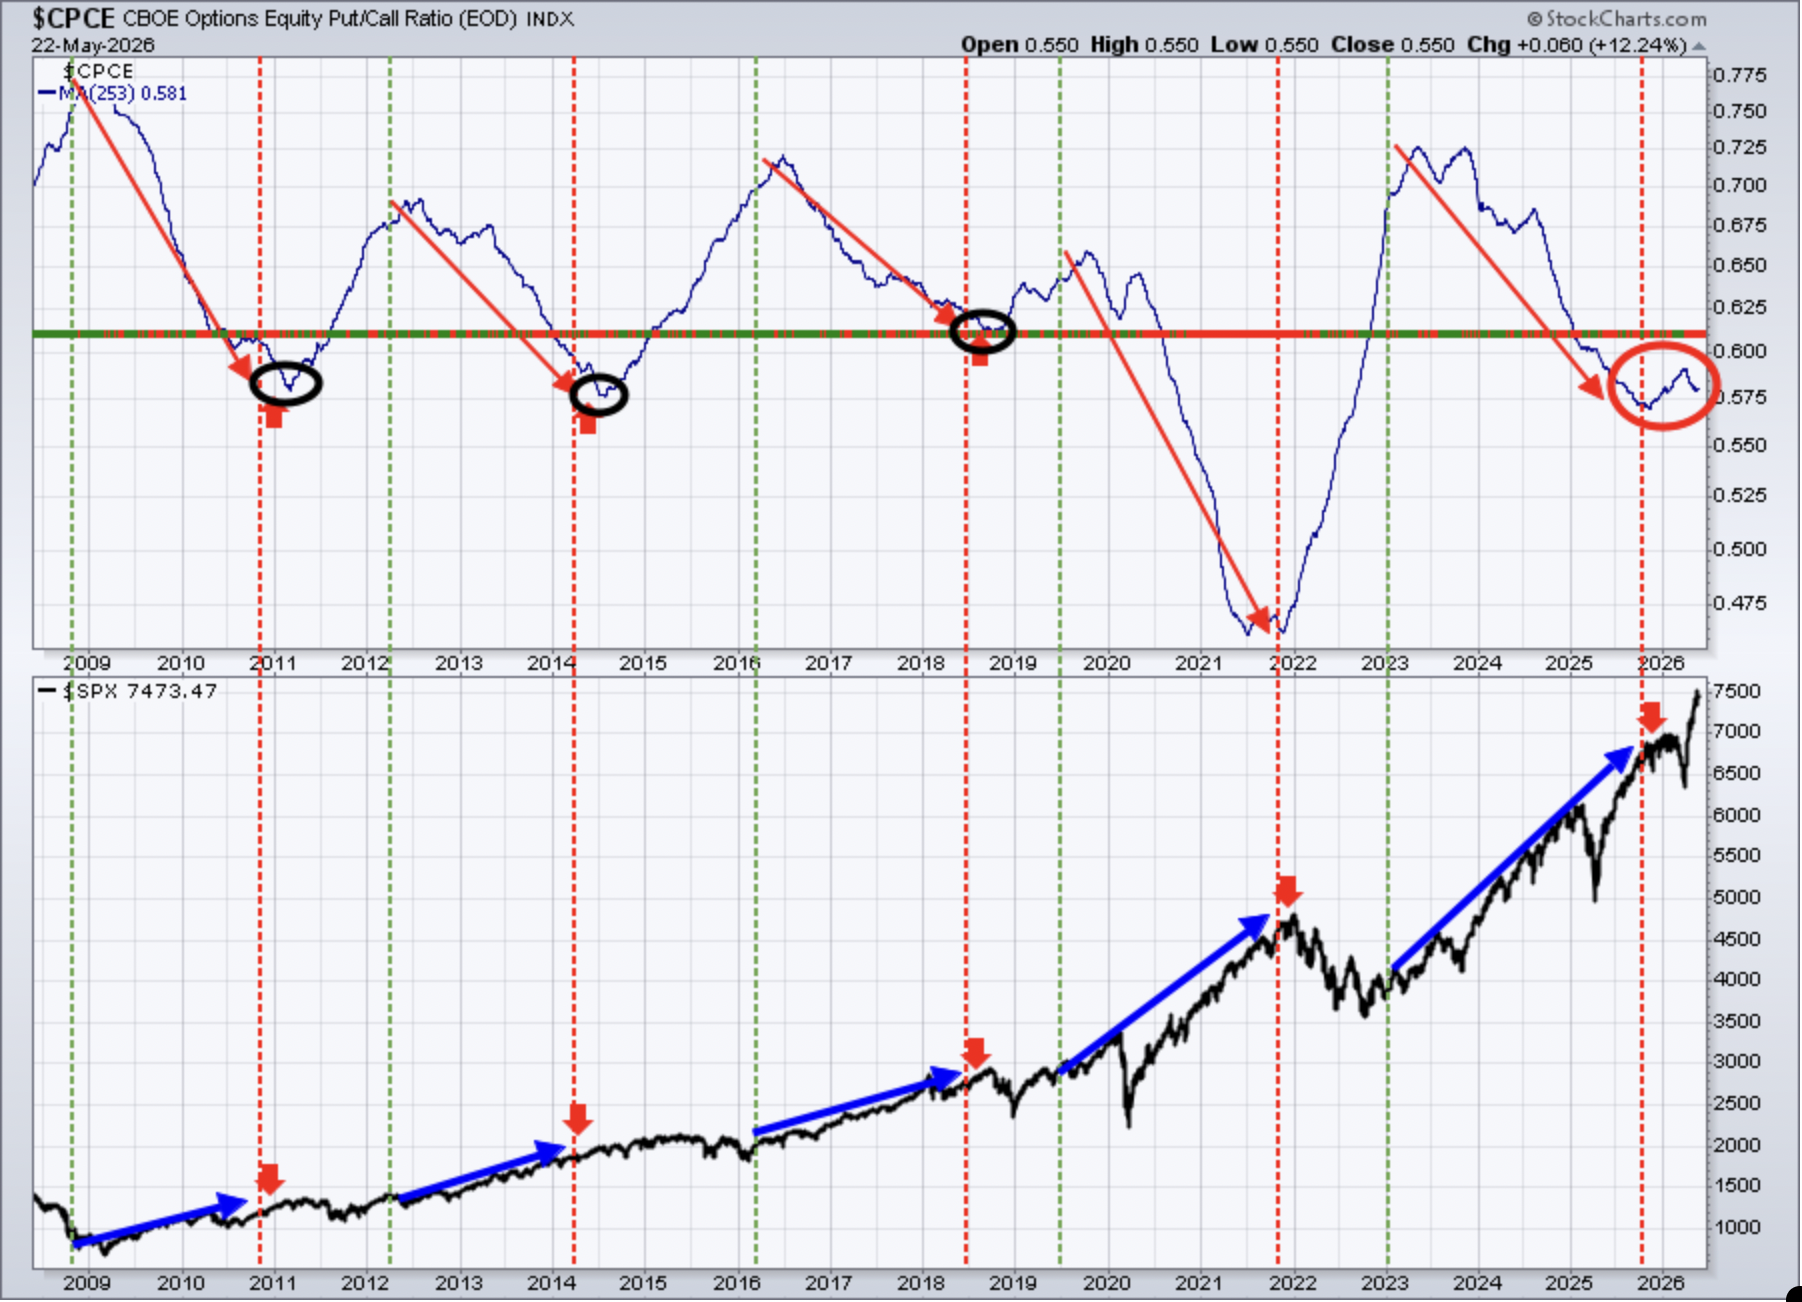
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500.
This long-term moving average seems to be searching for direction. It looked like we had reversed the downtrend and started potentially a lengthy rise. That has changed as this moving average rolls over and now heads lower. Which is it? I'd simply say this signal is neutral at the moment, though it will be bullish if it keeps moving lower.
Long-Term Trade Setups
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month, and I reviewed all of the following stocks as of Monday, May 4th:
- JPM – has consolidated with the entire banking industry, still looks solid
- BA – 275 remains the long-term obstacle, now trending above 20-month EMA
- FFIV – trending up above its 20-month EMA
- MA – last week's high pierced 20-week EMA, but was false breakout
- GS – very extended, remains strong relative to its investment services peers
- FDX – set new all-time high, but AMZN just announced competing service
- AAPL –strengthening on weekly chart, needs to clear 288.35
- CHRW – pulling back and consolidating after doubling in 6 months
- JBHT –nice breakout in 2026 after 3-4 years of consolidation
- STX - simply amazing run since April 2025 low, seems no end in sight
- HSY - very disappointing failure to hold onto 200 price support
- DIS - been waiting on this one for awhile, needs to hold 77-80 support
- MSCI - 4+ years of consolidation continues after prior rapid ascent
- SBUX - short-term breakout near 100, now staring at major 115 resistance
- KRE – still looks great in the long-term, awaiting lower interest rates
- ED – retesting recent breakout near the 110 level; 17-year uptrend intact
- AJG - year-long downtrend remains in place, watch 194.41 price support
- NSC – cup with handle breakout in mid-2025, measurement to 360 or so
- RHI – support in 22-23 range now established and needs to hold
- ADM – remains in solid uptrend off April 2025 low
- BG – breakout in January 2026 has led to further gains, nice uptrend
- CVS – big rally off 20-month EMA support, key resistance near 95
- HRL - weak stock, but it is a dividend aristocrat (raising dividends for 25 yrs+)
- DE – trending up, but continues to significantly underperform CAT
- LULU - will the bleeding stop at the 2020 pandemic low of 128.84?
- TTD - software is rebounding, but TTD's relative strength remains weak
- META - big gap lower last week with earnings, gap support is 606
- ADBE - bouncing with software rebound, key initial resistance at 259
- KMB - another dividend aristocrat, with solid price support at 95
- ORCL - added most recently and it's soared, leading April software rebound
- ABBV - added last week after a recent 20% decline to its 20-month EMA
- MCD - added last week after a 2 1/2 month decline, and amidst a rising yield
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: None
- Tuesday: AZO ($57 billion)
- Wednesday: MRVL ($171 billion), CRM ($144 billion), PDD ($139 billion), SNPS ($97 billion), SNOW ($57 billion)
- Thursday: COST ($466 billion), DELL ($163 billion), ADSK ($51 billion)
- Friday: None
Key Economic Reports
- Monday: None
- Tuesday: March S&P Case-Shiller home price index, May consumer confidence
- Wednesday: None
- Thursday: Initial jobless claims, April durable goods, April new home sales
- Friday: Q1 GDP (2nd estimate), April personal income & spending, April PCE index, May Chicago PMI
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- May 25: -15.90% (Ex: cumulative gains =
-2.89% over 46 trading days since 1950. -2.89% x 253/46 = -15.90%) - May 26: +54.11%
- May 27: +67.71%
- May 28: +2.19%
- May 29: +24.25%
- May 30: +46.09%
- May 31: +31.78%
- Jun 1: +54.02%
- Jun 2: +38.16%
- Jun 3: +6.79%
- Jun 4: -0.99%
- Jun 5: +44.59%
- Jun 6: +59.15%
- Jun 7: +3.37%
NASDAQ (since 1971)
- May 25: +15.82%
- May 26: +106.29%
- May 27: +175.36%
- May 28: +37.03%
- May 29: -36.86%
- May 30: +28.79%
- May 31: -8.12%
- Jun 1: +73.91%
- Jun 2: +132.50%
- Jun 3: -59.13%
- Jun 4: +80.53%
- Jun 5: +99.55%
- Jun 6: -5.16%
- Jun 7: +17.61%
Russell 2000 (since 1987)
- May 25: +38.88%
- May 26: +170.50%
- May 27: +199.60%
- May 28: +0.94%
- May 29: +4.42%
- May 30: +44.38%
- May 31: +24.72%
- Jun 1: +113.13%
- Jun 2: +173.13%
- Jun 3: -44.86%
- Jun 4: +38.36%
- Jun 5: +85.52%
- Jun 6: -4.31%
- Jun 7: +32.75%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Max pain has come and gone for the month of May. After the massive run up off of the late-March low, there were a TON of net in-the-money call premium on the table for market makers and we saw what happened on Friday, Monday, and Tuesday. The SPY fell from Thursday's close of 748.17 to Tuesday's close of 733.73. That's only a 2% or so drop, but it literally saved option payouts of billions of dollars. And perhaps the most interesting part was the fact that the SPY fell 9.59 on gap downs over those 3 days. That was roughly two-thirds of the entire drop. So you tell me.....was there really a lot of selling or was it just market maker manipulation, legally stealing from options holders? I mean, 3 days later, we're right back where we were before the options-related selling occurred.
These big Wall Street firms are THIEVES. Anyhow, it's over for this month, so here's what I'm focused on this week:
Technical Price Action. I was looking for a potential 20-day EMA test last week, given the typical negative action associated with monthly options expiration and the early part of the week following, especially the Monday that follows monthly-options-expiration Friday. We did see the semi ETF (SOXX) test its 20-day EMA on Tuesday of last week, but this group showed its power by snapping back and moving to yet another all-time high. I was a bit surprised by that action, however, I've said many times before that secular bull markets wait for no one. We should always respect all-time highs. The most important technical signal that I'll be watching is the rising 20-day EMA across our major indices and sectors.
Interest Rates. Just like the stock market, the bond market sold off for 3 days, Friday through Tuesday, and the 10-year treasury yield ($TNX) soared from 4.46% to a high of 4.69%. That took a toll on interest-rate-sensitive areas like small caps (IWM) and home construction ($DJUSHB). The good news, however, is that treasury yields turned considerably lower over the second half of last week and those two areas recovered rapidly. I still view 4.75% and 5.00% as the two key levels of yield resistance to watch. I don't believe we'll see the TNX move above 5.00%, but it sure would be interesting to see how the stock market reacts if it happens.
Energy. There's no area of the stock market more volatile than energy (XLE). It seems as though just a few texts from the President or media commentary can move this sector 5-10% very quickly. The trading range for crude oil is quite wide at $85-$120 per barrel, in my opinion. Developments in Iran, or the lack thereof, are totally controlling the action here. If you can predict the short-term tops and bottoms in this group, you can make a lot of money. I'm not that good.
Seasonality. The next week to ten days certainly favor the bulls. Scroll up and check out the annualized returns, by day, of each of our 3 key indices. May 26th through June 5th or 6th historically produces solid annualized gains, which also lines up with how most calendar months trade. The last several days of one calendar month and the first 3-5 days of the next tend to produce the lions share of market gains since 1950.
Happy trading!
Tom