
EB Weekly Market Report - Monday, August 10, 2026
ChartLists/Spreadsheets
The following ChartLists/Spreadsheets will be updated by tonight and will be updated on our website later this evening:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Strong AD (SADCL)
- Bullish Trifecta (BTCL)
- Short Squeeze (SSCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL) - no changes from last week, same 20 stocks
- Upcoming Earnings
- Upcoming Earnings Relative Strength
The above ChartLists have been updated through Friday, August 14th. You can view and/or download these ChartLists from our website, and also read about them to gain a better understanding of how they can help in your trading success.
The Key Manipulation spreadsheet was not updated last weekend, because of the massive number of earnings reports. It was updated this weekend, however, and will be updated on our website later this evening as well.
Weekly Market Recap
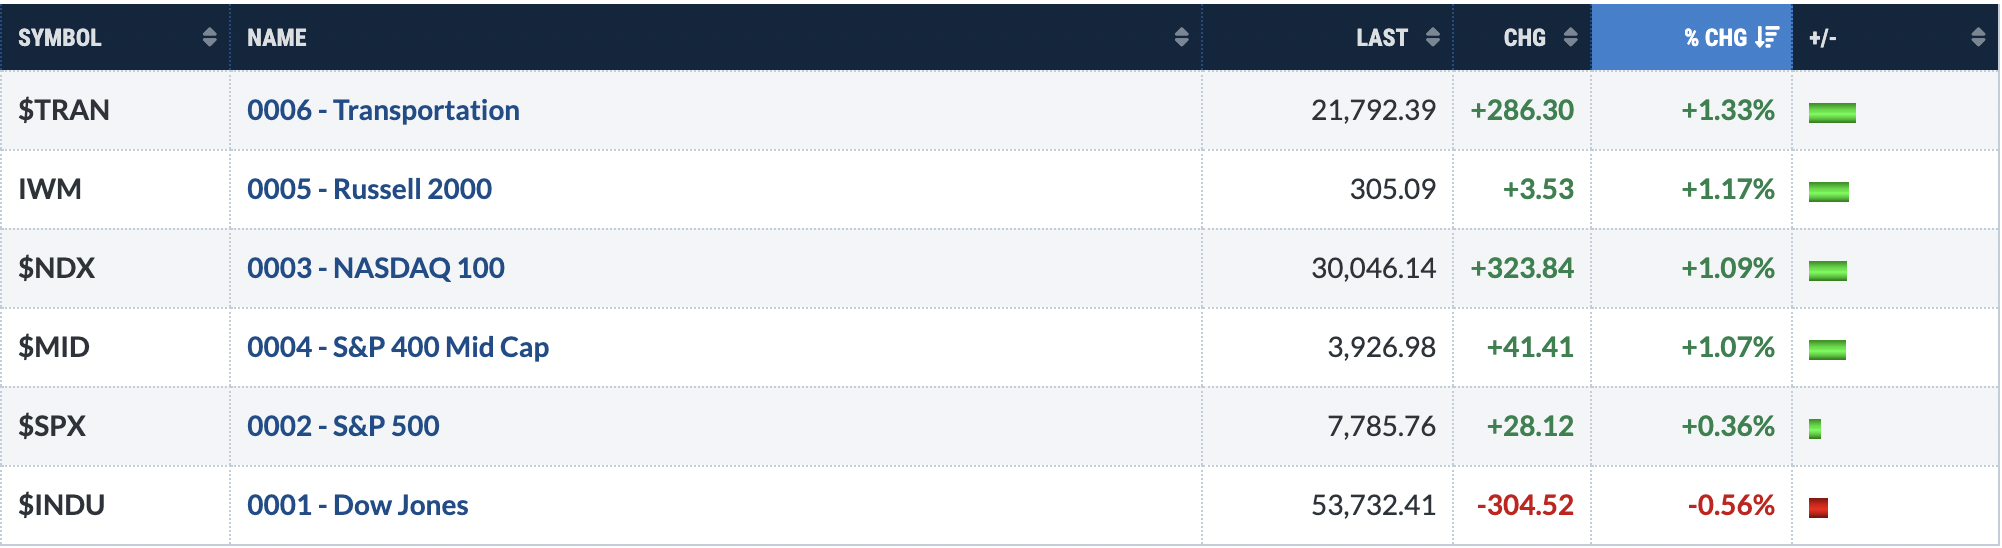
Major Indices
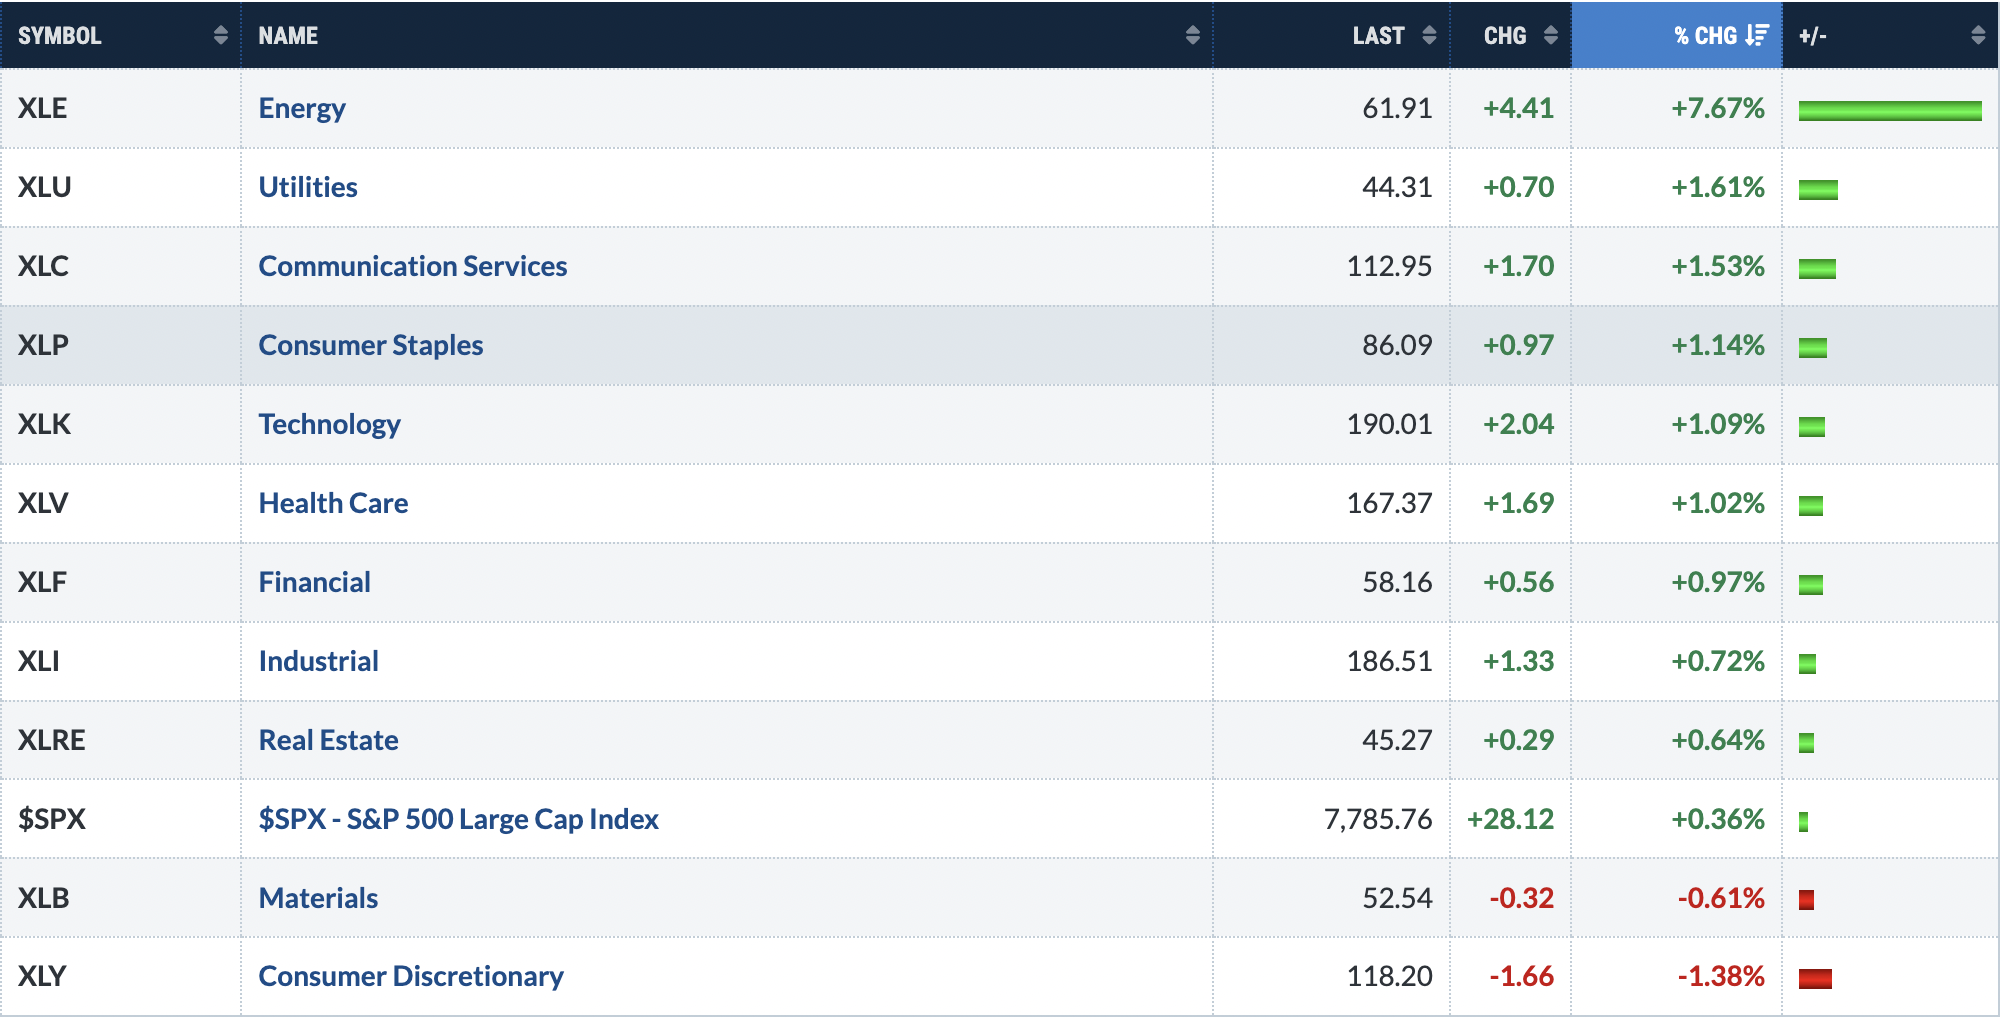
Sectors
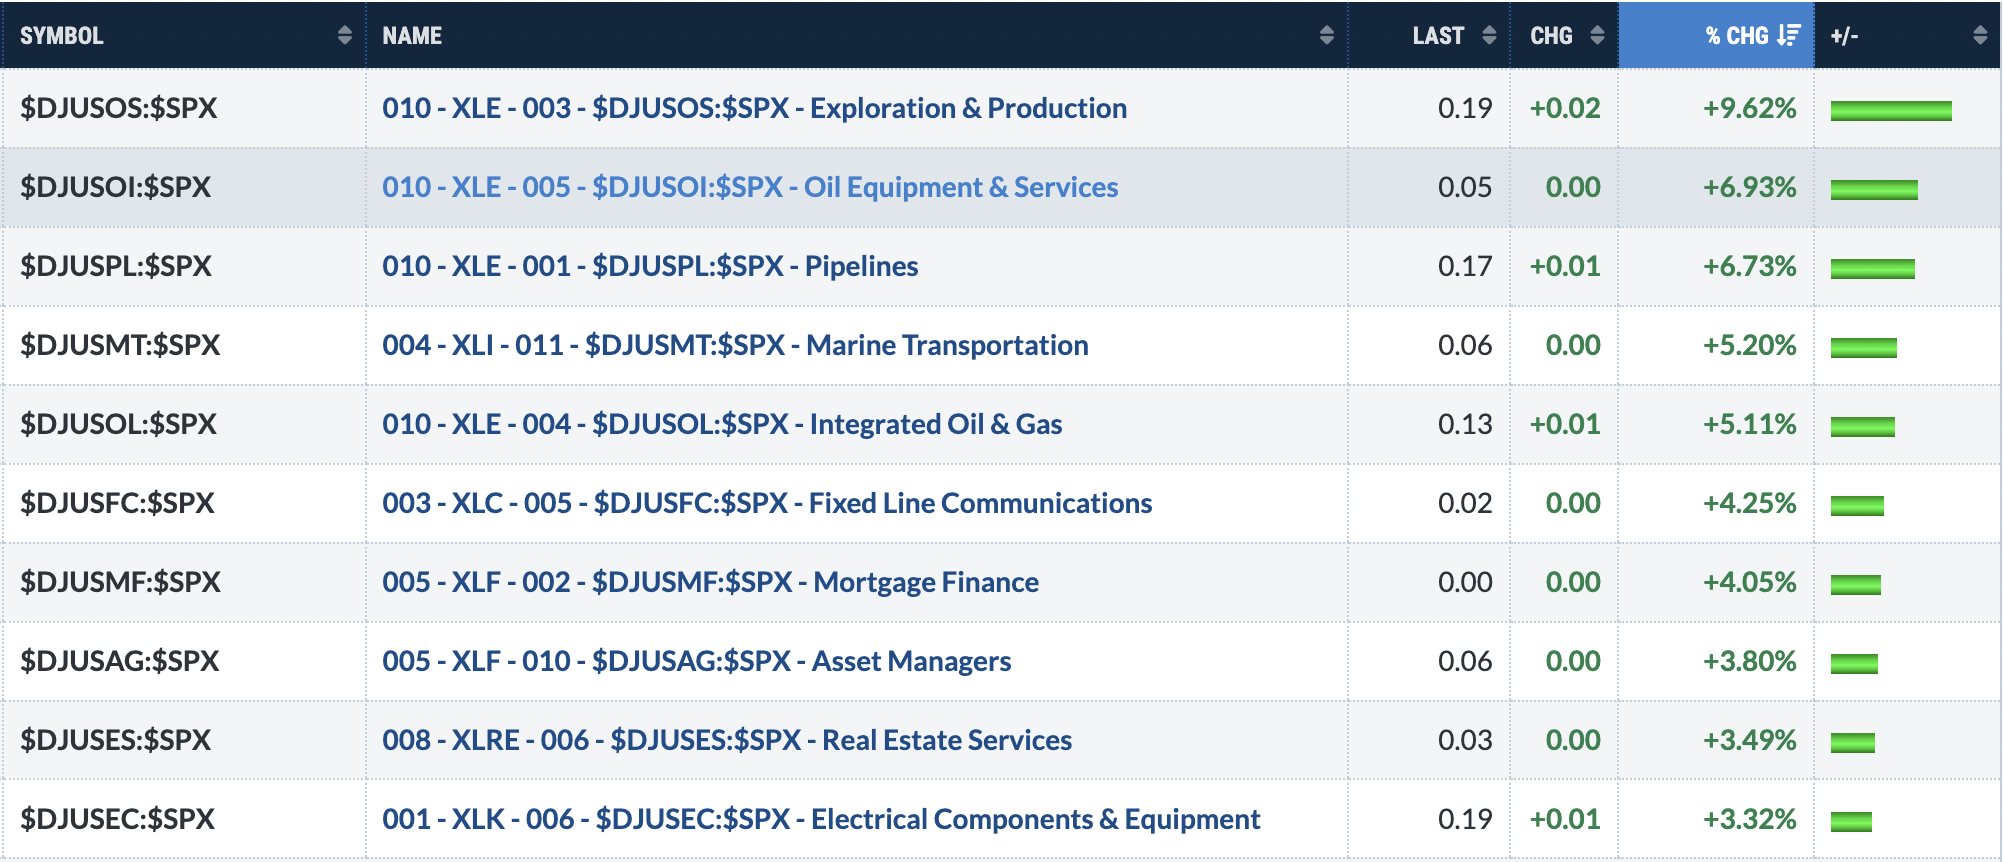
Top 10 Industries Last Week
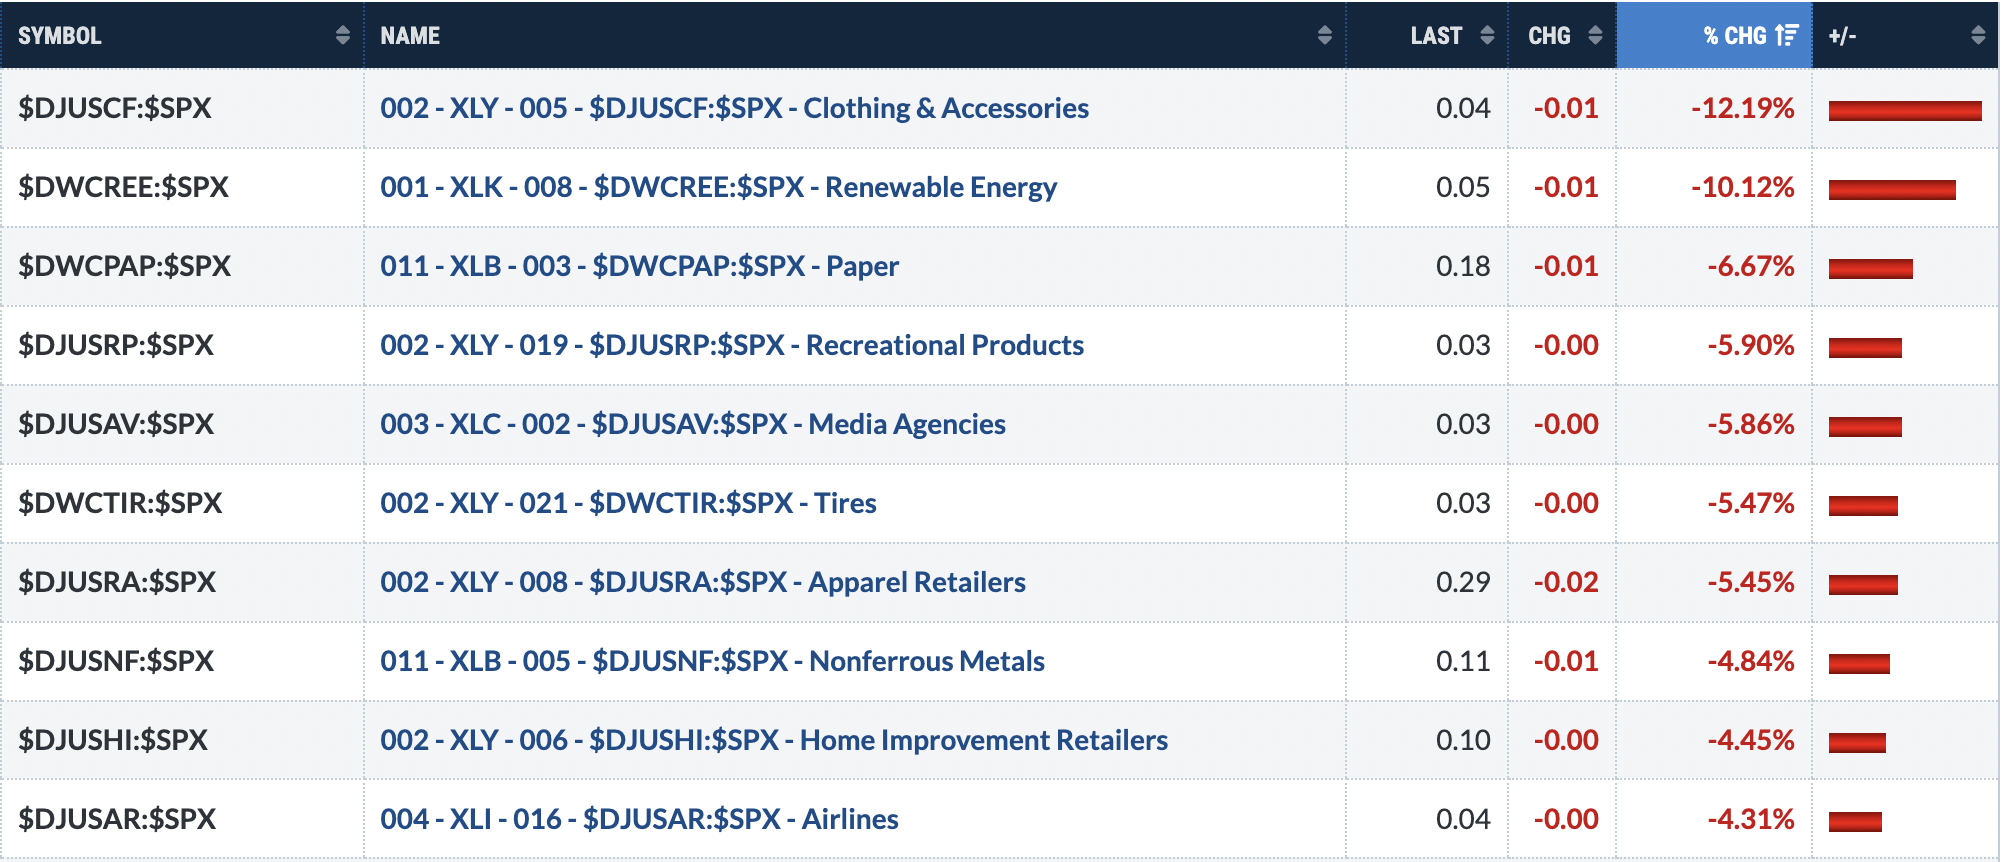
Bottom 10 Industries Last Week
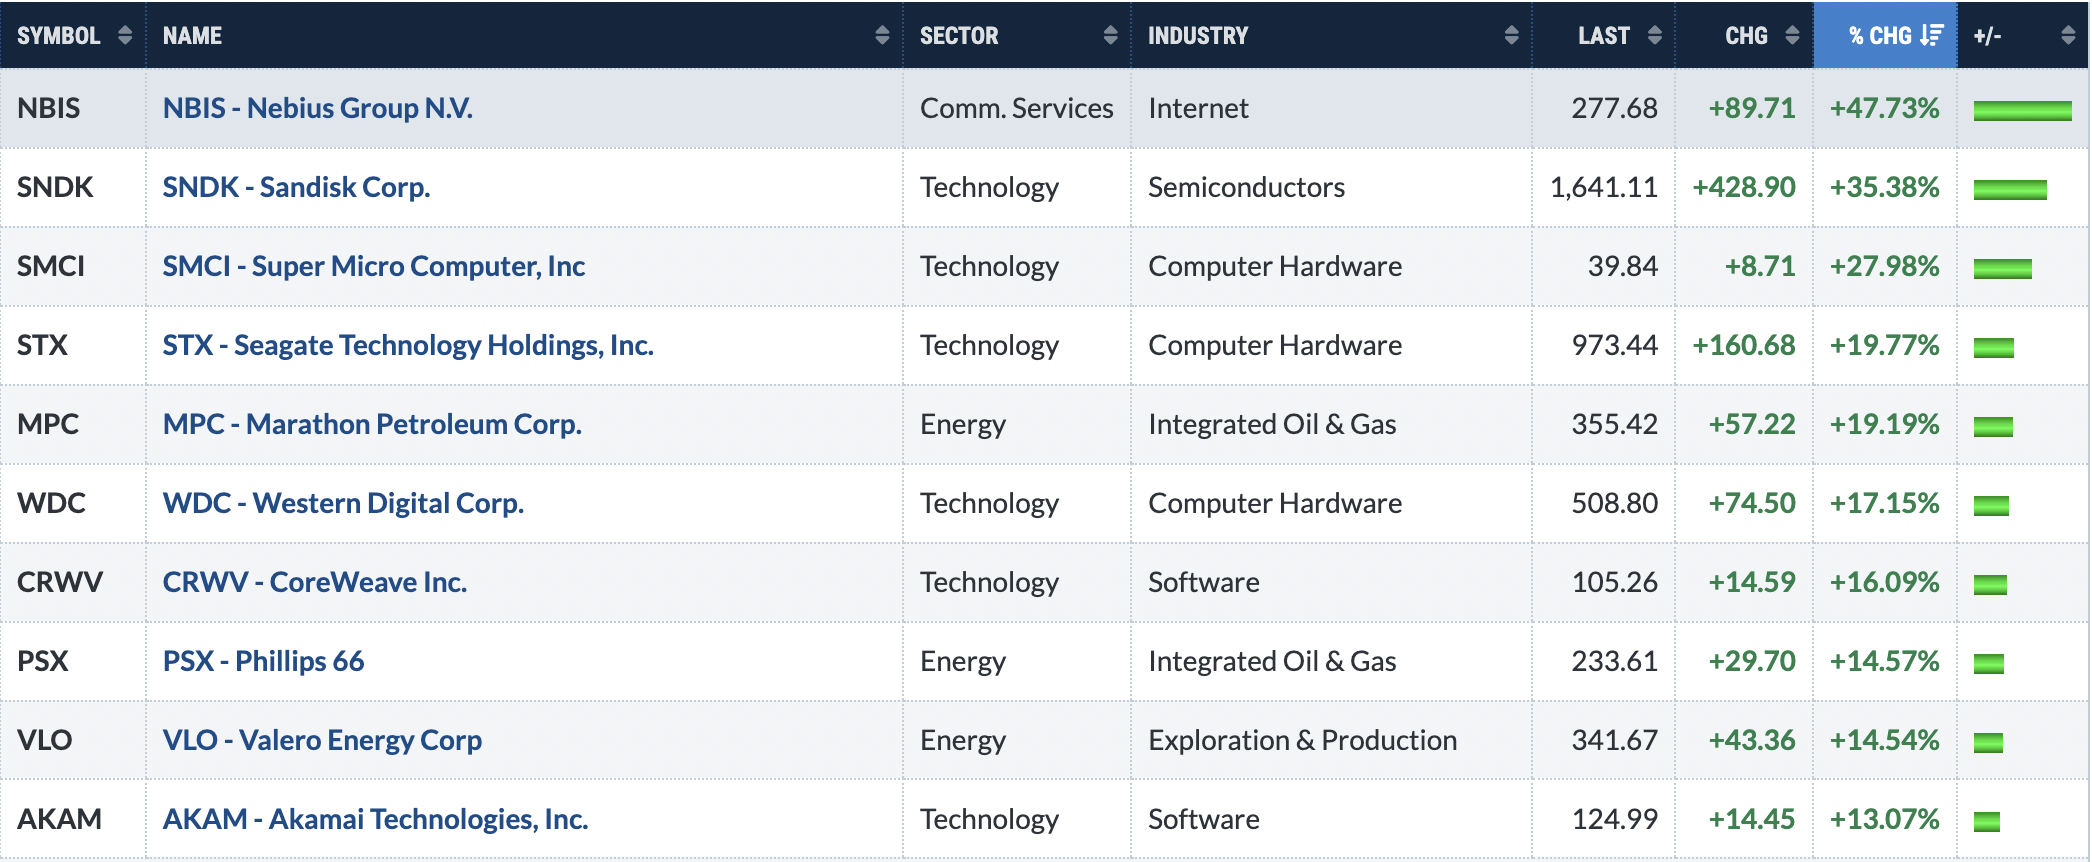
Top 10 Stocks - S&P 500/NASDAQ 100
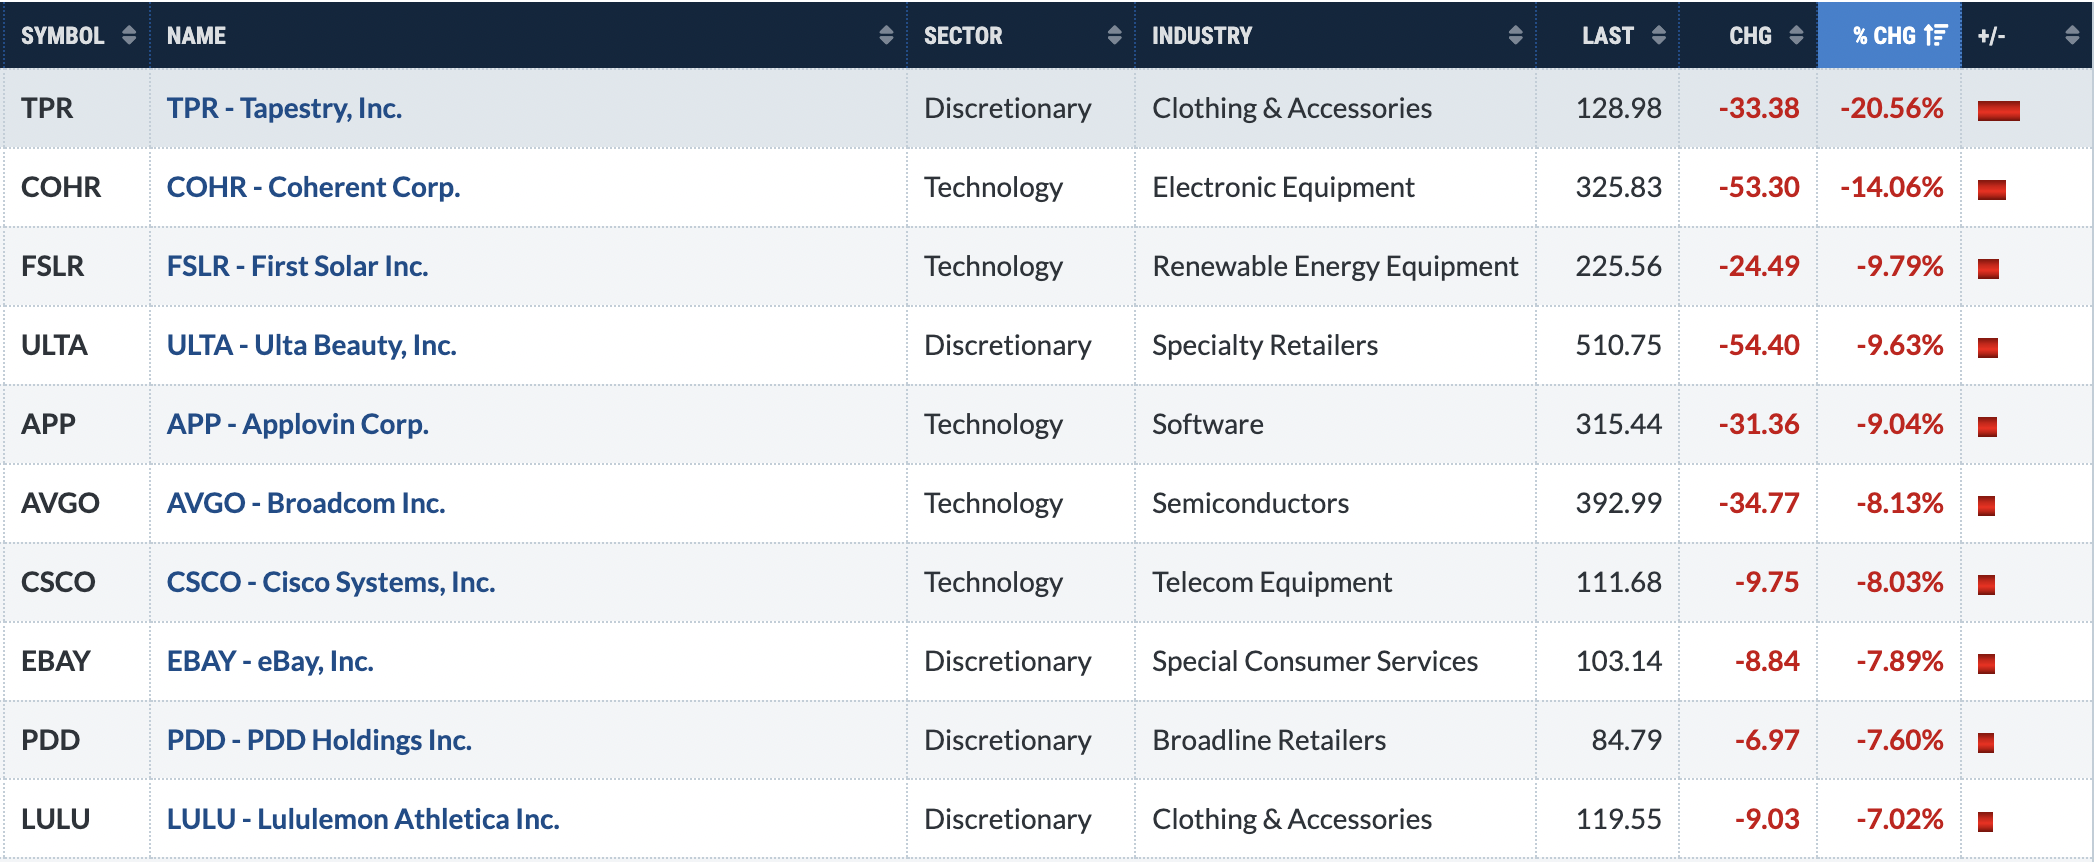
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
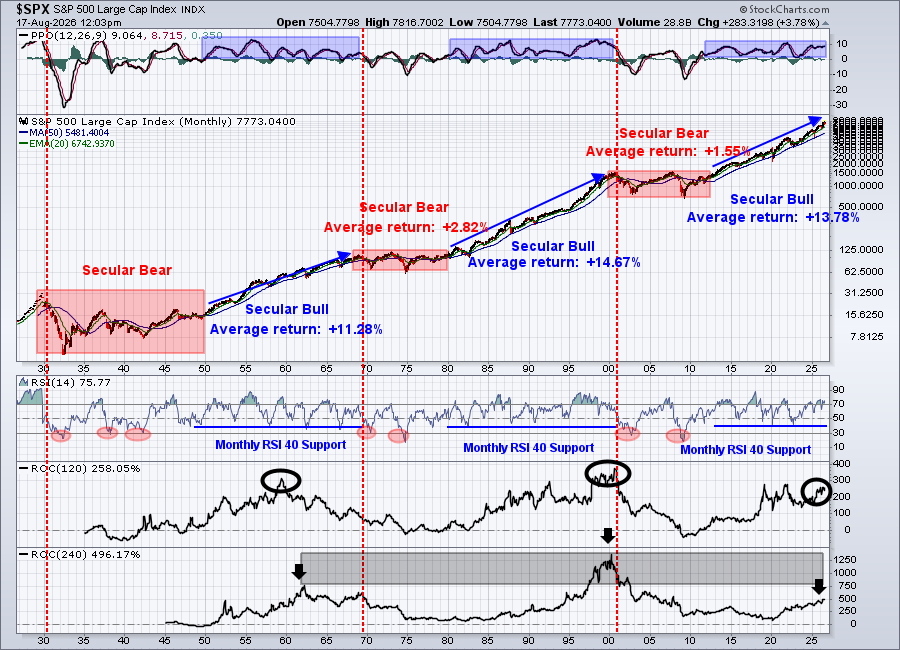
We saw new all-time highs last week on the S&P 500, continuing the long-term secular bull market that's currently in play. Long-term investors should stay the course.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
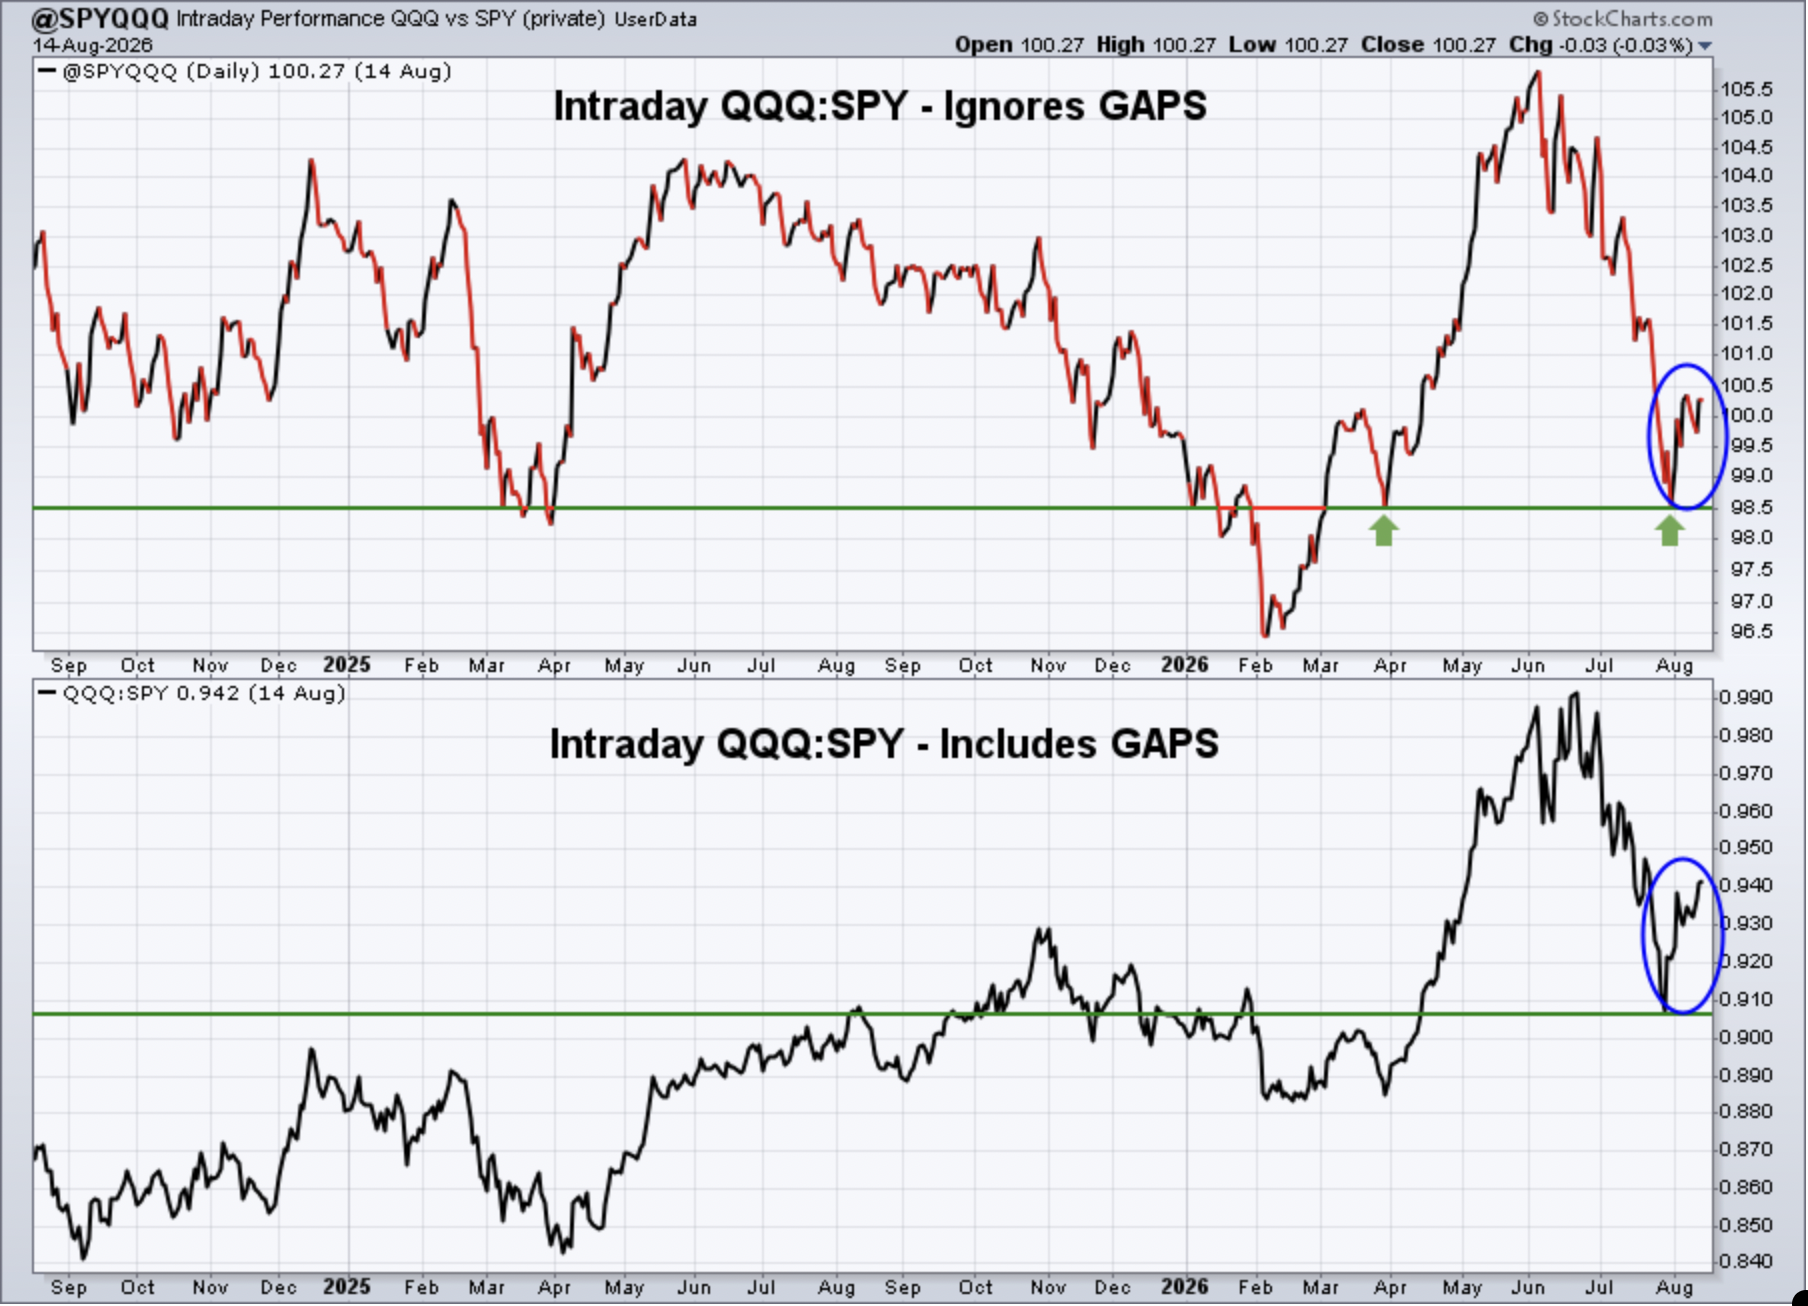
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
This ratio was mostly flat last week, not really providing any significant clues as to future market direction. In addition to lowering our expectations for the overall market indices, we probably should lower our expectations for our sustainability ratios as well. It would be fairly unusual for these ratios to go screaming higher in August and September. Normally, the stock market is a bit more defensive in late summer as volumes decline with vacations.
IWM:QQQ
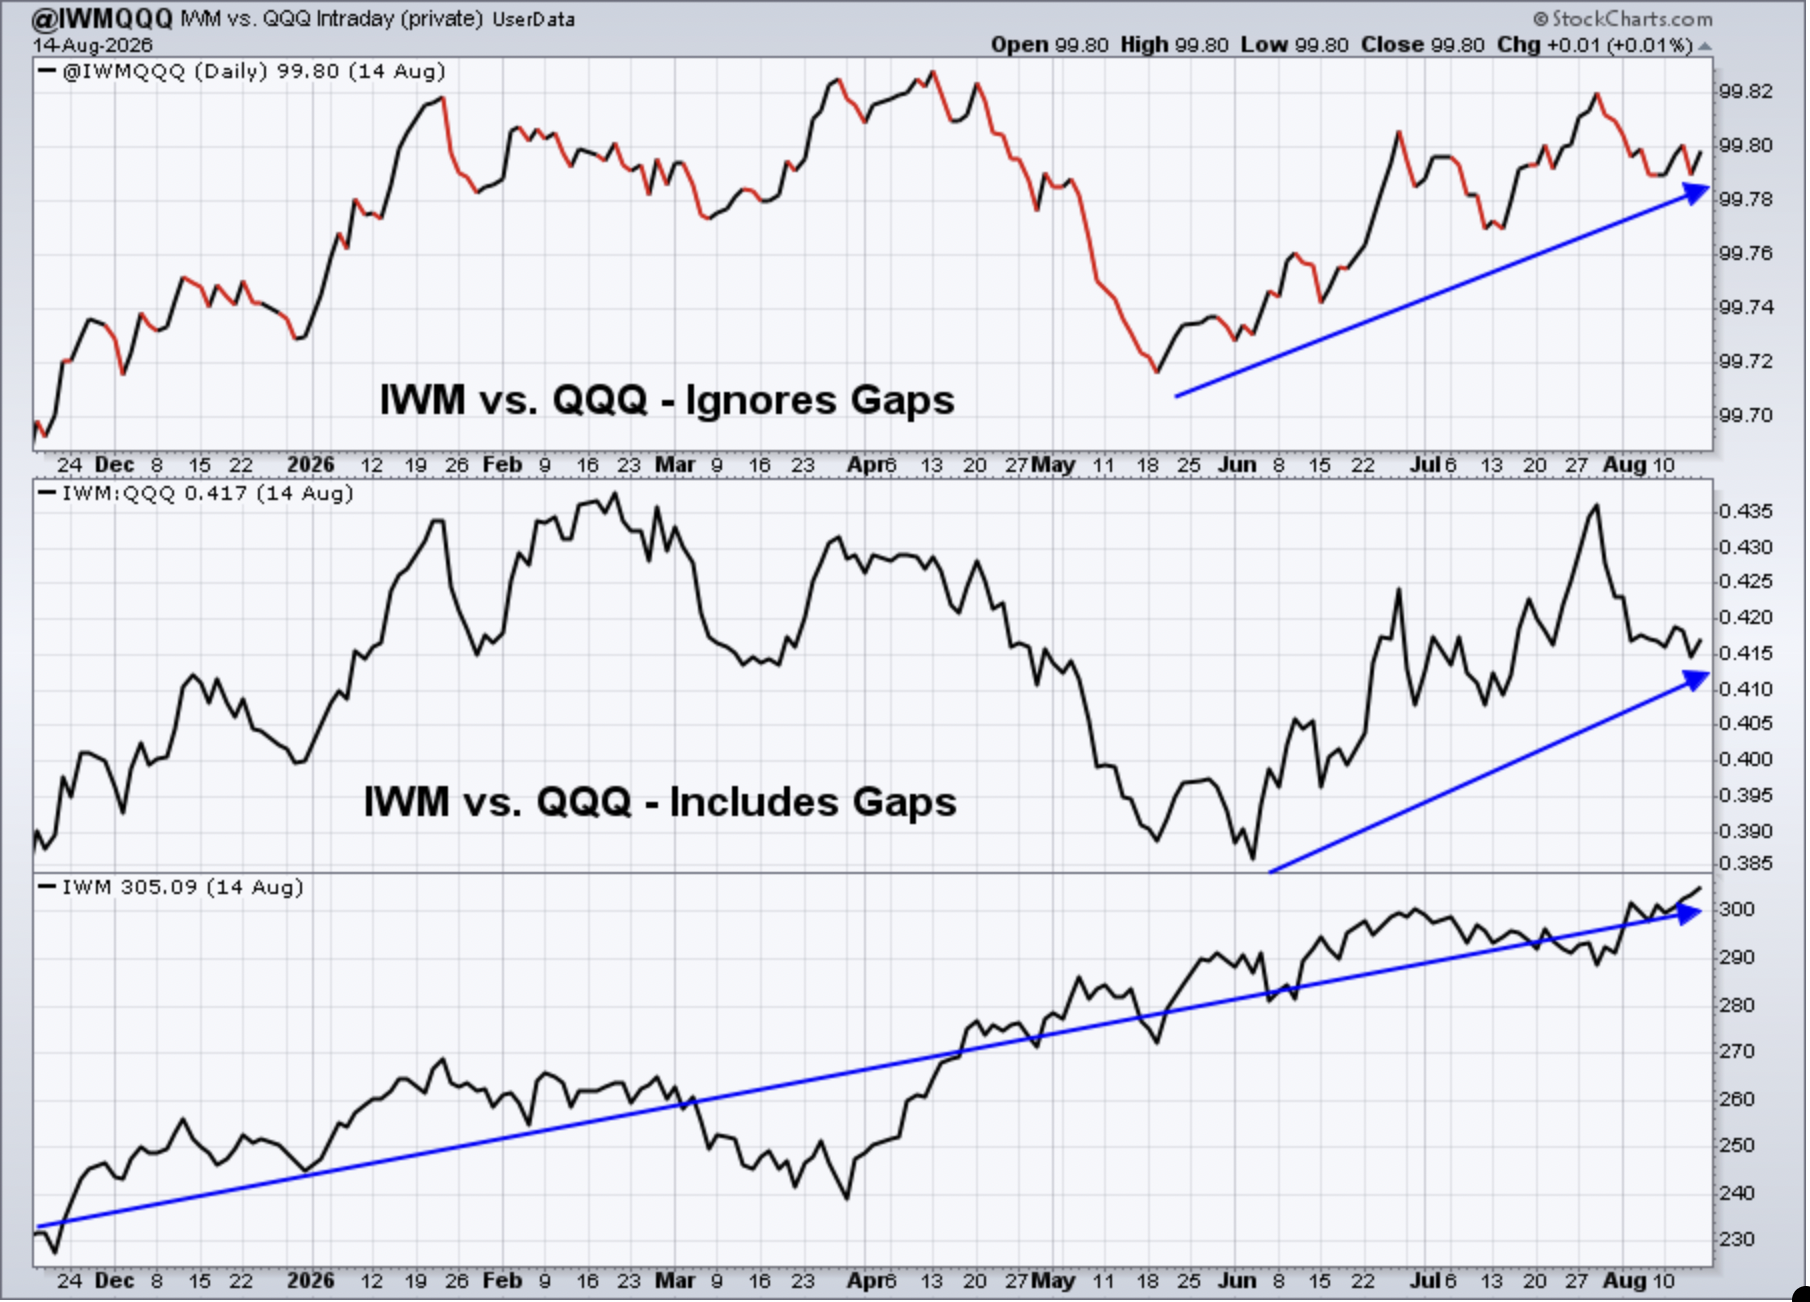
Small caps continue to perform well. I'd feel comfortable having them as part of my short-term or long-term trading/investing strategy right now. I still believe the interest rate environment over the next couple years will favor this asset class, even if we do have short-term interest rate "hiccups."
XLY:XLP
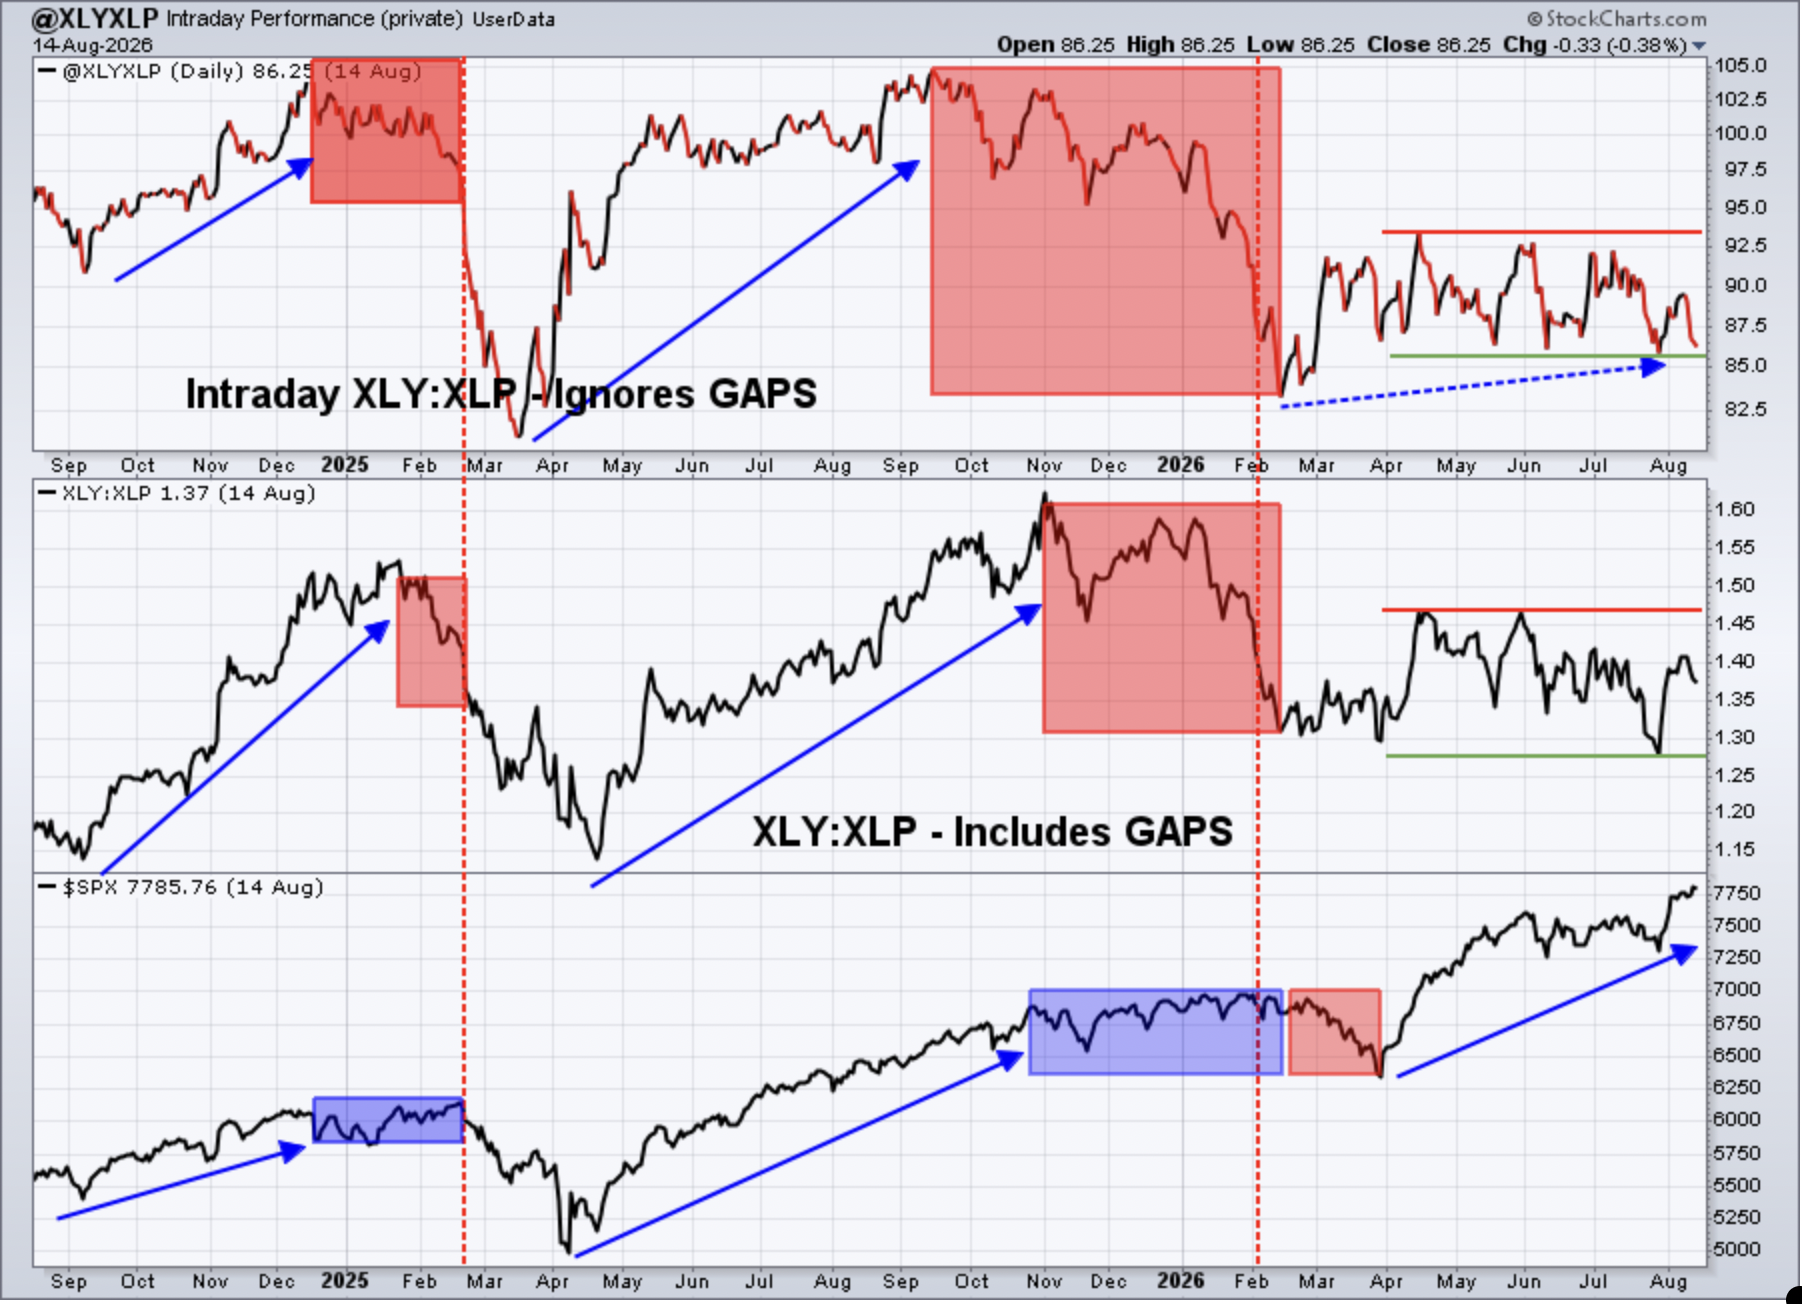
It was not a great week for this ratio. Wednesday was a particularly bad day as consumer discretionary stocks (XLY) were mostly moving down throughout the day, while consumer staples stocks (XLP) were moving higher. A couple more days like that and we could see a meaningful breakdown in this ratio - at least on an intraday basis (excluding gaps). While this is just one secondary signal, it is an important one to me. Consumer spending represents roughly two-thirds of GDP, so a poorly performing discretionary group can be an indication of economic weakness ahead. Therefore, we want to always keep a close eye on the group technically and how it trades on a relative basis to staples.
Sentiment
5-day SMA ($CPCE)
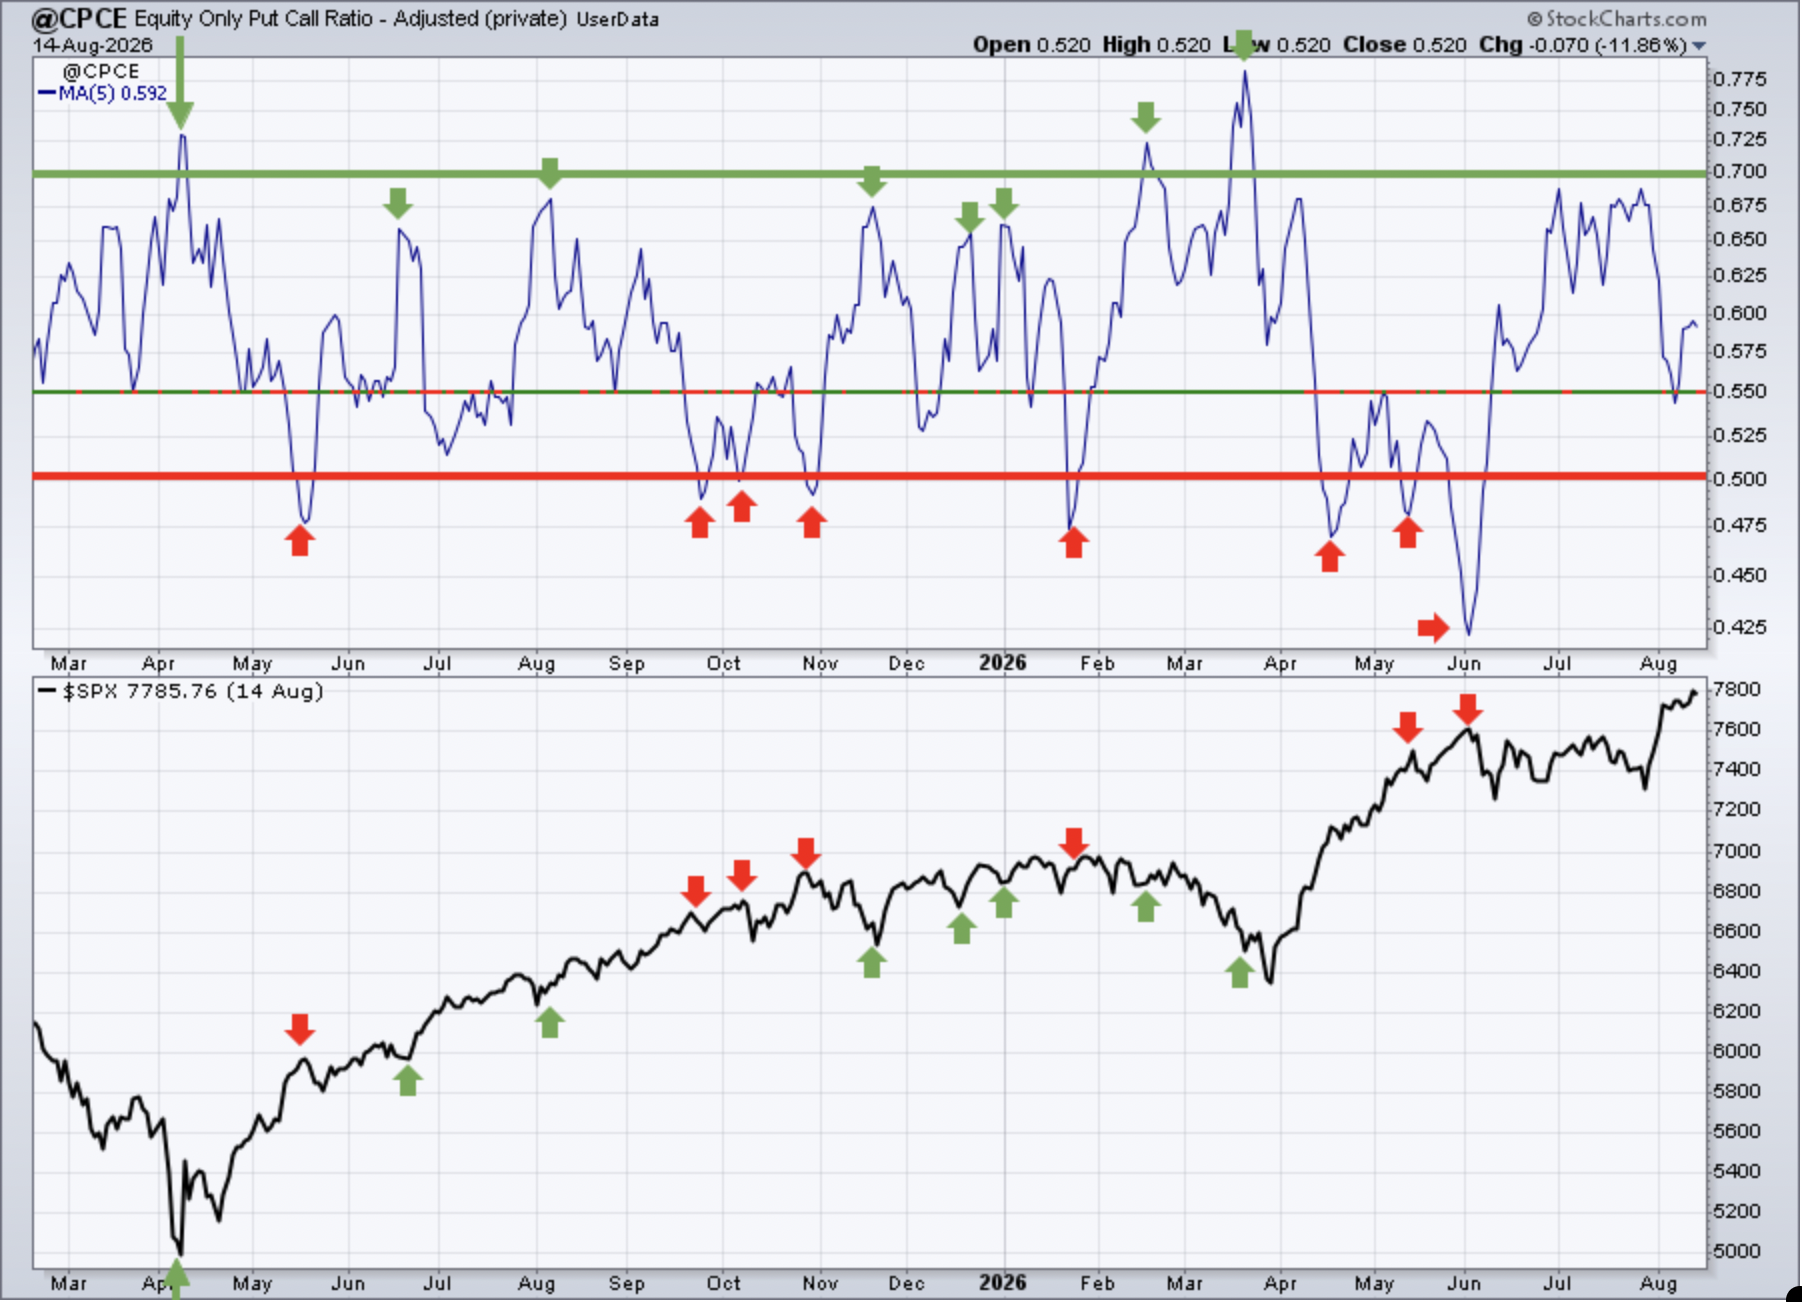
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
Last week, this 5-day SMA bounced as it neared what I consider to be a key level of complacency near 0.55. It's currently in neutral territory and isn't really providing us much of a short-term signal.
253-day SMA ($CPCE)
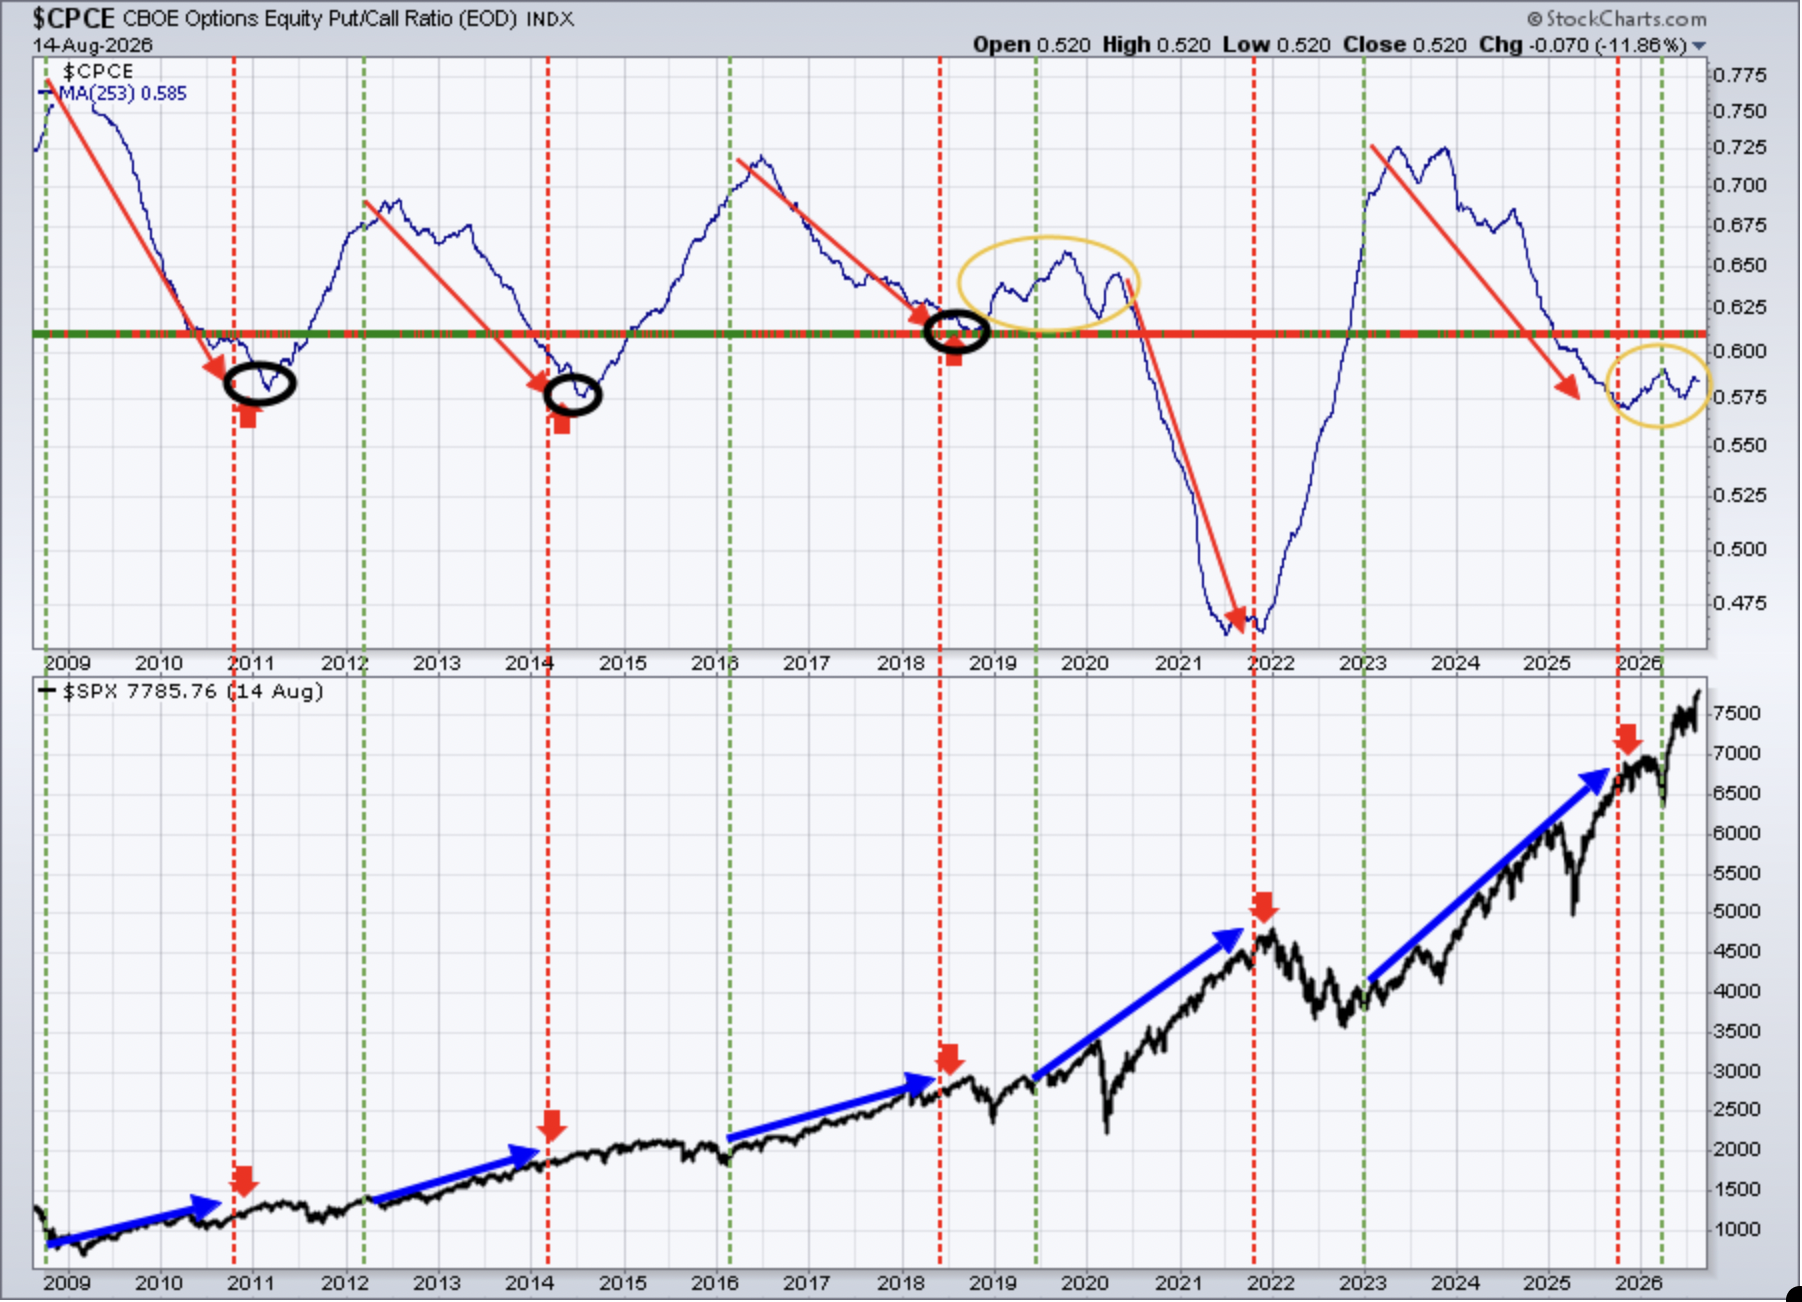
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500.
I'll be honest, I don't know what to think as I look at this chart. It looks very similar to 2019 into 2020 when the stock market couldn't decide which way it wanted to go. So I'm just watching it for now, not really trying to determine what signal it's sending. This 253-day SMA moves very, very slowly, so it'll take some patience. This is what I wrote last week and nothing has changed.
Long-Term Trade Setups
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month, and below is how I viewed each MONTHLY chart as of Friday, August 3rd:
- JPM - neg divergence suggests upside momentum could be slowing
- BA - 175-260 multi-year trading range, currently in the middle of it
- FFIV - overbought, but excellent long-term chart
- MA - 18-month consolidation; break above 600 would be very bullish
- GS - slowing momentum similar to JPM, has more than tripled in 2 1/2 years
- FDX - 265-275 should provide excellent support on any weakness
- AAPL - remains strong long-term, despite the short-term earnings setback
- CHRW - July selling sets up 20-month EMA test, a buy from here
- JBHT - slightly overbought on monthly chart, but quite bullish
- STX - monthly RSI falling from mid-90s (!!!); short-term vulnerable
- HSY - consolidation from 2023 high continues, 140 is excellent support
- DIS - lengthy period of consolidation hopefully setting up breakout soon
- MSCI - very choppy with current trading range 540-640
- SBUX - long-term momentum accelerating, 113.64 is all-time high
- KRE - regional banks have been solid, but nearing overbought territory
- ED - long-term uptrend looks awesome, solid growth & dividend stock
- AJG - bottoming head & shoulders pattern argues for higher prices
- NSC - trending higher, though clearly not the best railroad stock in 2026
- RHI - trading above its 20-month EMA for the first time in 2026, improving
- ADM - challenged all-time high from 2022, could consolidate here for a bit
- BG - broke out earlier in 2026 and now backtesting breakout level, it's a buy
- CVS - remains in all-time high breakout mode, bullish
- HRL - recently cleared 20-week EMA, now battling 20-month EMA near 25
- DE - trending higher last 2 years, likely to continue that trend
- LULU - needs to hold recent low or potentially test support in 80-82 range
- TTD - this was added purely for growth and it's showing few signs of bottoming
- META - still struggling from negative divergence on monthly chart
- ADBE - clearing 285-290 would begin to suggest bottom is in
- KMB - nice recent rally with key resistance in 115-116 range
- ORCL - broke 2026 support and tested April 2025 low before reversing; interesting buy at this level
- ABBV - now has excellent support in mid-230s, bullish
- MCD - monthly RSI at 43 and monthly PPO near zero line typically buy signal
- MKC - 42-45 is support level to watch, expecting it to hold
- TSCO - monthly RSI near 30 says BUY, very oversold and yield now solid 3%
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: FN ($20 billion)
- Tuesday: HD ($341 billion), KEYS ($60 billion), BIDU ($36 billion)
- Wednesday: ADI ($186 billion), TJX ($170 billion), LOW ($122 billion), TGT ($71 billion)
- Thursday: WMT ($921 billion), BABA ($293 billion), DE ($165 billion), ROST ($79 billion)
- Friday: BEKE ($19 billion)
Key Economic Reports
- Monday: August empire state manufacturing survey, August NAHB housing market index
- Tuesday: July housing starts & building permits, July industrial production & capacity utilization, July pending home sales
- Wednesday: FOMC minutes
- Thursday: Initial jobless claims, July leading indicators
- Friday: None
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Aug 17: +48.47% (Ex: cumulative gains =
+10.35% over 54 trading days since 1950. +10.35% x 253/54 = +48.47%) - Aug 18: -40.46%
- Aug 19: -46.99%
- Aug 20: +52.91%
- Aug 21: -10.18%
- Aug 22: +1.09%
- Aug 23: +14.15%
- Aug 24: +3.37%
- Aug 25: -22.28%
- Aug 26: -1.75%
- Aug 27: -1.57%
- Aug 28: -7.53%
- Aug 29: +28.52%
- Aug 30: -22.73%
NASDAQ (since 1971)
- Aug 17: +22.01%
- Aug 18: -7.31%
- Aug 19: -80.72%
- Aug 20: +24.20%
- Aug 21: -13.88%
- Aug 22: +30.93%
- Aug 23: +11.22%
- Aug 24: +11.28%
- Aug 25: +25.58%
- Aug 26: +27.04%
- Aug 27: +13.91%
- Aug 28: -16.97%
- Aug 29: +66.05%
- Aug 30: -34.86%
Russell 2000 (since 1987)
- Aug 17: -18.35%
- Aug 18: +5.90%
- Aug 19: -80.03%
- Aug 20: +15.80%
- Aug 21: +2.60%
- Aug 22: +11.57%
- Aug 23: -21.80%
- Aug 24: +32.69%
- Aug 25: +5.58%
- Aug 26: +2.36%
- Aug 27: +31.06%
- Aug 28: +14.19%
- Aug 29: +152.41%
- Aug 30: -69.37%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
It's great to see all-time highs continue to print, especially after two encouraging inflation reports last week. From a sector leadership perspective, however, there are only two sectors outperforming the S&P 500 - technology (XLK) and energy (XLE). I feel that energy's relative strength isn't as reliable, because it's dependent on the continuation of Middle East tensions, in my opinion. Maybe I'm wrong and I'm open to that possibility. However, the XLE does struggle during weeks where crude oil prices decline and that's been the long-term correlation as well.
Meanwhile, semiconductors (SOXX) are heating up again. I mentioned this in last Wednesday's Live Trading Room, indicating that the group was regaining strength technically. Over the past week, semiconductor stocks like SNDK (+46%), AEHR (+30%), COHU (+28%), MXL (+27%), AXTI (+27%), and FORM (+24%) have all gained north of 20%.
Here's what I'll be thinking about this week:
Interest Rates. I believe the biggest short-term threat to U.S. stocks remains the rise in the 10-year treasury yield ($TNX). It's been on the rise again since midday on Thursday, moving from 4.61% then to 4.71% at last check. Keep in mind that the TNX dropped last week on Wednesday and Thursday, after the July CPI and July PPI reports were mostly benign. Temporarily, that may have satisfied traders, but the movement higher again, I believe, recognizes that Fed Chief Warsh still may hike rates in September to MAKE SURE inflation isn't a problem.
The Economy. July jobs came in weak earlier this month and the discretionary sector remains particularly weak. That's concerning. I'm certainly not in panic mode, but it makes feel a bit more queasy about this rally when discretionary stocks are out of favor on a relative basis. On an absolute basis, the XLY is testing its August 4th low right now.
Seasonality. I keep reminding myself this is August. September has a propensity for driving the S&P 500 lower - unlike any other month. We've seen the S&P 500 drop 41 times in September since 1950, only rallying 34 times. That's a 45% chance over the past 75 years. The odds in September do NOT favor the bulls. Meanwhile, the odds of the S&P 500 rallying in ANY other month is just over 62%. I am open to the possibility that higher interest rates could spook the market temporarily, causing some short-term pain. The odds are not strong enough to sell as a long-term investor, but short-term traders need to remain on their toes.
Happy trading!
Tom