
EB Weekly Market Report -Monday, October 26, 2026
Model ETF Portfolio Draft
Our Model ETF Portfolio ended at last Monday's close and we announced in one of last week's Daily Market Reports that we would be selecting our next Model ETF Portfolio after the close today. That event starts at 5:30pm ET. Room instructions will be sent out separately.
We decided to hold off until Tuesday's (tomorrow) close to enter our new Model ETFs as the Tuesday close marks the end of the most bearish historical week of the year, dating back to 1950 on the S&P 500.
ChartLists/Spreadsheets
The following ChartLists have been updated as of the Friday, October 23rd close, and have been posted to our website:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Strong AD (SADCL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL)
- Upcoming Earnings (EARN)
- Upcoming Earnings Relative Strength (EARNRS)
The Key Manipulation spreadsheet has been updated through Friday, October 23, 2026. You can now view and/or download this spreadsheet from our website.
Weekly Market Recap
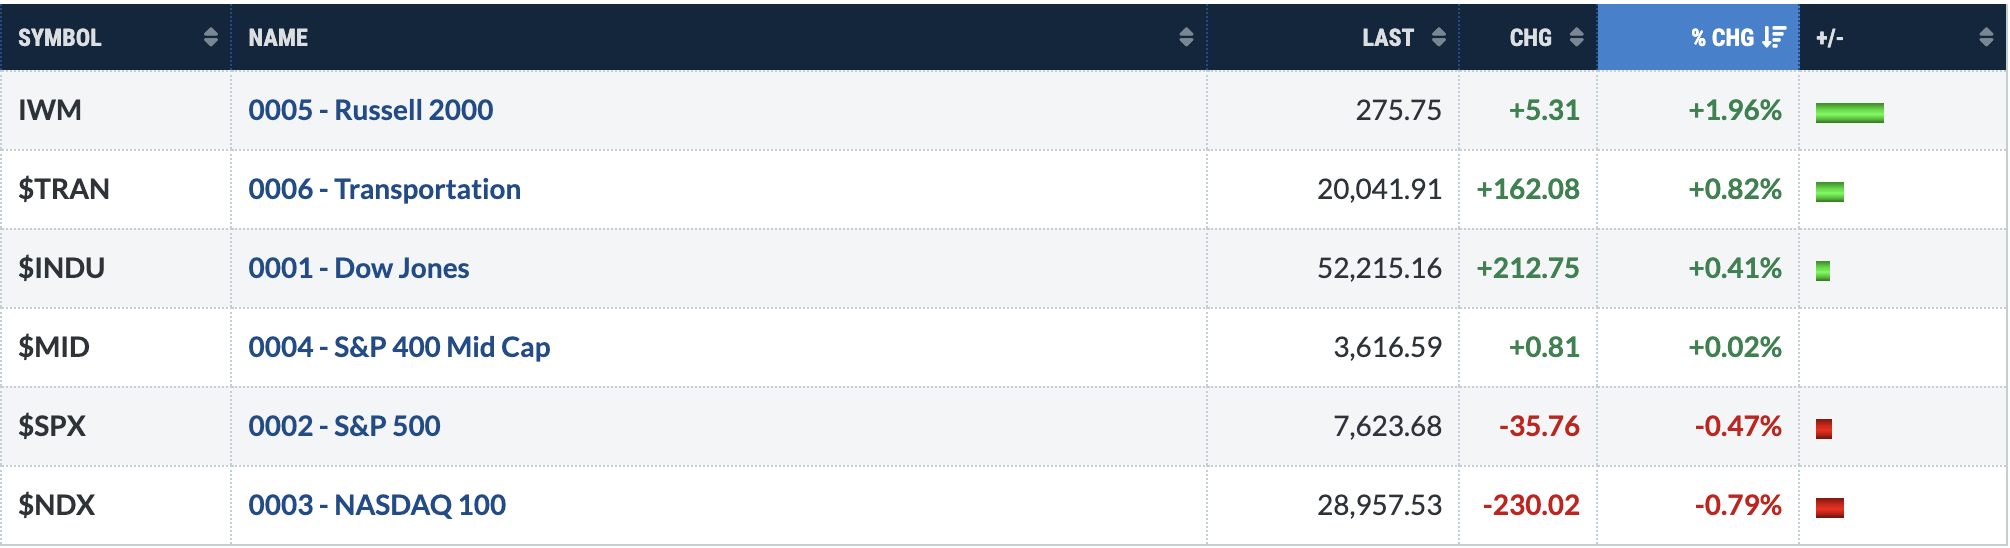
Major Indices
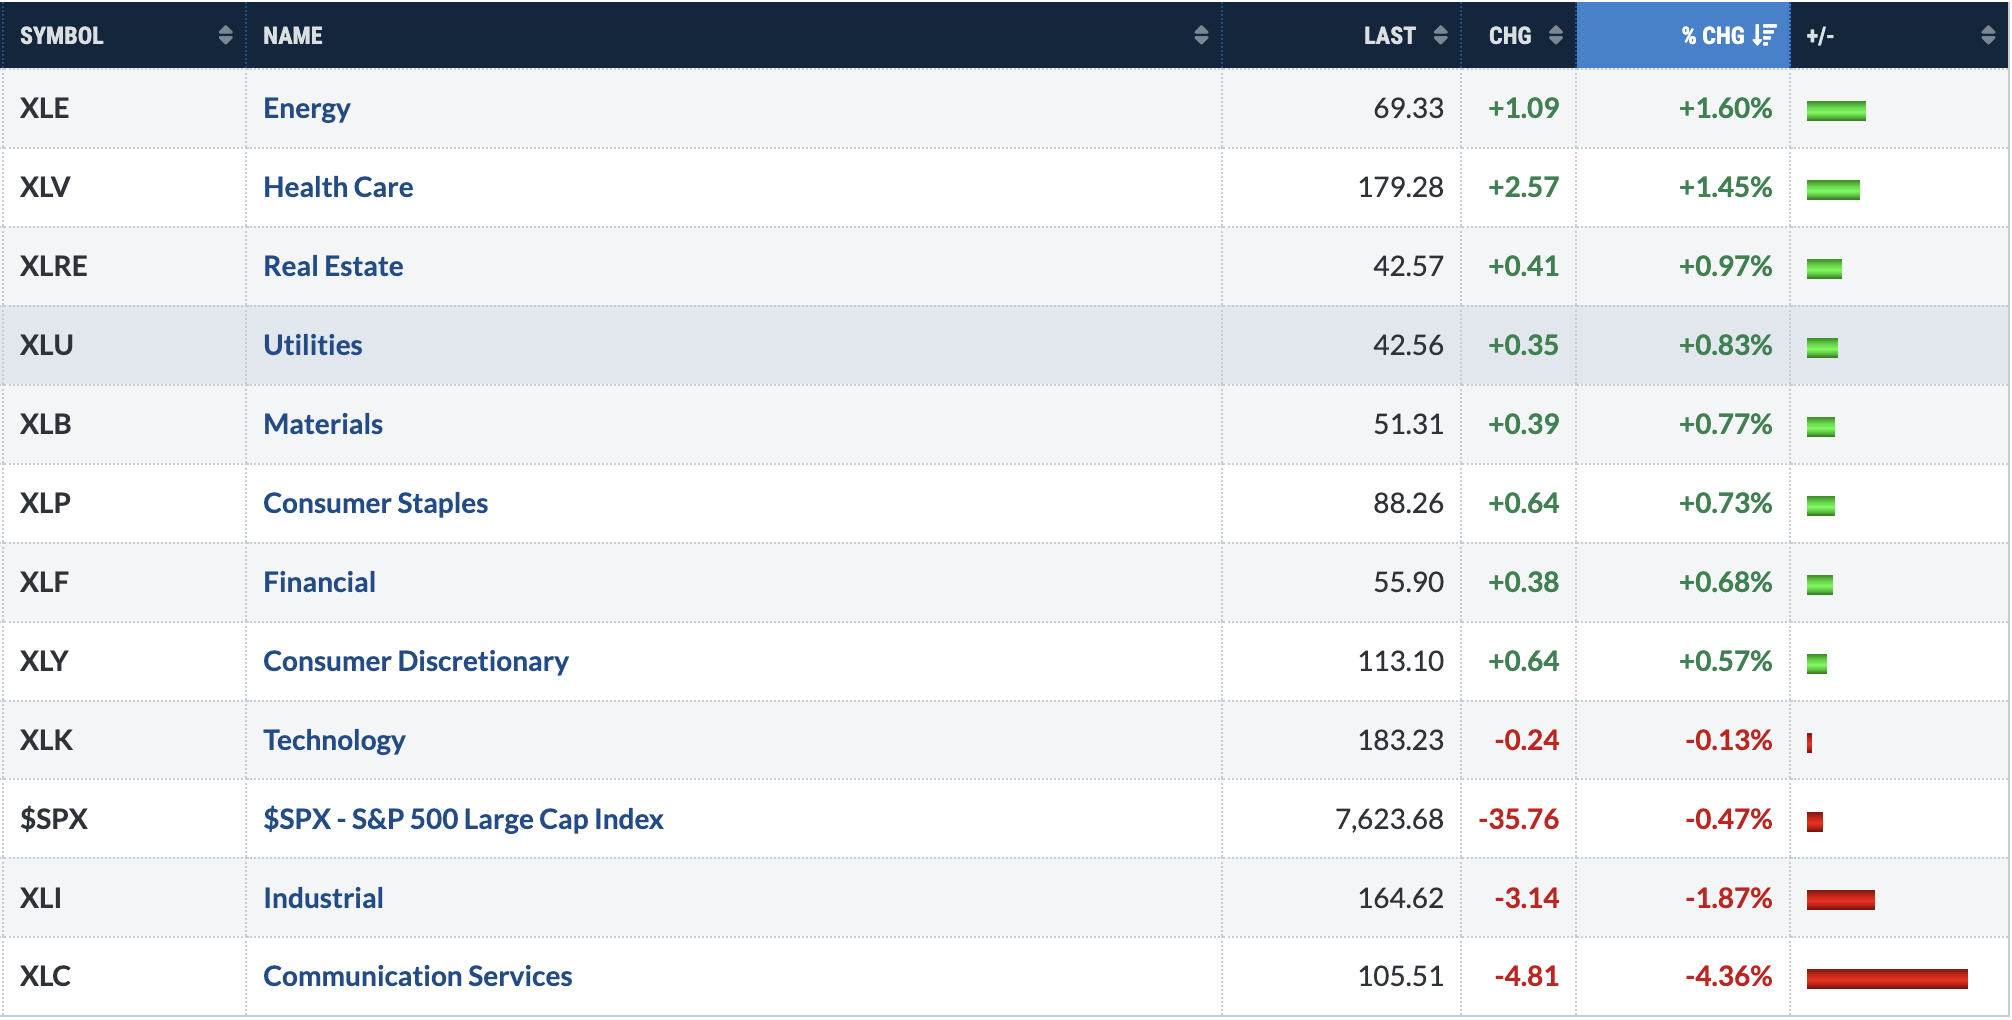
Sectors
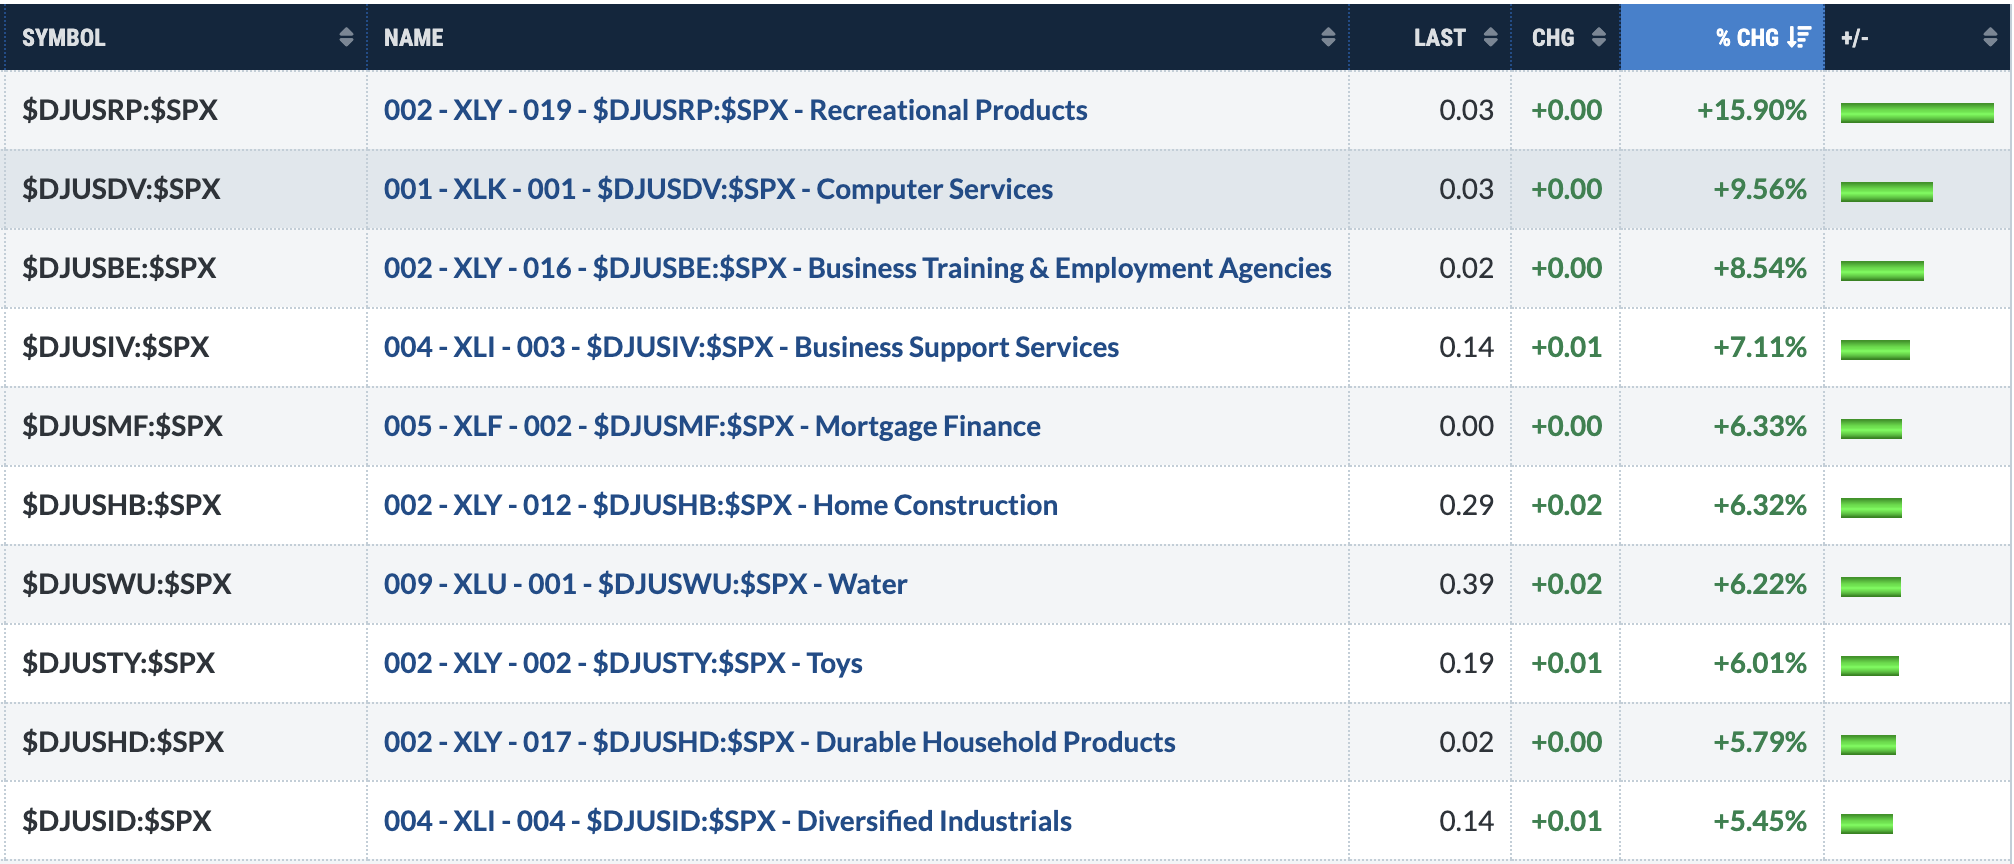
Top 10 Industries Last Week
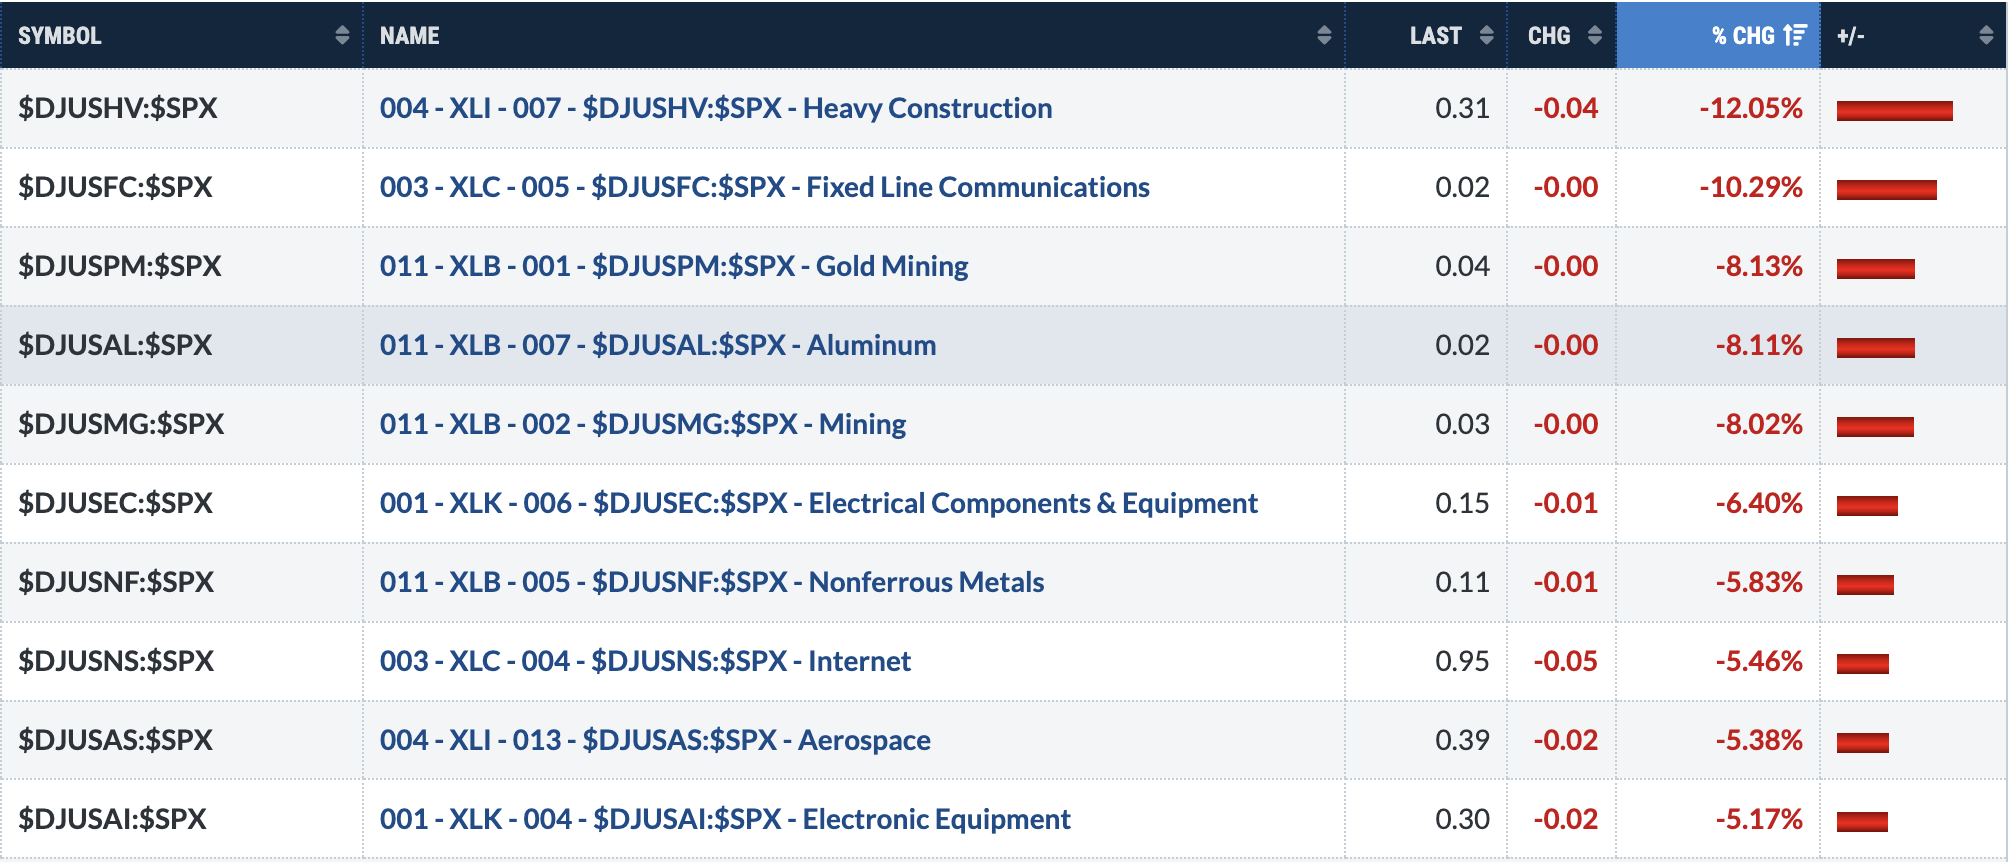
Bottom 10 Industries Last Week
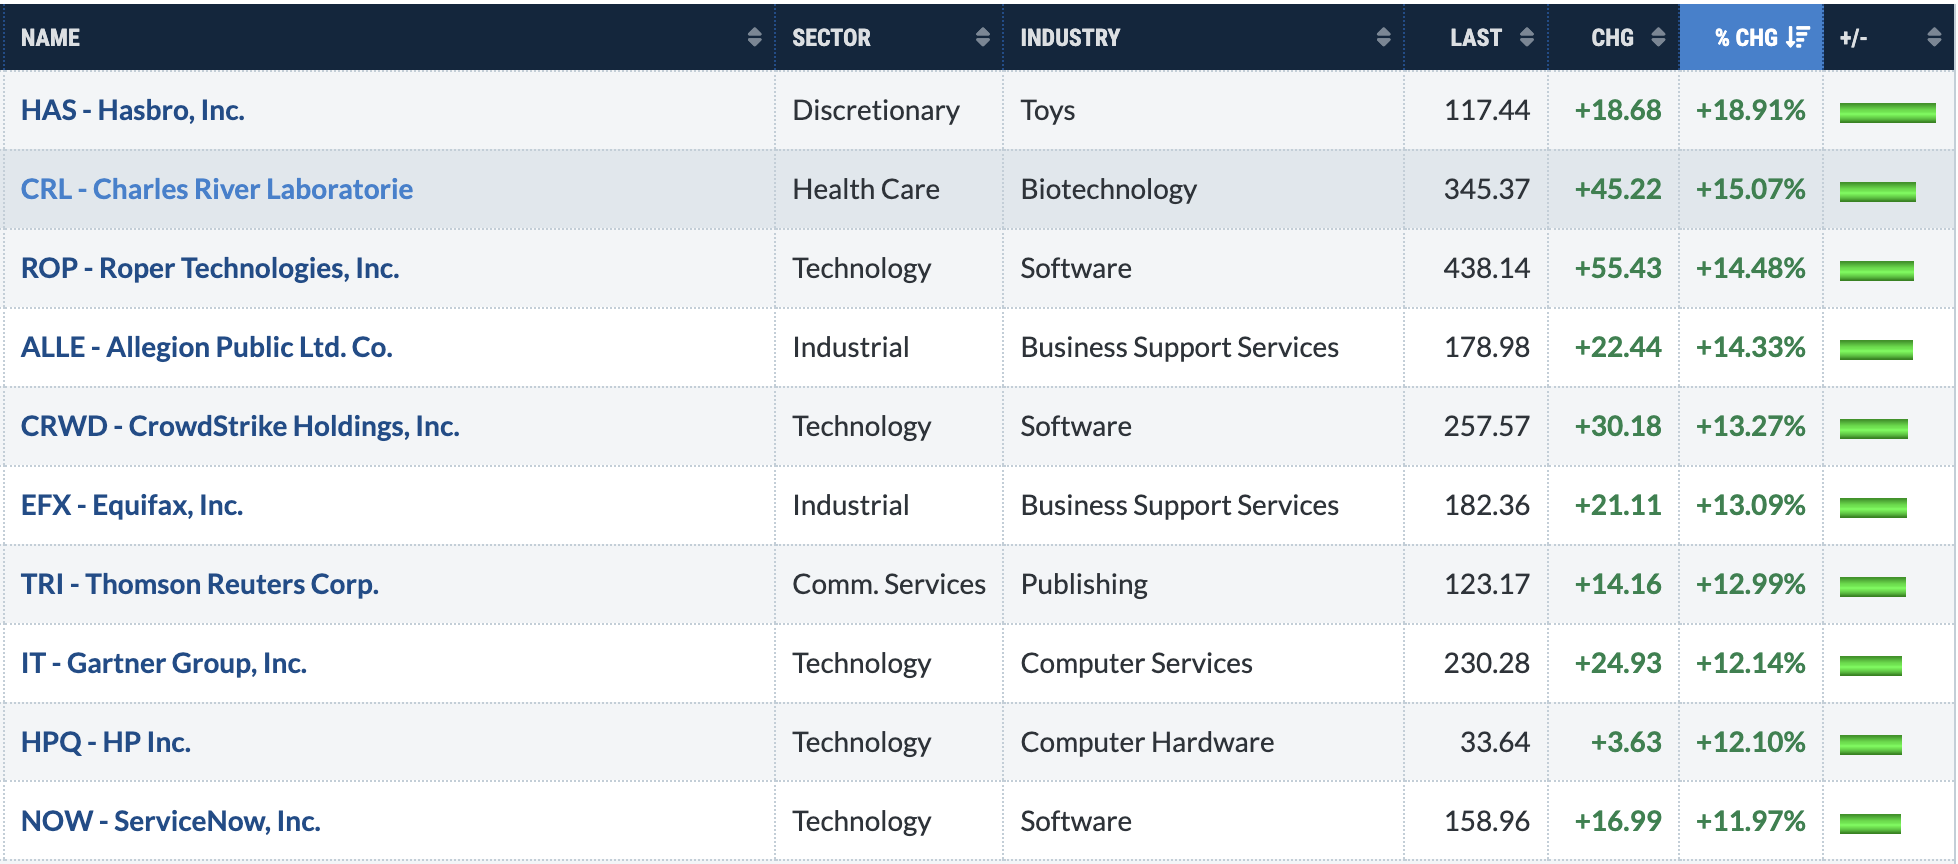
Top 10 Stocks - S&P 500/NASDAQ 100
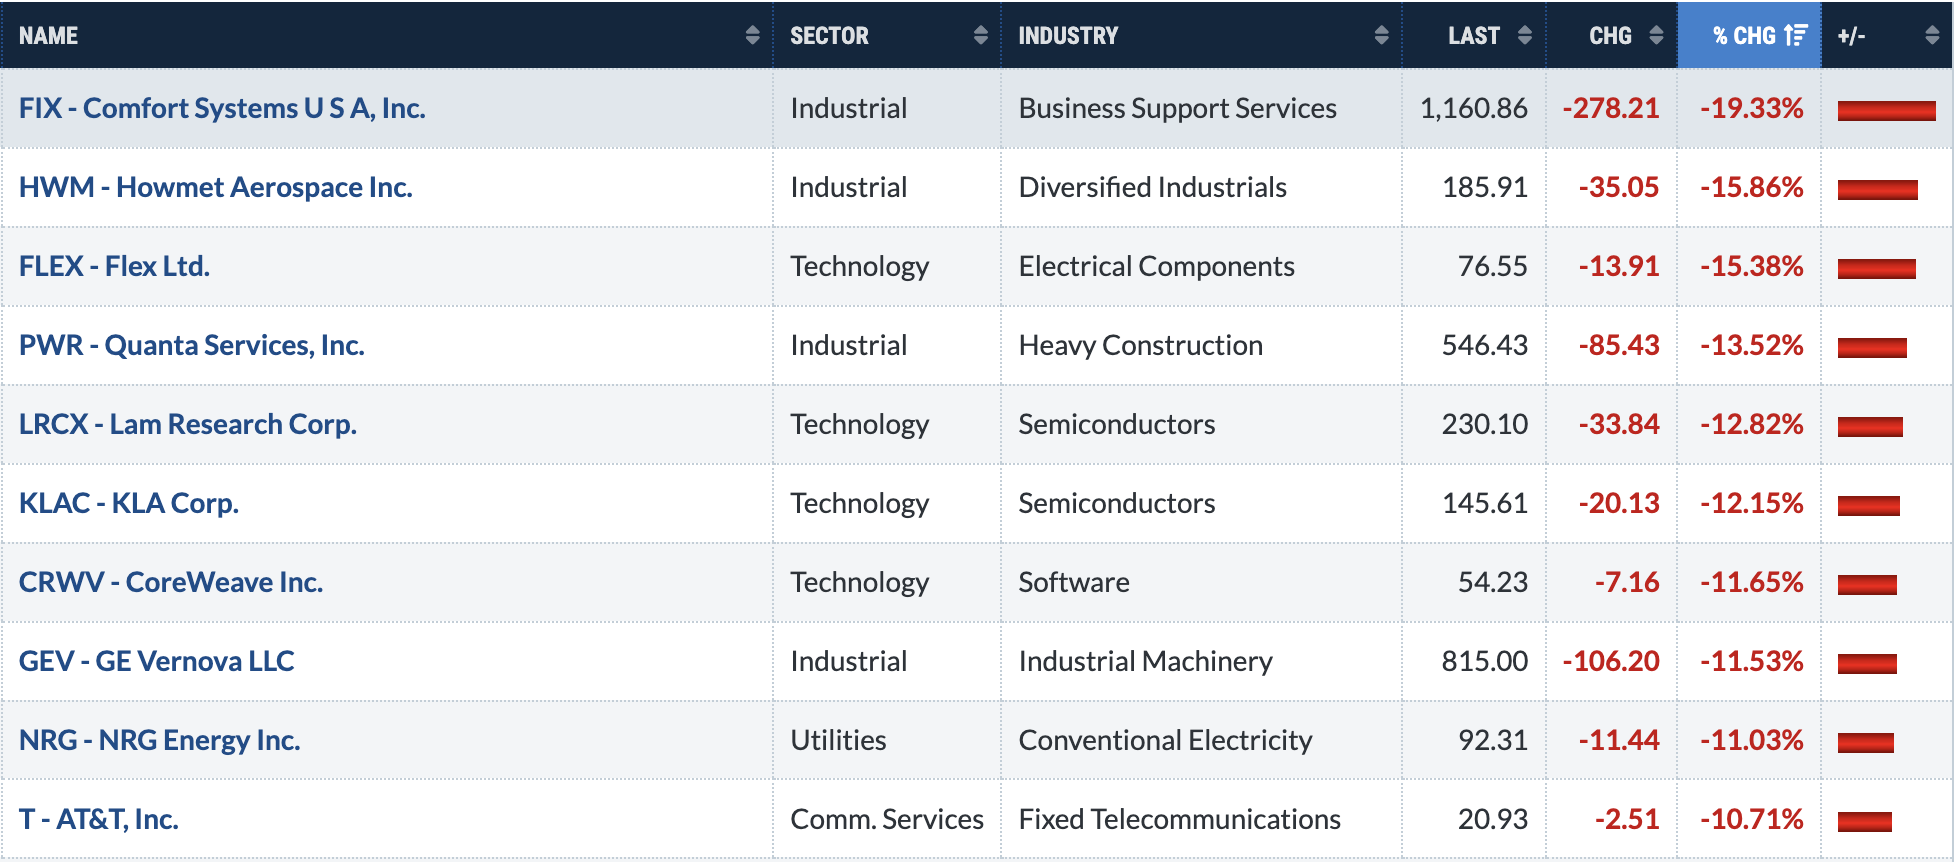
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
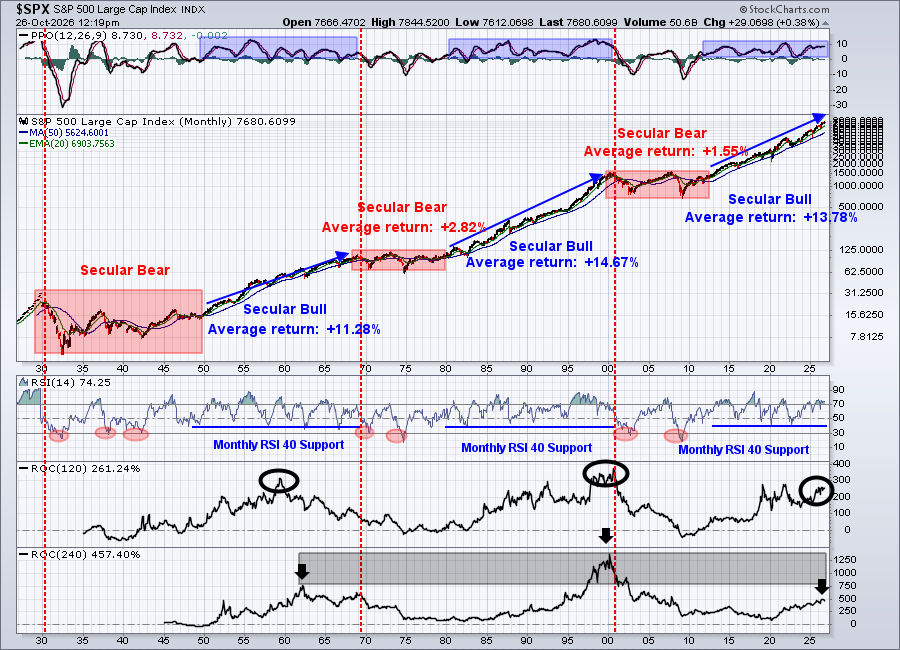
The recent decline in treasury yields certainly helped our major indices a bit last week, especially small caps and interest-rate-sensitive areas of the market. Still, this long-term chart really hasn't budged. The long-term secular bull market remains intact and, as we head into the most bullish time of the year historically, I'd remain 100% long from a long-term perspective.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
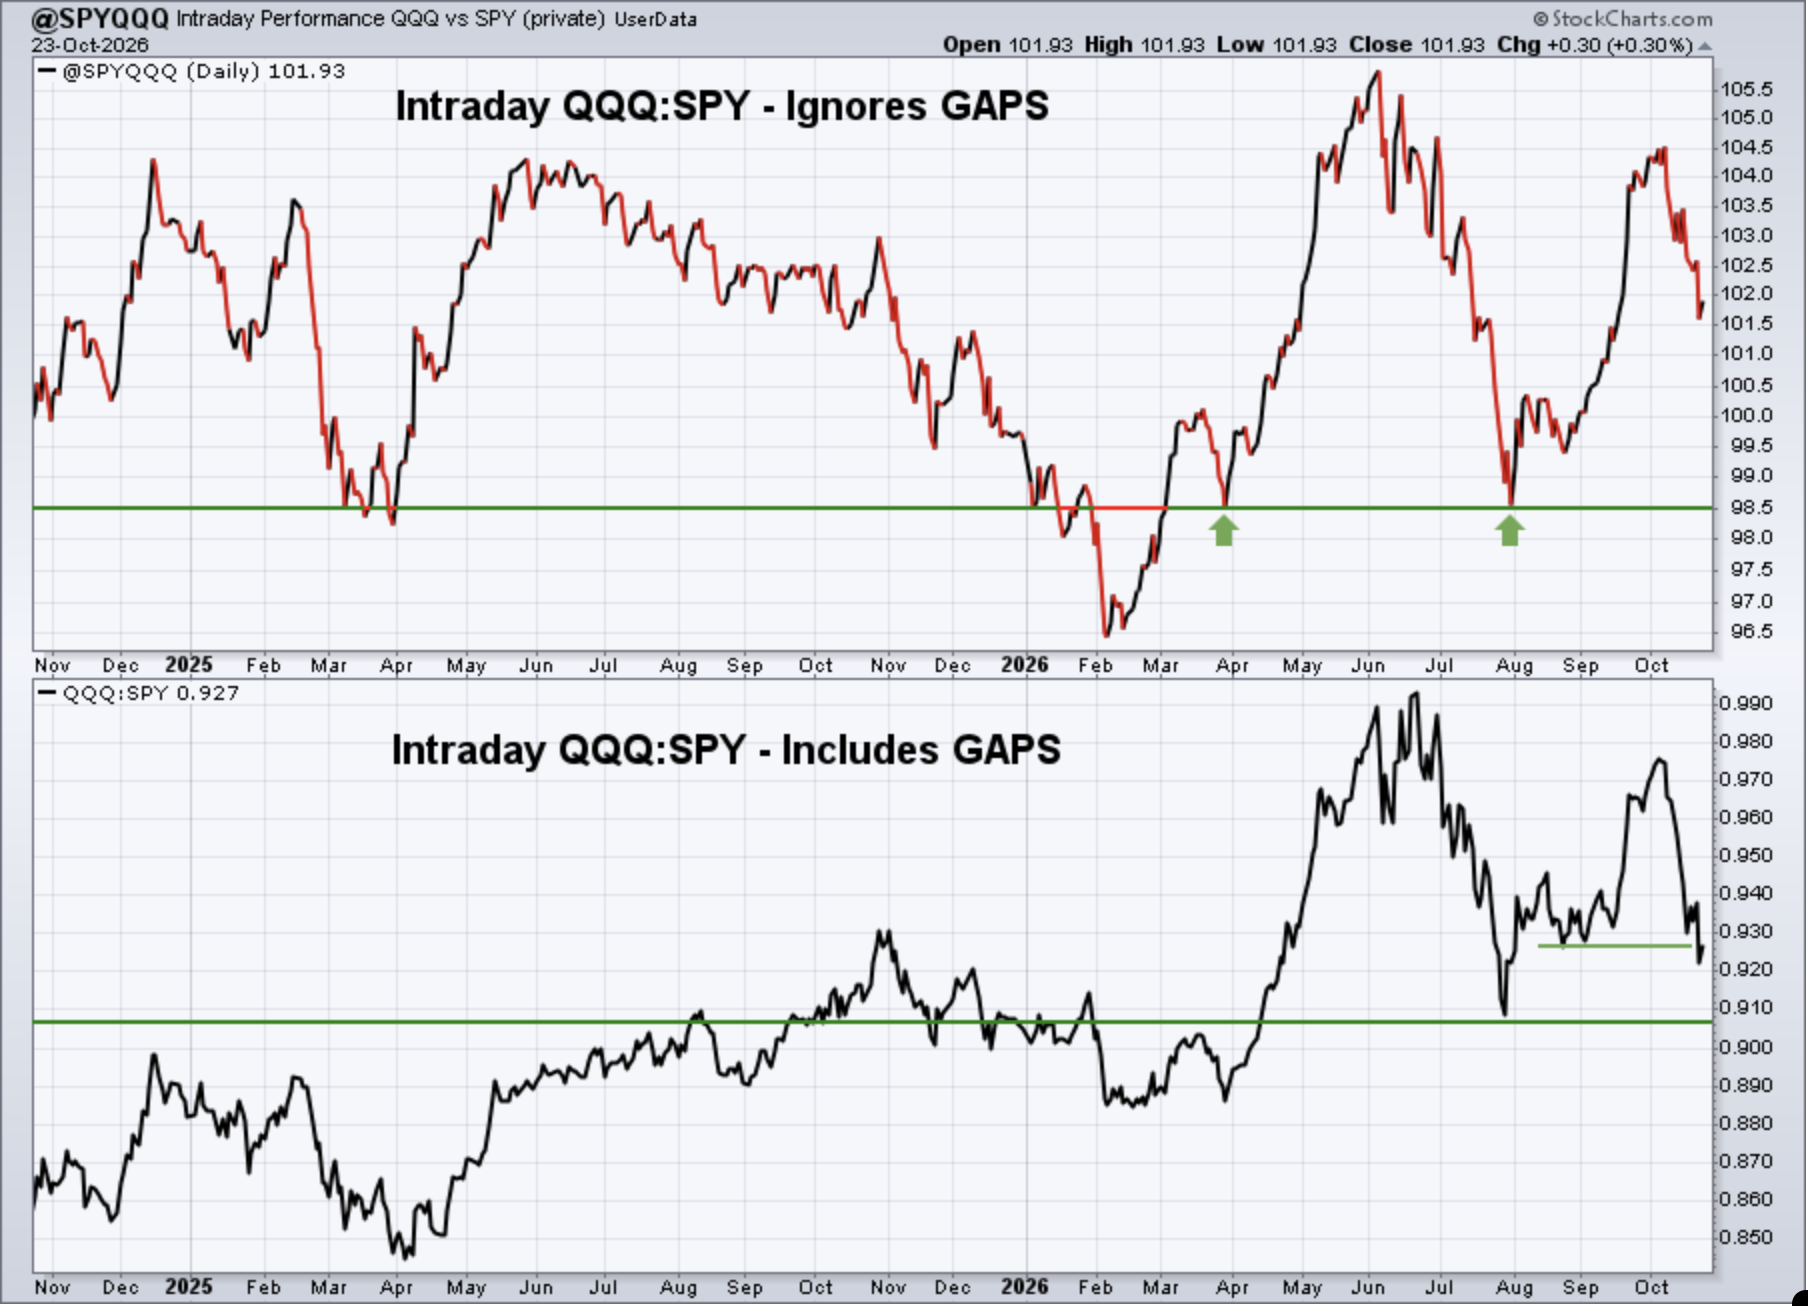
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
This chart shows the rotation accelerating towards value-oriented stocks, which isn't necessarily a bad thing. Remember, broad participation is always a good thing. I've pointed out several times that EVERY sector is in a long-term uptrend. Leadership is best coming from growth-oriented areas, because those companies can grow earnings the quickest, especially if the economy is strong or expected to strengthen. So when growth is doing well, we can make very bullish assumptions about the economy.
IWM:QQQ
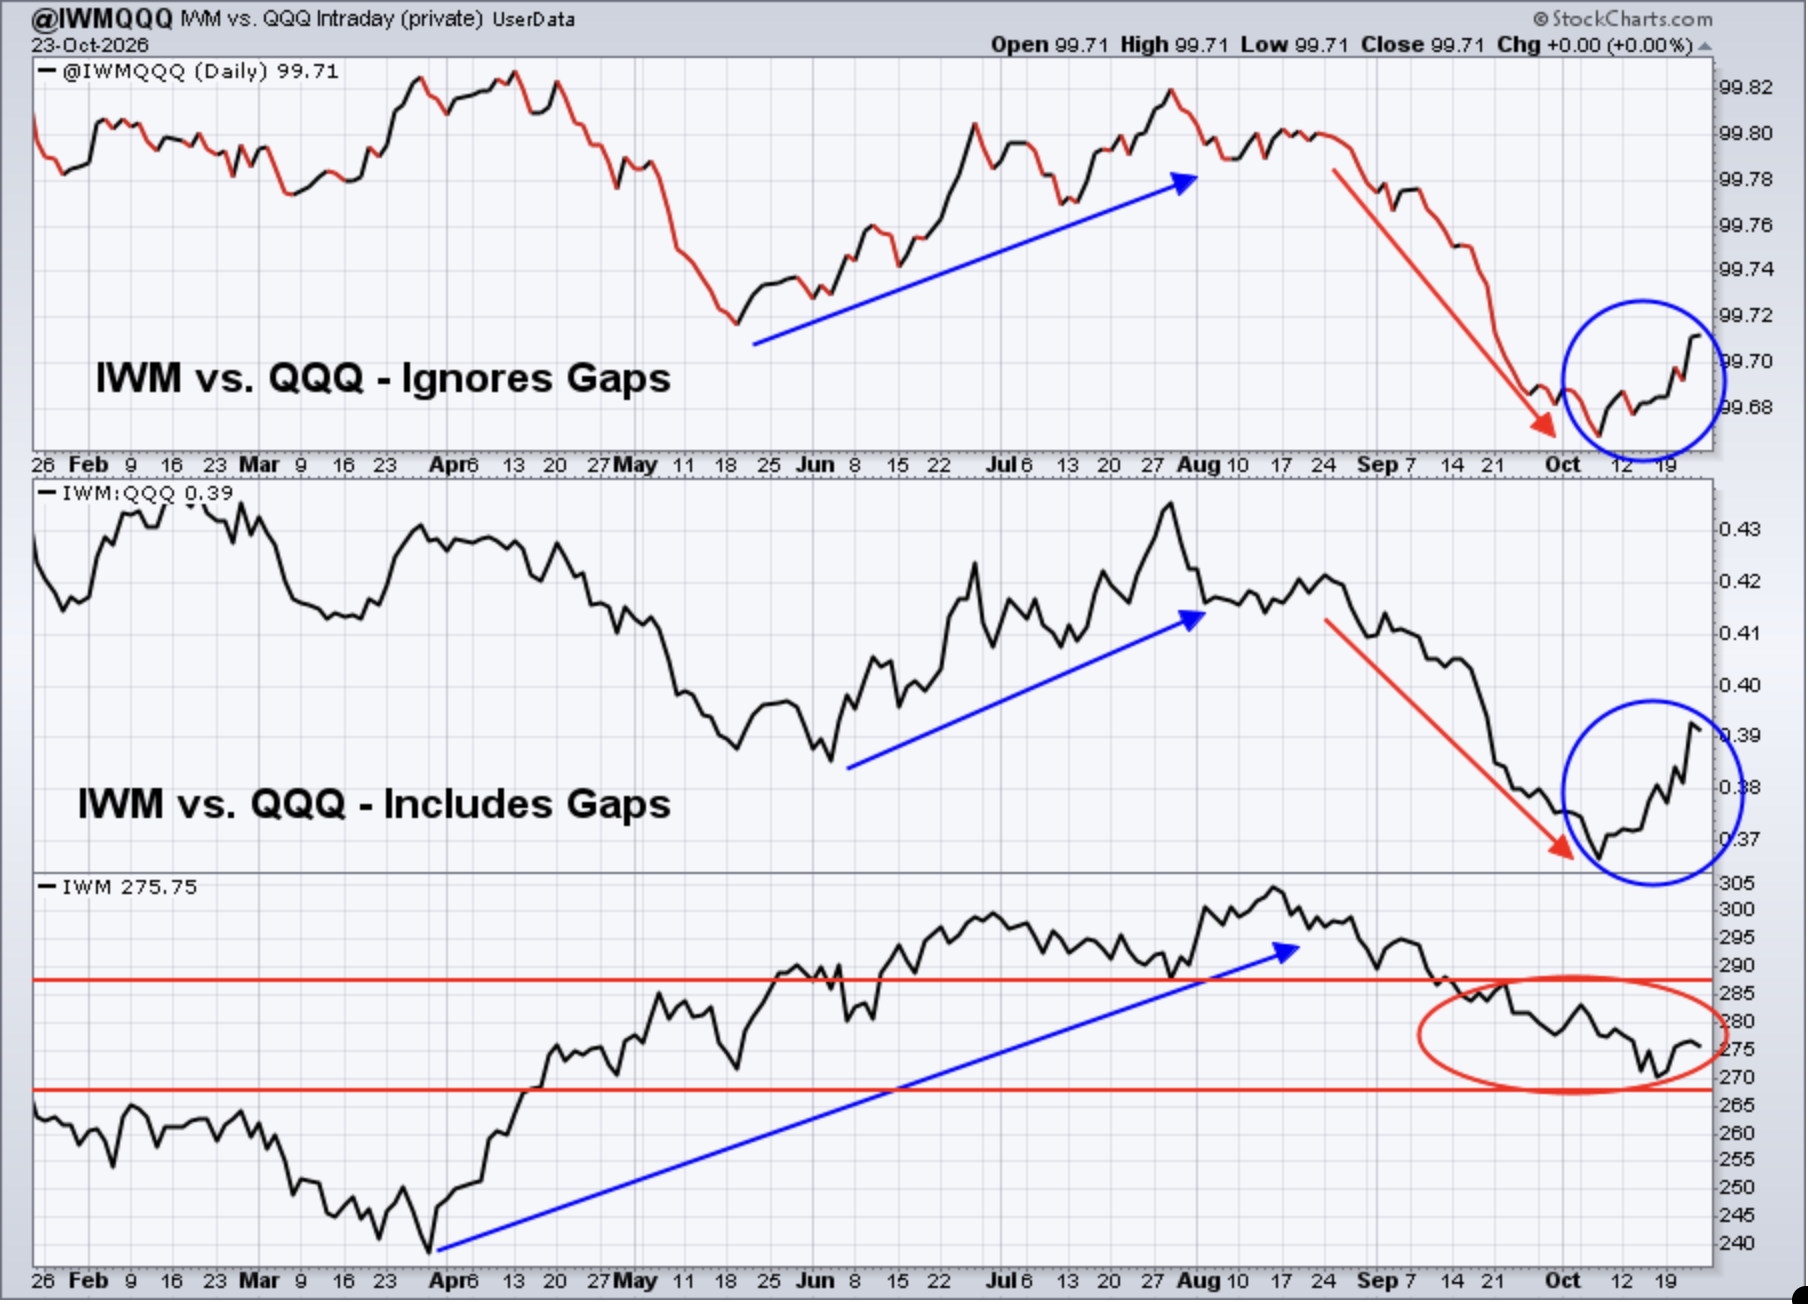
So far, everything is tracking right on cue with the IWM. It hit support near 270 and, not only has been bouncing, but has also been showing significant relative strength vs. the other major indices. That's bullish for now and the chart above is your visual to see that rotation.
XLY:XLP
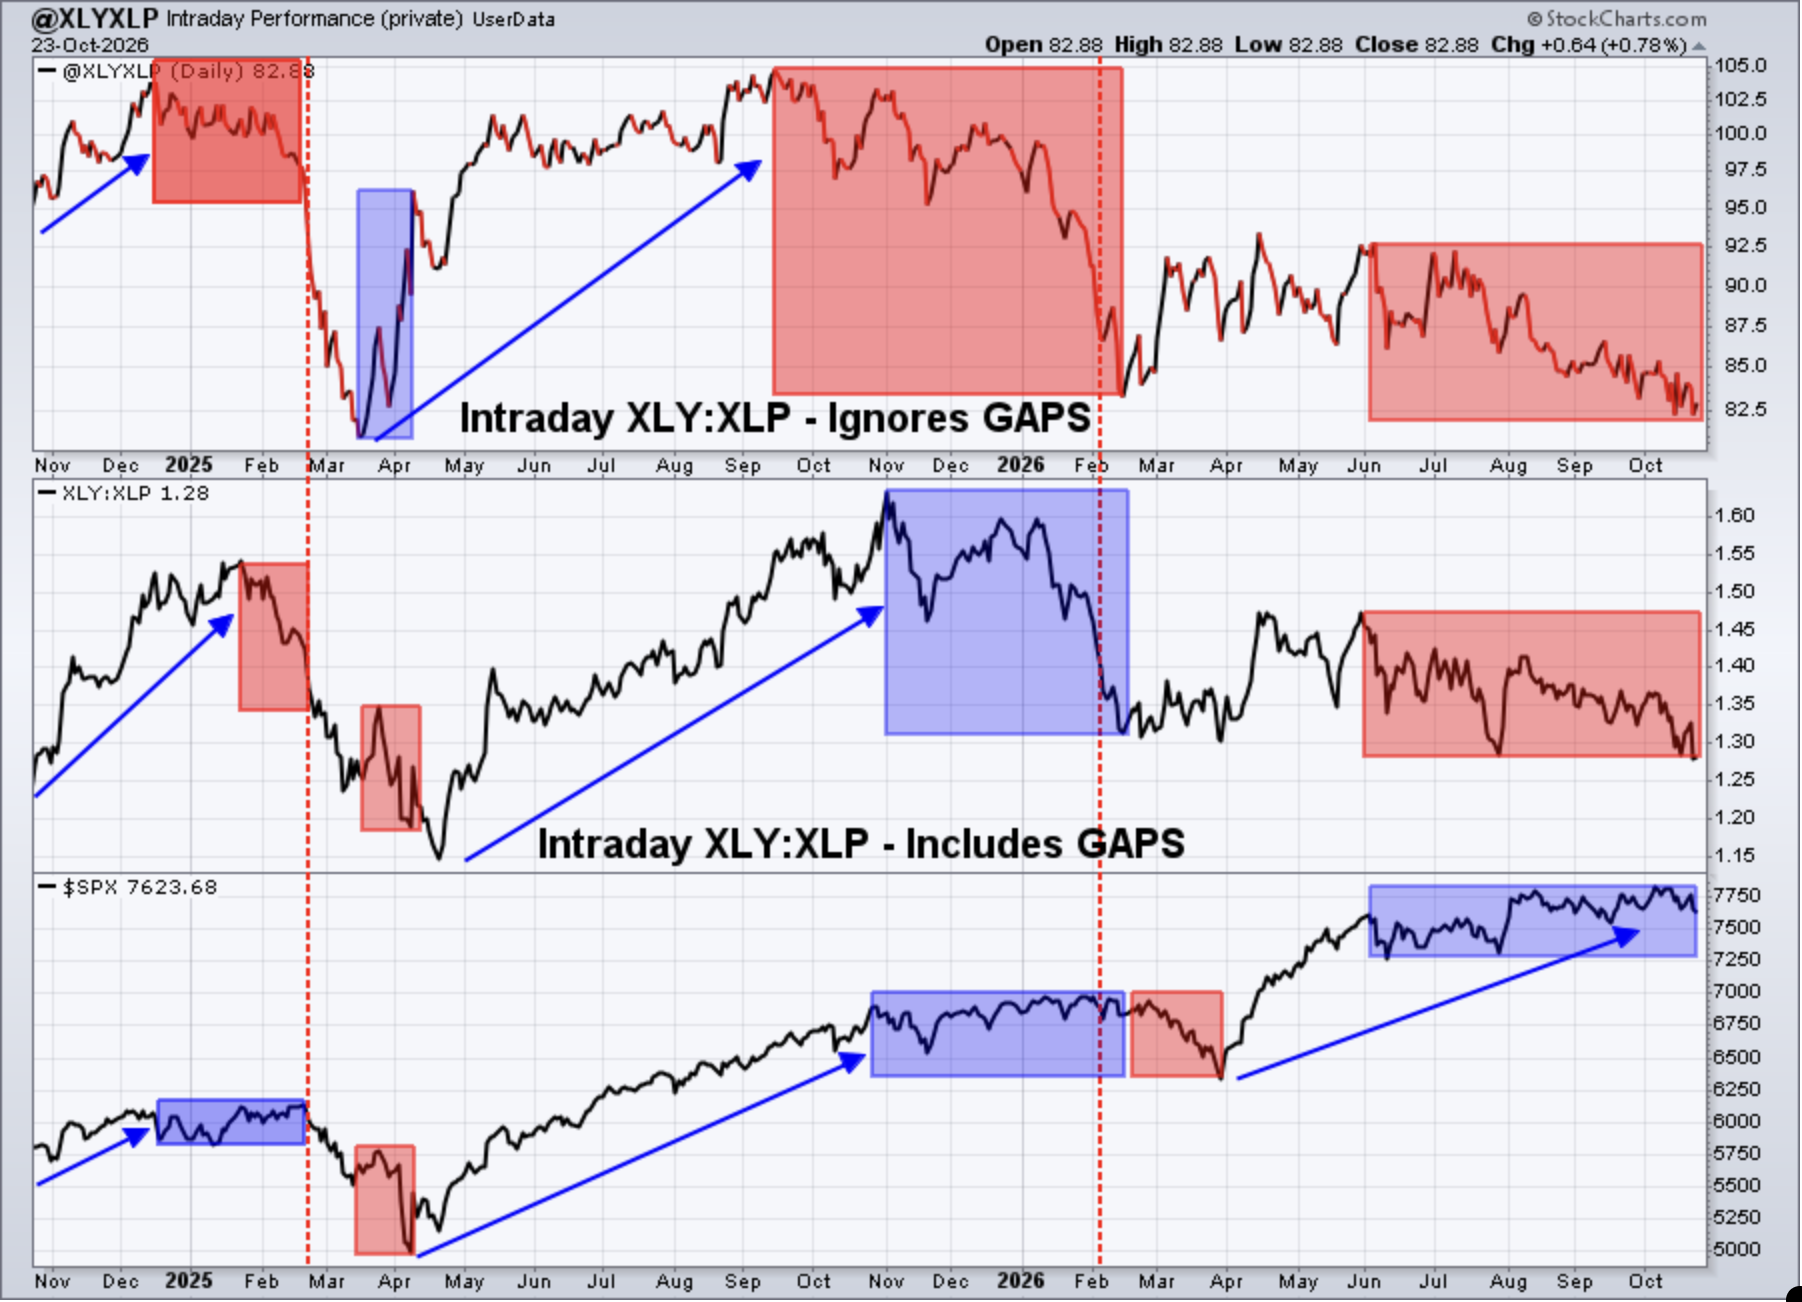
Consumer stocks remain under some relative pressure, though we did see consumer staples (XLP) move to an all-time high last week. Based on everything I look at, I fully expect the consumer discretionary area to begin showing relative strength sometime in Q4, and especially in 2027.
XLP 30-Day Cumulative Signal
Based on more than 25 years of back-tested data, I'm not going to consider this signal bearish unless it reaches the 106 level. Every major market downturn this century, other than the COVID pandemic, has seen this signal reach 106.
Here's where this signal currently resides:
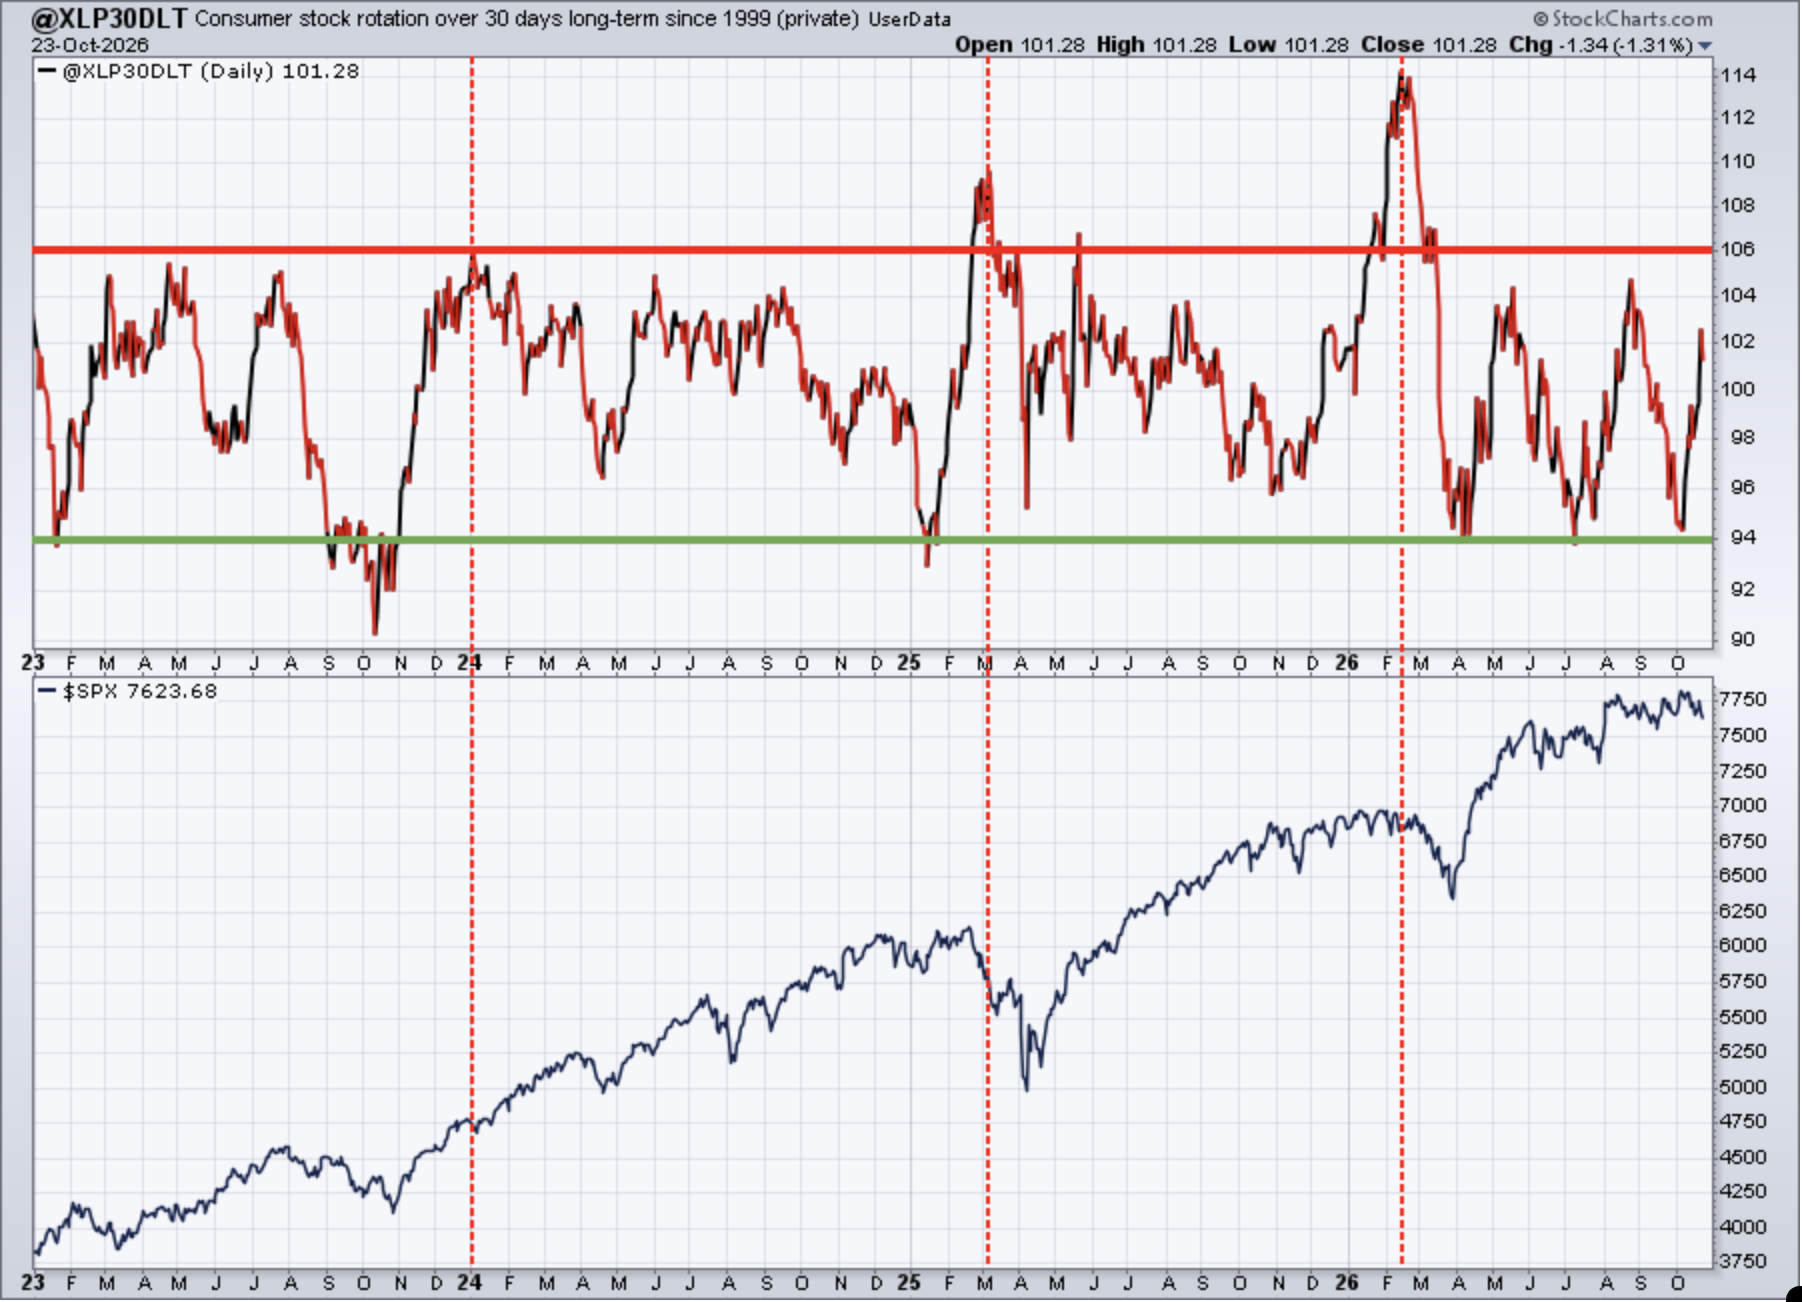
We're on the move higher, but keep two things in mind. First, we're not at the 106 level, which has been a historical requirement for market tops this century - and it just makes good common sense. Wall Street must re-position their holdings into defensive areas, PRIOR to a major market top, in order to gain the most benefit from that ensuing correction or bear market. Second, and this is very important, not every 106 reading means that the market is topping. If every area of the stock market is rising, sometimes this cumulative intraday XLP reading will hit 106 and the stock market remains very bullish.
Sentiment
5-day SMA ($CPCE)
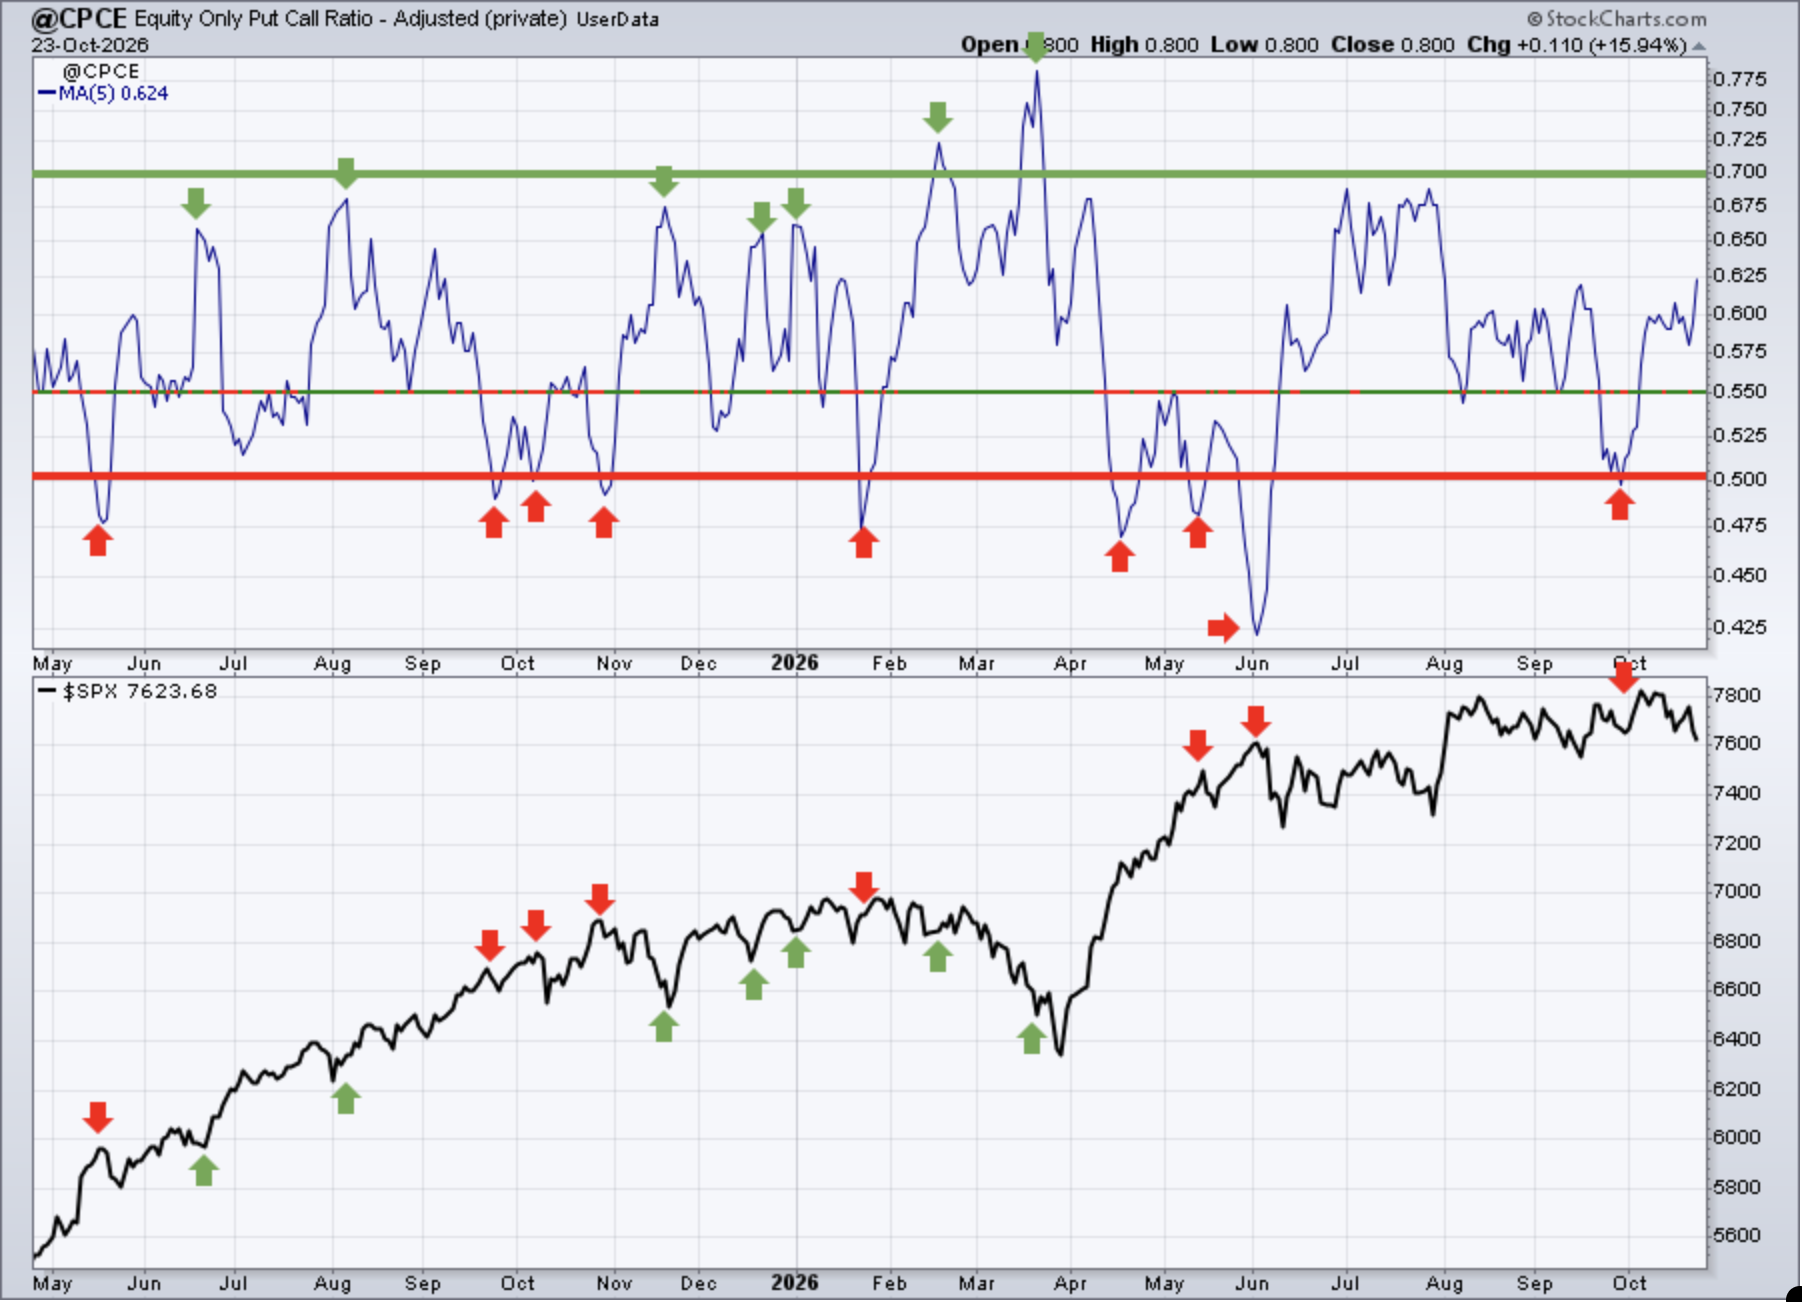
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
The selling from Thursday and Friday did result in this sentiment indicator moving up quickly. However, it still sits in the middle of neutral and is telling us very little about short-term market direction. A move into the 0.70s might be a different story, but it's unlikely to get there, especially if historical bullishness kicks in this week.
253-day SMA ($CPCE)
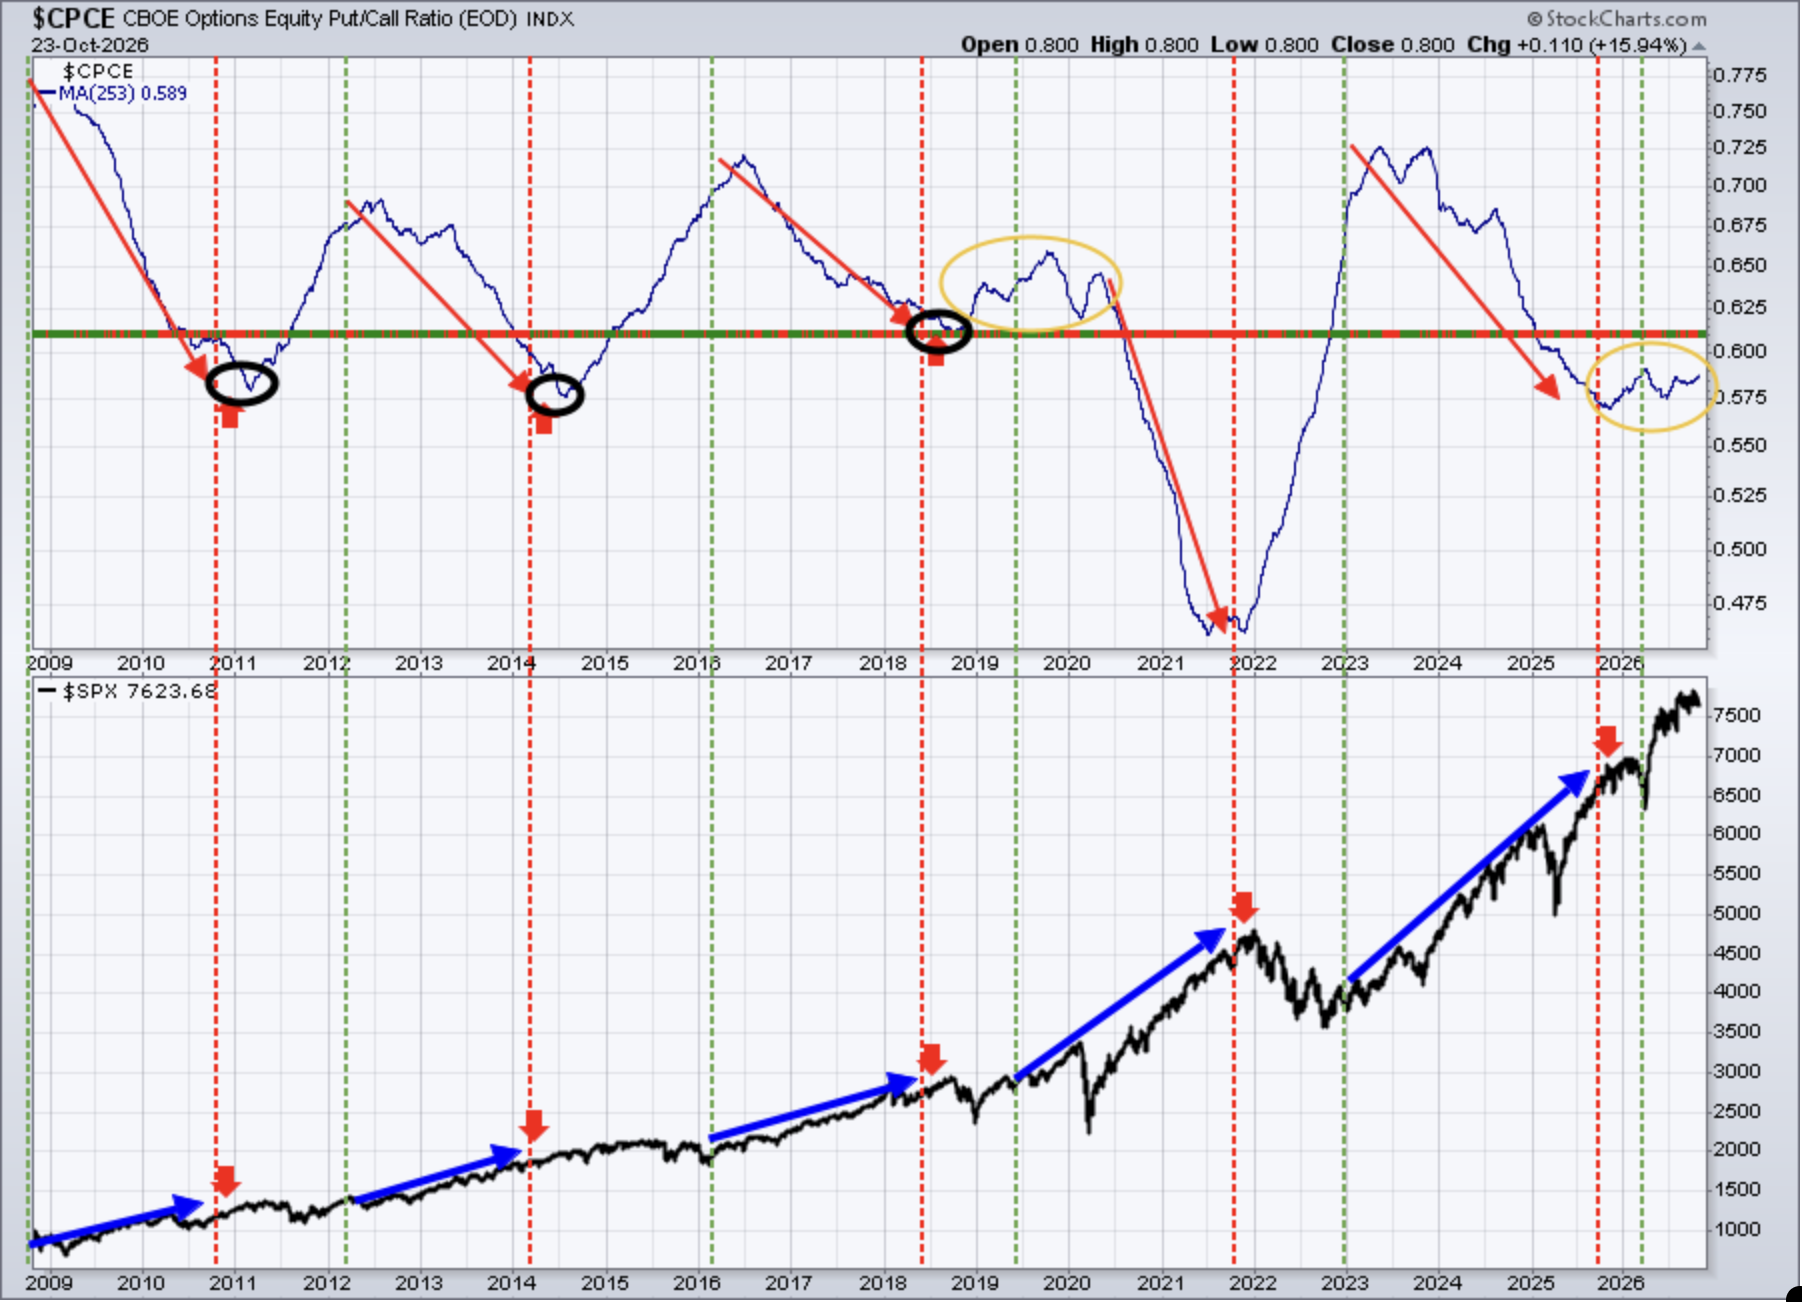
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500.
We might have to wait a bit longer before this chart tells us much of anything. The back and forth action suggests perhaps a struggle in the S&P 500, but I wouldn't be looking for any major selloff at this time.
Long-Term Trade Setups
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month, and below is how I viewed each MONTHLY chart as of Monday, October 5th:
- JPM - pulling back with neg divergence, let's watch 20-month EMA at 300
- BA - monthly RSI has been between 40 and 60 for 4 years. Enough said.
- FFIV - more new highs being reached, bullish
- MA - mentioned last month handle could form to 500, just about there
- GS - neg divergence suggested caution in Sept and GS fell 10%, watch 830 level
- FDX - excellent long-term support from 240-265
- AAPL - now slightly overbought, but uptrend is very strong
- CHRW - losing 20-month EMA support, so could see drop to 110
- JBHT - recent selling should find support/buyers around 215
- STX - consolidation continuing after massive rally, remains bullish
- HSY - drop below 170 now brings 140 support into play potentially
- DIS - every move up for past decade seems to get little follow through
- MSCI - very lengthy consolidation, excellent support in 500-520 range
- SBUX - 5-year consolidation still in play, need break above 112 or so
- KRE - on 2-month losing streak, but still trades comfortably above 20-mo EMA
- ED - currently trading in uptrend, near both price support and 20-month EMA
- AJG - September reversal lower now suggesting further consolidation ahead
- NSC - cup with handle breakout still bullish, but look for 20-month EMA test
- RHI - never quite reached 250 resistance, now rolling over again
- ADM - hit 2022 resistance, expect downside to 20-month EMA closer to 70
- BG - pullback to 20-month EMA looks like solid long-term entry point
- CVS - given strong monthly PPO, further selling to 20-day EMA buyable
- HRL - monthly pos divergence, which suggests selling momentum slowing
- DE - gaining strength and momentum, looks to head higher
- LULU - something just isn't right here, no relief; look to 80 for next support
- TTD - removing TTD going forward, renewed selling below 13 very bearish
- META - challenged all-time high in September, regaining strength
- ADBE - 20-month EMA not quite reached, rolling over again
- KMB - 115 resistance stalled advance, now looking to hold 90 support
- ORCL - held major long-term support at 115, trading on its 50-month SMA
- ABBV - strengthening, rising 20-month EMA should continue to offer support
- MCD - monthly RSI now under 35, very oversold, could see trip to 210
- MKC - breaking below May low with yield now over 4.25%; interesting buy
- TSCO - monthly PPO very weak, bounce short-lived, could 20 be possible?
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: VZ ($188 billion), WELL ($171 billion), CDNS ($85 billion), NUE ($59 billion), CLS ($31 billion)
- Tuesday: V ($739 billion), KO ($410 billion), NVS ($298 billion), BA ($148 billion), STX ($146 billion)
- Wednesday: GOOGL ($3.97 trillion), MSFT ($3.87 trillion), GEV ($220 billion), KLAC ($193 billion), APH ($180 billion), FTNT ($127 billion)
- Thursday: AMZN ($2.70 trillion), LLY ($1.23 trillion), MA ($555 billion), INTC ($431 billion), CAT ($324 billion), SNDK ($182 billion)
- Friday: XOM ($739 billion), ABBV ($504 billion), CVX ($448 billion), AZN ($267 billion), GD ($95 billion)
Key Economic Reports
- Monday: None
- Tuesday: September durable goods, September new home sales, August Case-Shiller home price index, October consumer confidence, FOMC meeting begins
- Wednesday: September wholesale and retail inventories, FOMC meeting ends with policy decision at 2:00pm ET
- Thursday: Initial jobless claims, Q3 GDP initial estimate, September personal income & spending, September PCE index
- Friday: Q3 employment cost index, October Chicago PMI
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Oct 26: -60.52% (Ex: cumulative gains =
-12.92% over 54 trading days since 1950. -12.92% x 253/54 = -60.52%) - Oct 27: -19.78%
- Oct 28: +124.30%
- Oct 29: +75.31%
- Oct 30: +51.71%
- Oct 31: +10.56%
- Nov 1: +47.70%
- Nov 2: +79.69%
- Nov 3: +97.04%
- Nov 4: +43.73%
- Nov 5: +78.00%
- Nov 6: -16.85%
- Nov 7: -6.57%
- Nov 8: +22.15%
NASDAQ (since 1971)
- Oct 26: -115.08%
- Oct 27: -59.60%
- Oct 28: +162.80%
- Oct 29: +69.43%
- Oct 30: +17.62%
- Oct 31: +78.75%
- Nov 1: +46.72%
- Nov 2: +101.17%
- Nov 3: +98.38%
- Nov 4: +87.56%
- Nov 5: +110.28%
- Nov 6: +30.04%
- Nov 7: -31.79%
- Nov 8: -4.82%
Russell 2000 (since 1987)
- Oct 26: -13.96%
- Oct 27: -127.63%
- Oct 28: +187.91%
- Oct 29: +62.01%
- Oct 30: +6.72%
- Oct 31: +123.52%
- Nov 1: +7.94%
- Nov 2: +133.34%
- Nov 3: +164.65%
- Nov 4: +56.52%
- Nov 5: +80.33%
- Nov 6: +74.19%
- Nov 7: -66.50%
- Nov 8: +26.02%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Well, the most bearish historical week of the year kicked off on Thursday and we immediately saw a hit to our major indices. Both the S&P 500 ($SPX) and NASDAQ 100 ($NDX) were down, with the SPX down nearly 2%, while the NDX dropped close to 3%. Semiconductors ($DJUSSC) remained weak, which clearly puts pressure on these two major indices, because the group is the largest in both indices based on market caps.
Here's what I'll be thinking about and watching this week:
Earnings. Q3 earnings will step it up this week as we'll hear from a few of the Mag 7 stocks - Alphabet (GOOGL) and Microsoft (MSFT) on Wednesday afternoon and Amazon.com (AMZN) on Thursday afternoon. Earnings, thus far, have been strong and fully support current valuations, in my opinion.
Seasonality. This Tuesday's close marks the beginning of the most bullish historical period of the year. Since 1950, the S&P 500 has closed higher on January 18th than it was at the close on the prior October 27th (Tuesday) 67 of the last 76 years. The NASDAQ has done so 45 of the last 55 years, and the Russell 2000 has closed higher during this period 34 of the last 39 years.
Since 1988, here is the average return for each index during this upcoming period:
- S&P 500: +4.85%
- NASDAQ: 6.80%
- Russell 2000: +6.61%
Furthermore, the October 28th through November 5th period is one of the best of the year as well. On the S&P 500, this period has produced an annualized return of +67.29%, more than 7x the normal 9% return.
Interest Rates. The 10-year treasury yield ($TNX) has been trending lower since we saw two hot inflation reports for the month of September. I suggested at the time that it could very well be the top in the TNX. So far, that's been true and the TNX is now 40 basis points below its recent high.
Fed Meeting. The odds are stacked AGAINST a rate hike this month, so the real emphasis, in terms of market reaction to the meeting, is likely to be based upon what is said by Fed Chief Warsh. We already know, however, that he doesn't say a lot. I suspect the verbiage to be rather standard - that the Fed remains committed to bringing inflation down to an acceptable level and that the overall economy remains resilient, allowing the Fed to do its job on inflation without significantly impacting the jobs market.
Happy trading!
Tom